


EN
Zai Lab (ZLAB) Stock Looks Above Fair Value On Current Sales
Zai Lab has seen a wide range of outcomes for holders over the past few years, which puts fresh focus on a simple question for anyone looking at the stock today. Is the current share price sensibly anchored to what the business is generating in sales?
- Over the past 5 years, the share price has fallen 73.5%, which puts extra weight on whether the revenue base can justify where the stock now trades.
- Recent trial results for zocilurtatug pelitecan in extensive-stage small cell lung cancer and a US$250 million private placement may support expectations around future oncology sales and the timing of cash needs.
- The analysts covering Zai Lab have run their own numbers. See what analysts think Zai Lab's shares could be worth.
The issue now is whether Zai Lab's current valuation makes sense when lined up against the scale and trajectory of its sales.
For a wider watchlist beyond Zai Lab, you could also scan for other oncology focused companies using the 35 healthcare AI stocks.
Is Zai Lab Getting Expensive on Sales?
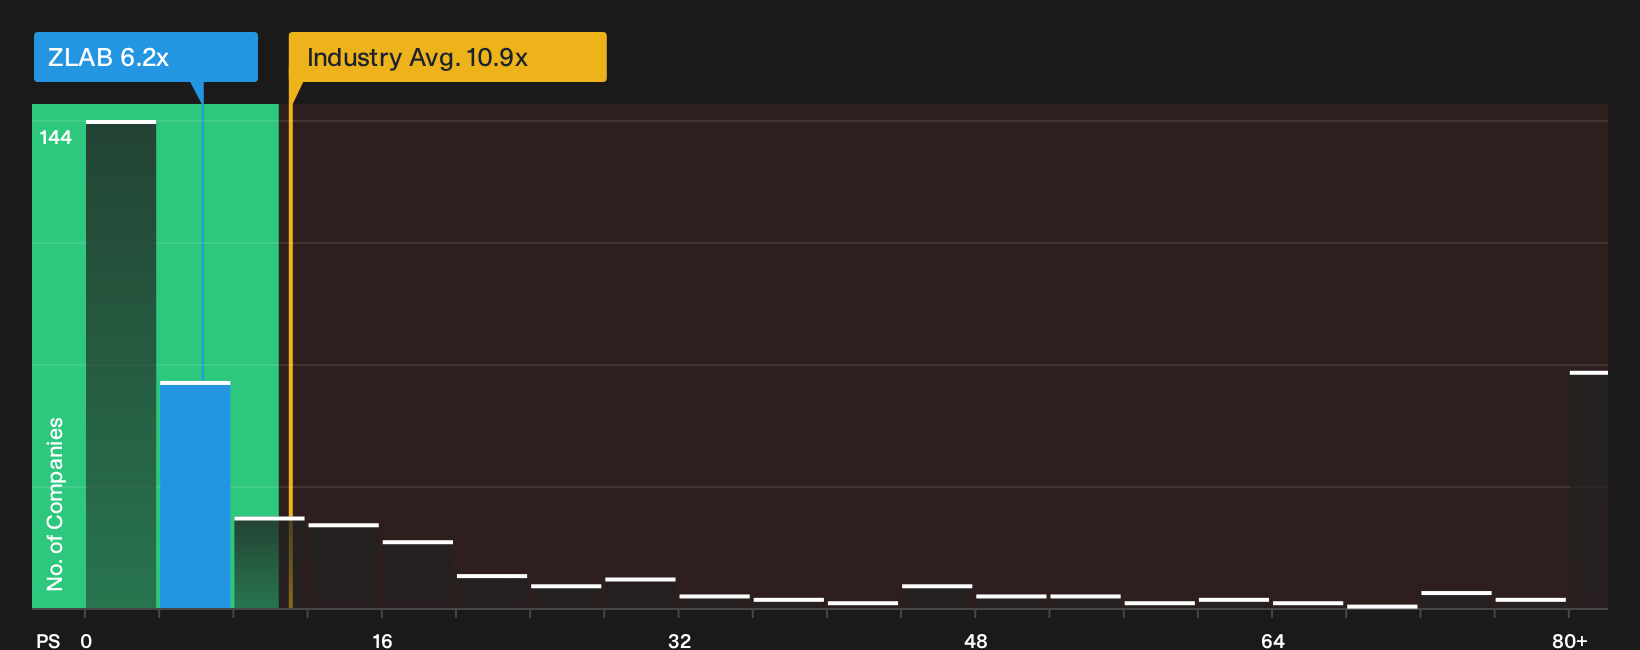
P/S is the cleaner yardstick for Zai Lab because the business is still loss making and investors are mostly paying for access to its oncology revenue stream. On that lens, the stock trades on a P/S ratio of 6.2x, compared with about 10.9x for the wider biotechs group and roughly 10.2x across closer peers.
The fair multiple implied by Simply Wall St’s model, which blends Zai Lab’s growth prospects, margins, scale and risk profile, sits below where the shares currently change hands. As a result, the stock screens as overvalued on this framework even though it is at a discount to broad sector and peer averages. Because the recent zocilurtatug pelitecan news and US$250 million private placement focus attention on future oncology sales, it is worth asking whether that pipeline potential is enough to justify paying a richer multiple than the model suggests. Explore the numbers behind Zai Lab's P/S valuation.
The Zai Lab Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for Zai Lab leaves off by spelling out which paths for growth, margins and future earnings would need to hold for the shares to look materially richer or cheaper than today’s price. Each idea treats Zai Lab's fair value as a thesis about the business that can be revisited over time, rather than a single frozen snapshot.
One of the top community narratives on Zai Lab: 7% undervalued
"The main factor that has to go right is that Zai Lab turns its emerging global pipeline, led by Zoci and newer internally discovered assets, into successful approvals…"
Discover why this Narrative puts Zai Lab at 7% undervalued.
An unanswered question for Zai Lab sits a few years down the road
Analyst projections provide a different lens on where Zai Lab might be heading over the next few years, and they offer a reference point to compare with today’s pricing. Explore where analysts expect Zai Lab to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com