


EN
Killam Apartment REIT (TSX:KMP.UN) Results Test Whether Its Valuation Still Looks Cheap
Killam Apartment REIT (TSX:KMP.UN) just reported third quarter 2026 results, highlighting higher same property NOI, 97.3% apartment occupancy, a $50.5 million asset sale, and unit buybacks under its normal course issuer bid.
At a share price of CA$17.94, Killam Apartment REIT has posted a 7 day share price return of 5.1% and a year to date share price gain of 9.1%. Its 1 year total shareholder return of 11.5% and 3 year total shareholder return of 20.4% suggest momentum that has softened slightly in recent months after a 90 day share price decline of 4.9%.
Compare Killam Apartment REIT’s momentum and capital recycling story with a curated 6 high quality undervalued stocks that share solid fundamentals and may be setting up for their next move.
After a sharp 7 day rebound and a recent soft patch over 90 days, the real tension for Killam Apartment REIT is simple: Does CA$17.94 still sit meaningfully below fair value estimates, or has that gap mostly closed?
Price-to-Earnings of 122.2x: Is it justified?
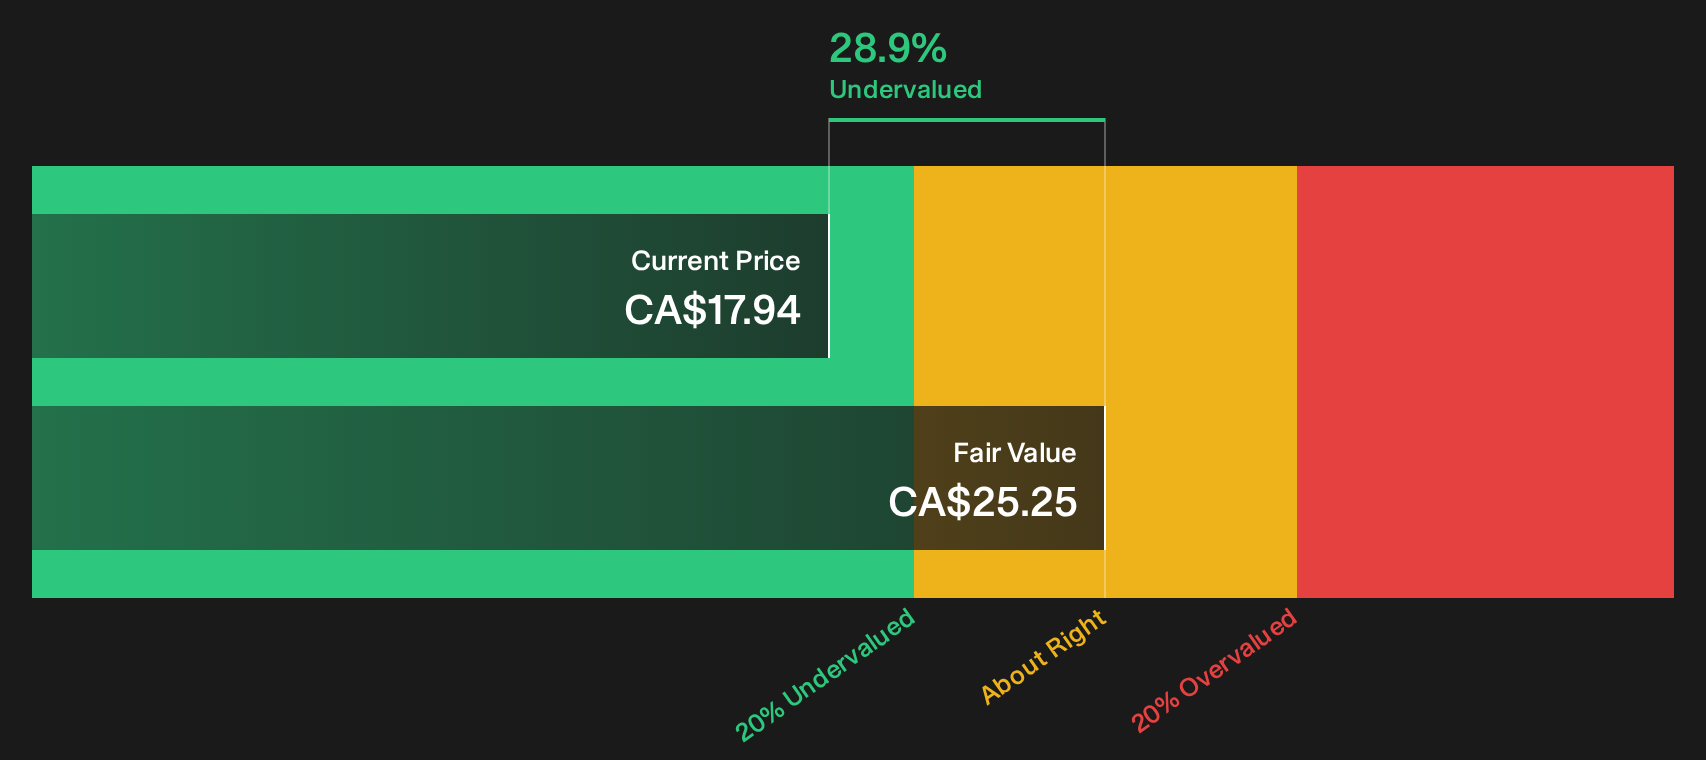
On the numbers, Killam Apartment REIT trades at a P/E of 122.2x, which is a high figure relative to many listed real estate trusts and sits against a last close of CA$17.94 that is also 28.9% below an internal future cash flow estimate of CA$25.25.
The P/E ratio compares the current unit price to earnings per unit and gives a quick sense of how much investors are paying for each dollar of profit. For a residential REIT like Killam Apartment REIT, that means the P/E helps you see how current earnings stack up against the market price in a sector where investors often focus on steady income streams and asset backing.
Here, the data points are pulling in different directions. The trust is flagged as expensive on a P/E of 122.2x compared to a Canadian peer average of 12.8x and a global residential REIT average of 17.3x, while at the same time being described as trading at a 28.9% discount to an estimated future cash flow value of CA$25.25 from the SWS DCF model.
Result: Price-to-Earnings of 122.2x (OVERVALUED)
See what the numbers say about this price — find out in our valuation breakdown.
Still, the story around Killam Apartment REIT can change quickly if property values soften or if higher interest costs weigh on acquisition and development plans.
Find out about the key risks to this Killam Apartment REIT narrative.
Another View: Cash Flow Suggests Killam Apartment REIT Looks Cheap
The first check flags Killam Apartment REIT as expensive on a 122.2x P/E, yet the SWS DCF model paints a very different picture. From that cash flow perspective, CA$17.94 is 28.9% below an estimated value of CA$25.25. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Killam Apartment REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Killam Apartment REIT so far. If you want a clearer picture, go straight to the underlying data and weigh both sides of the story using the 1 key reward and 5 important warning signs
Looking for more investment ideas beyond Killam Apartment REIT?
Do not stop your research with one REIT. Broaden your watchlist with a few targeted filters that can surface ideas you might not otherwise spot.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (5 results) that screens for financial strength first.
- Hunt for potential mispricings by running through a 7 high quality undiscovered gems that focuses on quality businesses that are not widely followed.
- Sharpen your income shortlist by using a 3 dividend fortresses that highlights higher yielding payers with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com