


EN
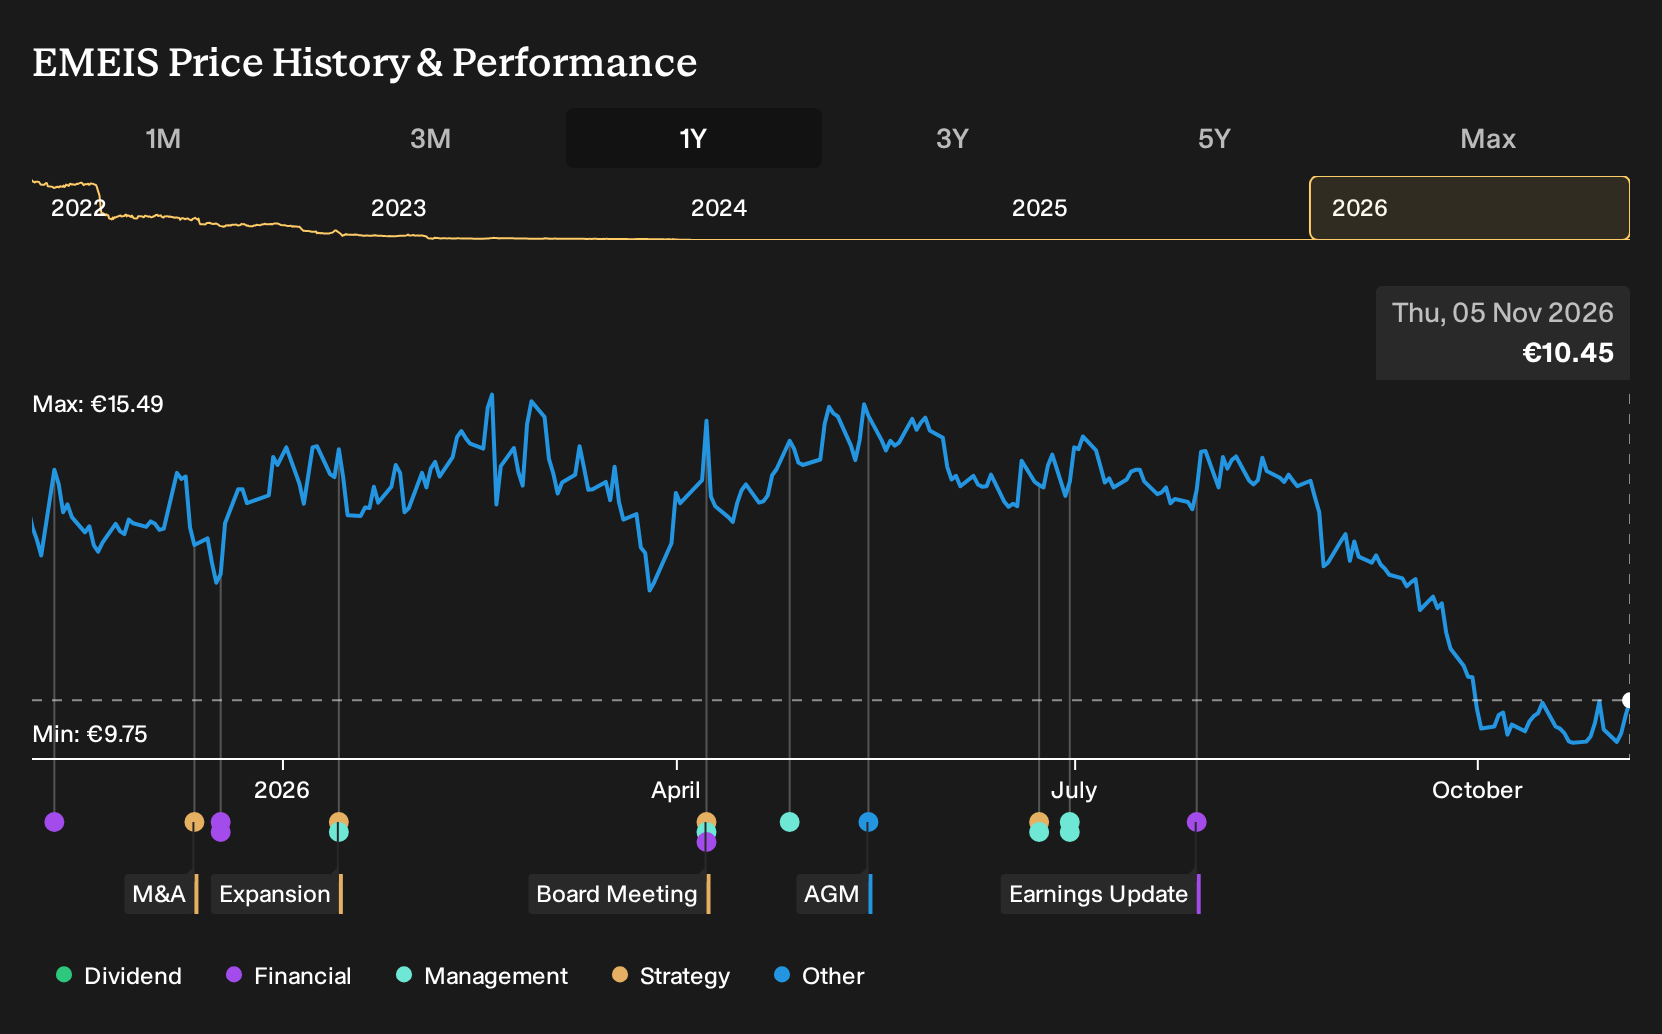
How Q3 Sales Update At Emeis Société Anonyme (ENXTPA:EMEIS) Has Changed Its Investment Story
- emeis Société anonyme held its Q3 2026 sales and trading statement call on 29 October 2026, providing fresh detail on recent operating and commercial trends across its European elderly care and healthcare facilities.
- The update gave investors an opportunity to reassess emeis Société anonyme's progress on occupancy, pricing and operational execution in the context of its longer term turnaround and deleveraging goals.
- This article considers how emeis Société anonyme's investment narrative is influenced by the fresh Q3 trading detail from its recent sales call.
Scan how emeis Société anonyme is reshaping its operations after the Q3 2026 sales call, then benchmark it against list of solid balance sheet and fundamentals (194 results) that may handle similar pressures differently.
emeis Société anonyme Investment Narrative Recap
To own emeis Société anonyme, you need to believe its European care facilities can keep lifting occupancy, hold pricing, and translate that into steadier EBITDA even while the group remains loss making today. The Q3 2026 call mainly refreshed that operational story. Unless management flagged a clear break in occupancy or pricing trends, the immediate thesis likely remains intact.
In the near term, the key catalyst is still operational follow through, especially at underperforming sites and in markets under regulatory pressure. The biggest current risk is execution on the turnaround while carrying roughly €3.8b of debt, since any stumble on occupancy or cost control would quickly tighten financial headroom.
With no new major corporate announcements around the Q3 sales call, the most relevant reference point is still management’s ongoing plan to lighten the balance sheet through real estate partnerships and disposals. That program matters directly for the equity story because it shapes interest costs, refinancing options, and room to invest in care quality.
For you as a shareholder, progress on asset sales and partnership structures interacts directly with the Q3 operational detail. Stable or improving facility level trends can support valuations in healthcare real estate, which in turn influences how quickly emeis Société anonyme can reduce leverage and narrow its losses, a core piece of the medium term catalyst path.
emeis Société anonyme's current loss of €298.4 million is set against analyst expectations for earnings of €30.8 million by 2029. This implies an earnings swing of roughly €329 million on forecast revenues of €6.6 billion, based on an assumed revenue growth rate of 3.8% per year.
Uncover why emeis Société anonyme's fair value indicates a 58% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts maintenance capex at the center. Some worry that higher renovation spending absorbs much of the EBITDA progress, so earnings stay weak even if occupancy and pricing look better. Those more cautious analysts were assuming revenue of about €6.8 billion and earnings of roughly €165.9 million by 2029 before this Q3 2026 call. Their story could shift once they rework the numbers.
Explore 2 other emeis Société anonyme fair value estimates, including one that suggests it could be worth just €16.30!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your emeis Société anonyme research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for emeis Société anonyme. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate emeis Société anonyme's overall financial health at a glance.
Looking For More Investment Ideas Beyond emeis Société anonyme?
If you want to stress test your emeis Société anonyme view against other opportunities, use the Simply Wall St Screener to scan for different return and risk profiles that might suit your approach better.
- For investors who care most about quality at a sensible entry point, run your filters against 211 high quality undervalued stocks that already clear a high bar on fundamentals.
- If capital preservation sits high on your priority list, compare emeis Société anonyme with 215 resilient stocks with low risk scores that score well on balance sheet resilience and earnings stability.
- When you want fresh ideas off the beaten path, broaden your watchlist with 592 high quality undiscovered gems that combine solid metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com