


EN
Is Torex Resources (TSX:TXR) Cheap On Strong Q3 Earnings And Cash Flow?
Torex Resources (TSX:TXR) just posted third quarter 2026 earnings, reporting net income of US$155.2 million and basic earnings per share from continuing operations of US$1.68, both above last year’s levels.
The latest move in Torex Resources reflects that shift in earnings power. The share price has climbed 6.81% in the last day and 17.47% over 90 days, while the 1 year total shareholder return of 23.48% and a very large 3 year total shareholder return indicate that momentum has been strong over a longer horizon.
Scan how Torex Resources compares with other precious metals producers by reviewing the hand picked 33 elite gold producer stocks benefiting from stronger earnings trends and active project pipelines.
Torex Resources has already rewarded holders with strong multi year returns and a sharp recent move. The next step is to test whether the current price still leaves meaningful upside on the table or largely reflects the story.
Most Popular Narrative: 21% Undervalued
The most followed narrative pegs Torex Resources at a fair value of CA$93.70, set against the last close of CA$73.71. This suggests a clear valuation gap for investors to interrogate.
The current valuation implies the share price does not fully reflect Torex Gold Resources being debt free with over $500 million of liquidity, a large planned 2026 capital return program, and a pipeline of debottlenecking and Los Reyes growth options.
See why 35 investors see Torex Resources as 21% undervalued.
Result: Fair Value of CA$93.70 (UNDERVALUED)
Still, Torex Resources depends heavily on controlling all-in sustaining costs and turning higher 2026 sustaining and exploration spending into genuine productivity and cash flow gains.
Find out about the key risks to this Torex Resources narrative.
Another View On Torex Resources’ Value
That 21% gap to the CA$93.70 fair value hinges on analyst scenarios. A different lens, the SWS DCF model, points to a present value for future cash flows of about CA$72.53 per share, slightly below the current CA$73.71 price. This frames Torex Resources as modestly overvalued on this measure.
This contrast between an earnings based fair value and a cash flow based estimate raises a simple question for you: Which matters more for your thesis, the projected profit profile or the cash that might actually make it back to shareholders over time?
Look into how the SWS DCF model arrives at its fair value.
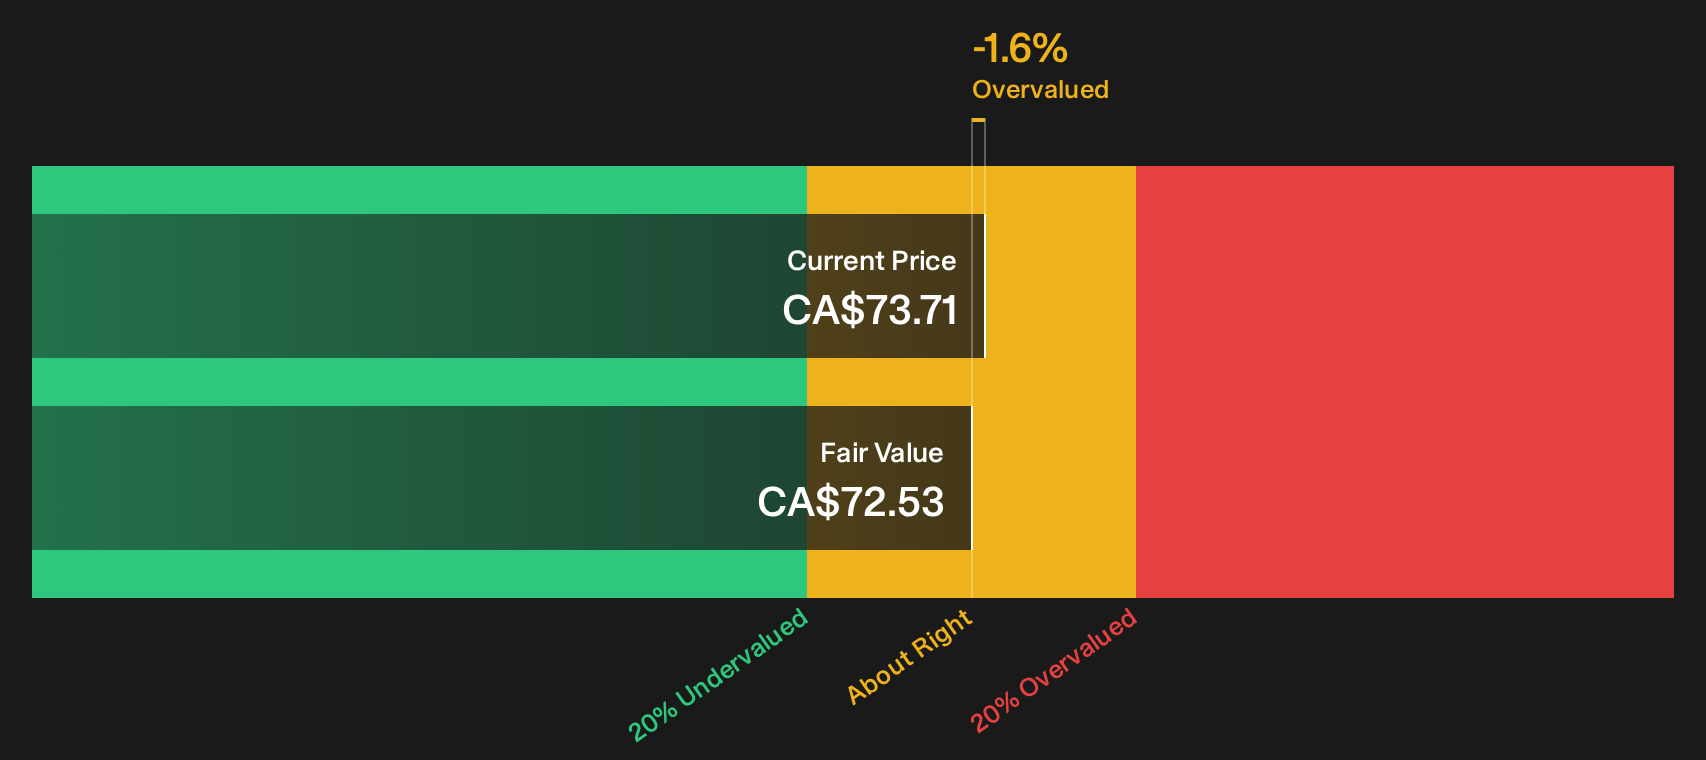
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Torex Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Torex Resources is clearly optimistic, yet the real edge comes from checking the numbers yourself and deciding quickly where you stand. To see what is driving that optimism, review the 5 key rewards.
Looking for more investment ideas beyond Torex Resources?
If Torex Resources has your attention, do not stop there. Use the Simply Wall Street Screener to quickly surface fresh candidates that fit your own criteria.
- Target potential bargains by scanning companies that appear mispriced on quality and valuation using the 6 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on businesses with robust payout profiles through the 3 dividend fortresses.
- Dial down portfolio risk by focusing on financially resilient businesses through the 8 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com