


EN
3 Australian Undervalued Stocks Trading Up To 49% Below Fair Value
AI related stocks have just taken a beating as markets question how much should be paid today for stories about tomorrow. When sentiment cools on big themes, attention often shifts to quieter Australian businesses that already generate cash and trade below some estimates of fair value. This article looks at three such opportunities from a cash flow focused screener that may appeal to patient, value driven investors.
The stocks highlighted below are just a small sample from this idea, and the wider screen surfaced 4 more companies with similarly cash rich stories that are not covered here. To identify and analyze those extra candidates alongside your own short list, head straight into the Undervalued Stocks Based On Cash Flows screener.
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group produces and sells liquefied natural gas and other hydrocarbons, using long-life LNG projects as its main cash engine.
Operations: Woodside Energy Group generates around A$7.3b from Australia, A$4.6b from International operations and A$1.9b from Marketing activities.
Market Cap: A$58.2b
For this screener, Woodside Energy Group matters because its LNG projects generate cash today while new developments extend the expected duration of those cash flows.
"Expectations that Woodside Energy Group will bring the Scarborough project into production around Q4 2026 and ramp up volumes support the idea that future LNG sales and associated revenue are already partially reflected in the current valuation."
The key question is what happens if one cost and execution program reshapes how much of those LNG-driven cash flows ultimately reach shareholders.
That tension between project risk and eventual cash returns is exactly what sits at the heart of the full narrative for Woodside Energy Group, where capital allocation, contract structure, and LNG pricing power come into sharper focus.
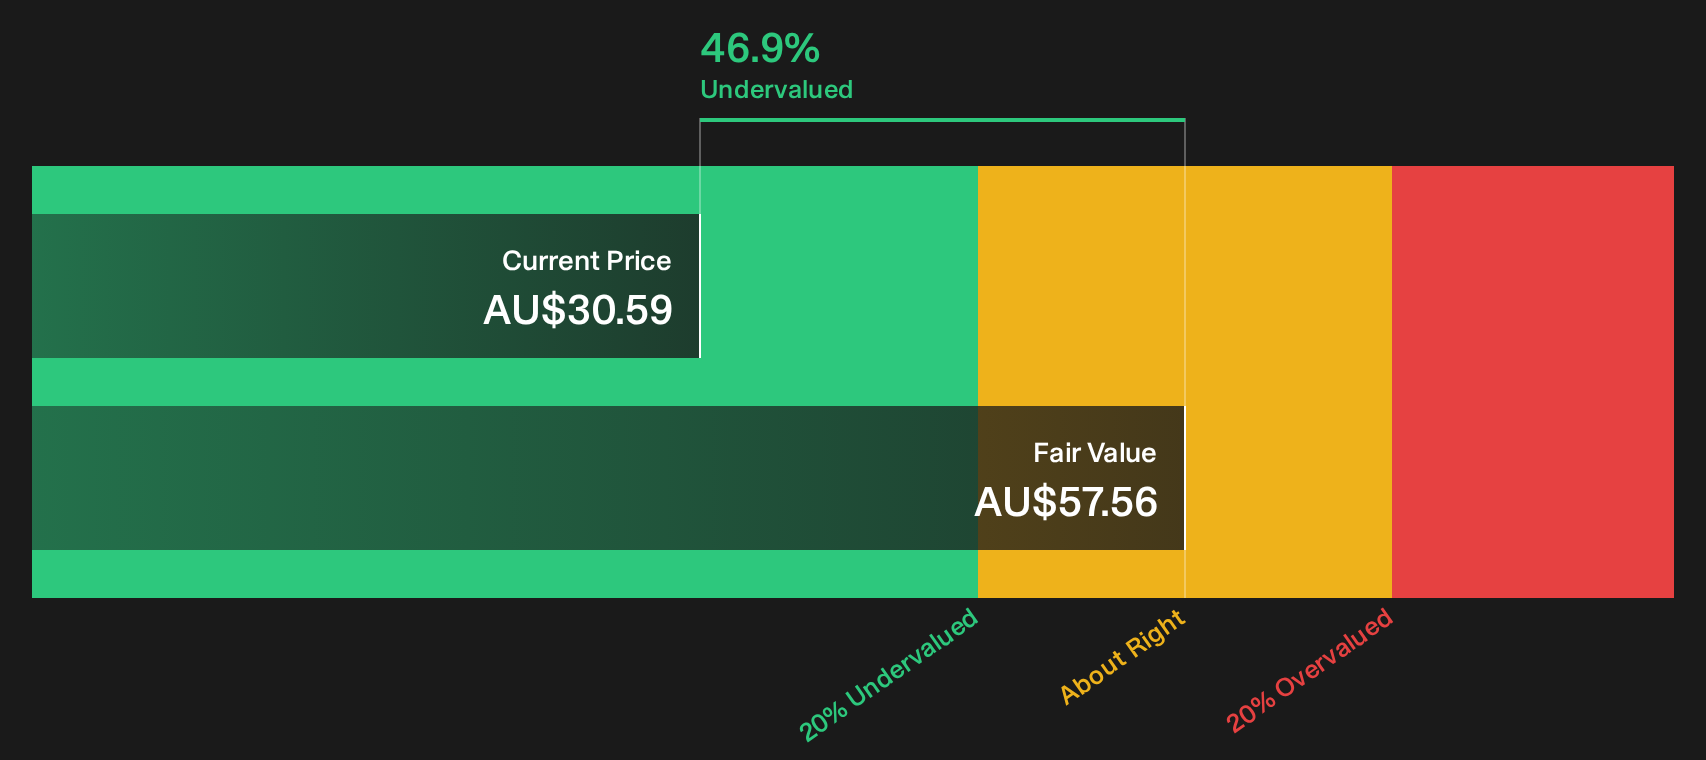
Origin Energy (ASX:ORG)
Overview: Origin Energy supplies electricity and gas, produces natural gas and LNG, and runs integrated energy services that collectively drive cash generation.
Operations: Origin Energy earns about A$15.3b from Energy Markets and A$307m from Integrated Gas, with utilities activity anchoring its revenue mix.
Market Cap: A$20.9b
Origin Energy fits this cash flow focused screen because its integrated retail energy and LNG activities already generate meaningful, recurring cash that underpins its valuation story.
"Continued growth in rooftop solar, home batteries and the 1.6 GW virtual power plant, supported by rising adoption of customer electrification products, can shift more consumption behind the meter and reduce grid supplied volumes. This affects wholesale and retail earnings visibility."
The real swing factor for Origin Energy is how efficiently it turns heavy spending on new projects into durable margins and reliable cash flows.
If that execution risk is what you are weighing, the full narrative for Origin Energy explains how Origin Energy’s cash engines could accelerate or stall from here.

Life360 (ASX:360)
Overview: Life360 runs a mobile-first Location & Safety platform where family-focused subscriptions anchor recurring cash flows, with Tile hardware as a smaller add-on.
Operations: Life360 generates about $572.6 million from Software & Programming, with reported geographic contributions of $500.3 million in Segment Adjustment and $72.2 million internationally.
Market Cap: A$5.6 billion
Life360 matters for this cash flow focused list because its paid Location & Safety memberships turn everyday family habits into predictable subscription income.
"Early-stage high-margin advertising and data partnerships are now supported by Life360's scaled audience and reported campaign lift, with call-to-action rates up to 47% higher for some clients and over 40% higher store visits for a grocery chain."
The real swing factor is how one unseen pressure around monetizing a largely free user base ultimately shapes margins and long-run cash flows.
That pressure point is exactly why the full narrative for Life360 explores how Life360 could convert its free users into increasing cash generation while maintaining and building on user engagement.

Seeking Fresh Alternatives Before Others?
New ideas move fast. By the time a breakout story hits the front page, early momentum is already flying. Scan these fresh lists while it matters and get in early.
- Spot stronger income candidates and stress test your watchlist against the curated 5 dividend fortresses before payout trends get fully priced in by the wider market.
- Track where real-world automation momentum is building by scanning the hand picked 90 robotics and automation stocks while these operators stay under the radar for now.
- Position ahead of potential infrastructure tailwinds by combing through the focused 40 power grid technology and infrastructure stocks before capital crowds into the same limited set of opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com