


EN
Did Strong Revenue Growth Just Shift Willis Lease Finance's (WLFC) Investment Narrative?
- Willis Lease Finance reported third quarter 2026 revenue of US$246.3 million and net income of US$11.7 million, with basic EPS from continuing operations of US$0.48, alongside a declared quarterly dividend of US$0.15 per share payable on November 25, 2026.
- Underlying operations showed mixed signals as lease rent reached a quarterly record and maintenance services revenue was very large compared with a year earlier, while net income and earnings per share for both the quarter and nine month period declined versus 2025 levels.
- Investors may consider how Willis Lease Finance's investment narrative could be influenced by strong revenue alongside weaker earnings in the third quarter.
Scan how Willis Lease Finance’s latest earnings mix of higher revenue and softer profit compares with peers by checking a curated list of list of solid balance sheet and fundamentals (25 results).
Willis Lease Finance Investment Narrative Recap
To stay invested in Willis Lease Finance, you need to be comfortable with a story where growing lease and maintenance activity eventually feeds through to cleaner earnings. Third quarter figures show strong revenue and record lease rent, but profit and EPS both declined versus 2025, so the short term focus is on whether margins can stabilize as newer engines and services scale.
The biggest near term swing factor is execution on that modern engine portfolio and maintenance build out, without letting finance costs and complex upkeep eat into returns. The key risk is that interest expense and maintenance on LEAP and GTF assets stay heavy, which would keep net margins compressed even if revenue keeps trending higher.
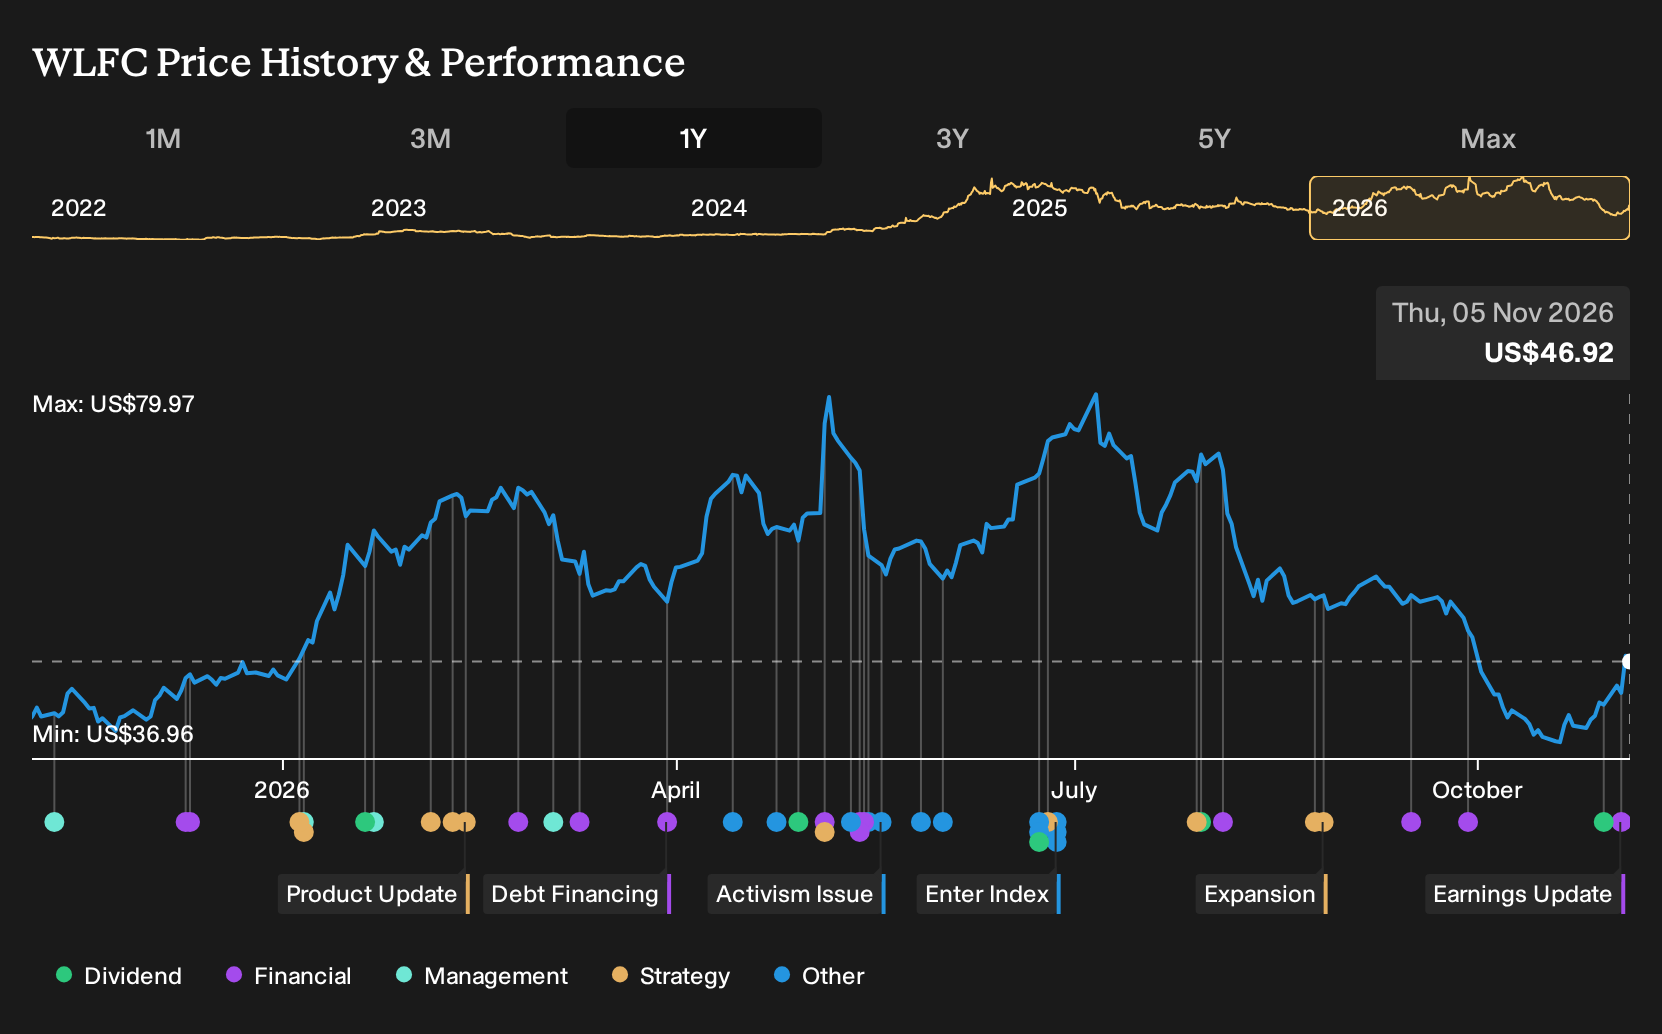
The fresh data point that ties closest to this story is the third quarter 2026 earnings release. Revenue for the period reached US$246.3 million compared with US$183.4 million a year earlier, while net income moved to US$11.7 million from US$24.3 million. That gap between top line growth and earnings sets the tone for how investors assess execution.
Lease rent hit a quarterly record at US$84.4 million and maintenance services revenue was very large compared with last year. This connects directly to the catalysts around a larger, more modern engine base and expanding MRO capability. At the same time, nine month EPS from continuing operations eased from US$4.82 basic to US$3.00, so anyone watching Willis Lease Finance now is likely weighing operating momentum against thinner profitability and interest coverage pressure.
Willis Lease Finance's current earnings are US$86.0 million and analysts project revenue growth of 4.0% a year, with revenues reaching US$847.8 million and earnings of US$135.9 million by 2029. That path implies an earnings increase of about US$49.9 million from today to the 2029 consensus forecast.
Learn how Willis Lease Finance's fair value identifies what some analysts view as a 50% potential upside to its current price before the market closes that gap.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Willis Lease Finance research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Willis Lease Finance. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Willis Lease Finance's overall financial health at a glance.
Looking for more investment ideas beyond Willis Lease Finance?
Once you have formed a view on Willis Lease Finance, it can help to compare that thesis with other companies that match the kind of balance sheet strength, income profile, or upside potential you want in your portfolio. The Simply Wall St Screener can narrow that universe down to a focused shortlist that actually fits your criteria instead of leaving you to scroll through endless tickers.
- If you care most about financial resilience and want counterparts with robust balance sheets and fundamentals, start by scanning a curated list of solid balance sheet and fundamentals (25 results) that meet those quality filters.
- For investors hunting for what could be mispriced quality, weigh your Willis Lease Finance view against a hand picked 42 high quality undervalued stocks that combine strong fundamentals with appealing valuations.
- If reliable income is your priority and you want to compare Willis Lease Finance with companies that focus more on cash returns, line it up next to a focused 6 dividend fortresses offering higher yields with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com