


EN
Global Payments (GPN) Stock Looks About Right As Shares Rose 26%
Global Payments has put in a solid run over the past year, helped by a potential US$40b buyout proposal and ongoing integration of its Worldpay acquisition. This naturally raises the question of whether the current share price lines up with what its earnings can reasonably support.
- The stock is up 26.0% over the past year, which puts more pressure on the earnings picture to justify where the valuation sits today.
- The proposed US$40b take private offer and the larger Worldpay footprint mean future profit streams, integration savings and a higher debt load all feed directly into how investors weigh the earnings power behind the current price.
- The analysts covering Global Payments have run their own numbers. See what analysts think Global Payments's shares could be worth.
The issue now is whether Global Payments' recent share price level is supported by the earnings it currently generates and what those earnings reasonably point to over time.
If you want a second reference point while comparing Global Payments with the proposed buyout and its earnings profile, apply the same analysis to 42 high quality undervalued stocks.
Is Global Payments Fairly Priced on Earnings?
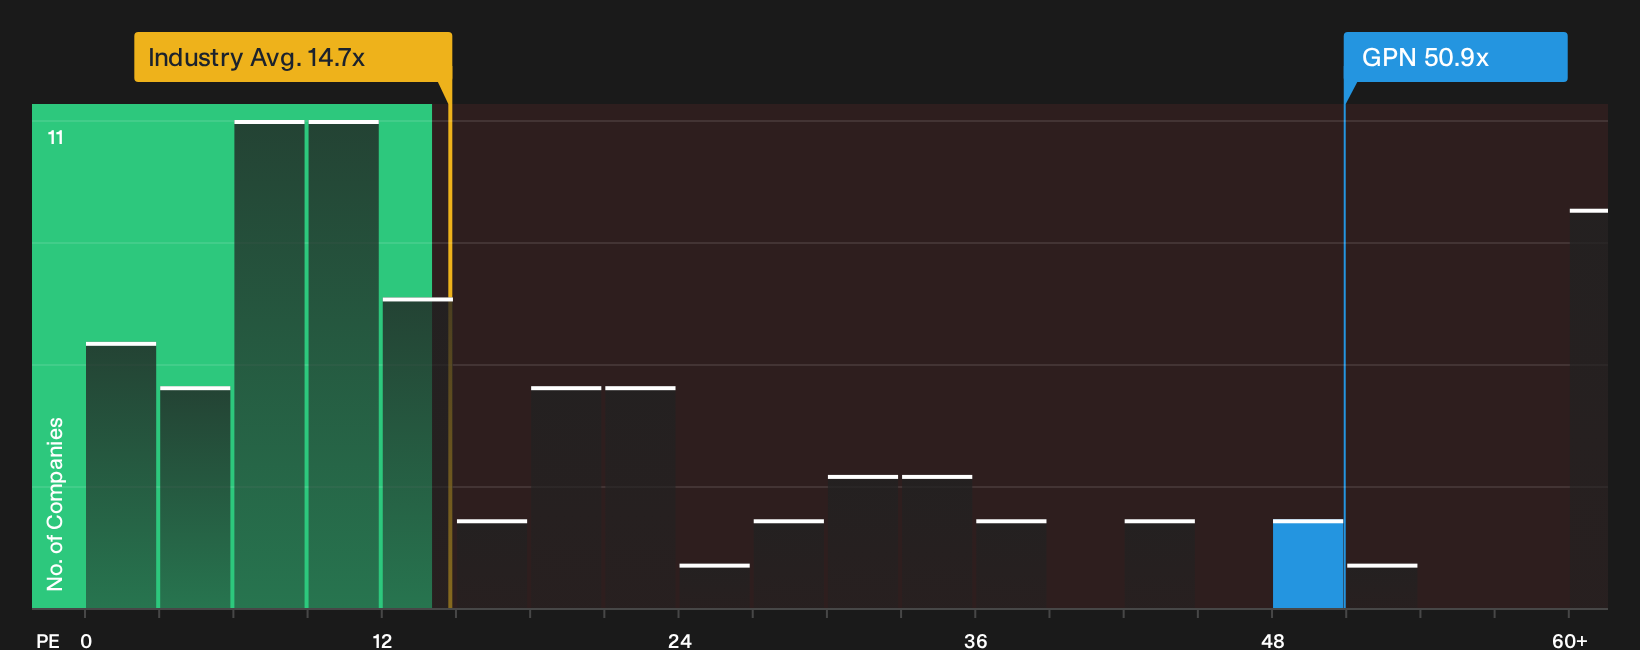
P/E works well for Global Payments because earnings remain the core focus for how investors frame a payments processor with meaningful scale. On this lens, the stock trades on a P/E of 50.9x, compared with about 14.7x for the wider diversified financial industry and roughly 44.2x across closer peers. That is a rich headline number, so context matters.
The fair value model that blends Global Payments' growth profile, margins, size and risk suggests a P/E only slightly above where the shares change hands today. As a result, the current rating screens about right on that tailored yardstick. Because the proposed US$40b buyout has sharpened attention on what the business can earn over the next few years, the present multiple effectively assumes that current profitability and Worldpay integration plans hold up without a major reset. Explore the numbers behind Global Payments's P/E valuation.
The Global Payments Narrative: What Would Justify Today's Price?
Narratives for Global Payments pick up where the valuation question leaves off and explain which paths for growth, profitability and earnings would need to occur for the stock to appear meaningfully mispriced in either direction. Each one treats Global Payments' implied fair value as a clear, trackable hypothesis about how the business might progress over time, and you can find them on Simply Wall St's Community page.
Community views on Global Payments are split between a cash rich transition story and a market already pricing in flawless execution.
Bull case: 11% undervalued
"Global Payments is currently executing a massive "pivot." They are moving away from being a general payment processor to becoming a pure-play Merchant Solutions provider..."
Discover why this Narrative puts Global Payments at 11% undervalued.
Bear case: 36% overvalued
"The numbers on growth guidance, margin expansion targets, capital return commitments, and leverage goals imply that Global Payments' share price already reflects successful execution on Worldpay integration..."
Explore why this Narrative puts Global Payments at 36% overvalued.
One big open question for Global Payments
Valuation only tells you what the market is willing to pay today, while the real swing factor for Global Payments is where professional forecasts think this business could be a few years from now. Explore where analysts expect Global Payments to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com