


EN
Payoneer Global (PAYO), What Is Behind The Fresh Attention?
Payoneer Global (PAYO) just released third quarter results that became the latest catalyst for the stock. Revenue reached US$276.94 million and net income came in at US$14.92 million, both below analyst expectations.
Despite the Q3 miss, Payoneer Global shares have quietly built momentum, with a year to date share price return of 31.8% and a 1 year total shareholder return of 36.1%, even though the 5 year total shareholder return remains down 16.8%.
Scan beyond Payoneer Global and explore other fintech and financial stocks that combine solid fundamentals with momentum in our curated 21 high quality undiscovered gems list.
After a post earnings rally built on modest beats and misses, the real tension for Payoneer Global is simple. Does the recent move justify buying now, or does patience for a cheaper entry still make more sense?
Most Popular Narrative: 3% Undervalued
Against a last close of $7.17, the most followed narrative pegs Payoneer Global's fair value at $7.40, which frames the recent rally as largely in line with underlying fundamentals rather than wildly detached from them.
Expansion of higher margin B2B payments and value added services into larger SMB and SME customers, backed by 44% year over year B2B volume growth in Q1 2026 and about one third of SMB volume now coming from B2B, supports further take rate uplift and revenue ex interest growth as Payoneer Global continues to shift its mix toward higher ARPU clients.
See why 20 investors see Payoneer Global as 3% undervalued.
Result: Fair Value of $7.40 (UNDERVALUED)
Still, the story around Payoneer Global can change fast if competition from larger payment platforms squeezes pricing, or if its stablecoin and trust bank plans fail to gain traction.
Find out about the key risks to this Payoneer Global narrative.
Another View: Payoneer Global Looks Expensive On Earnings
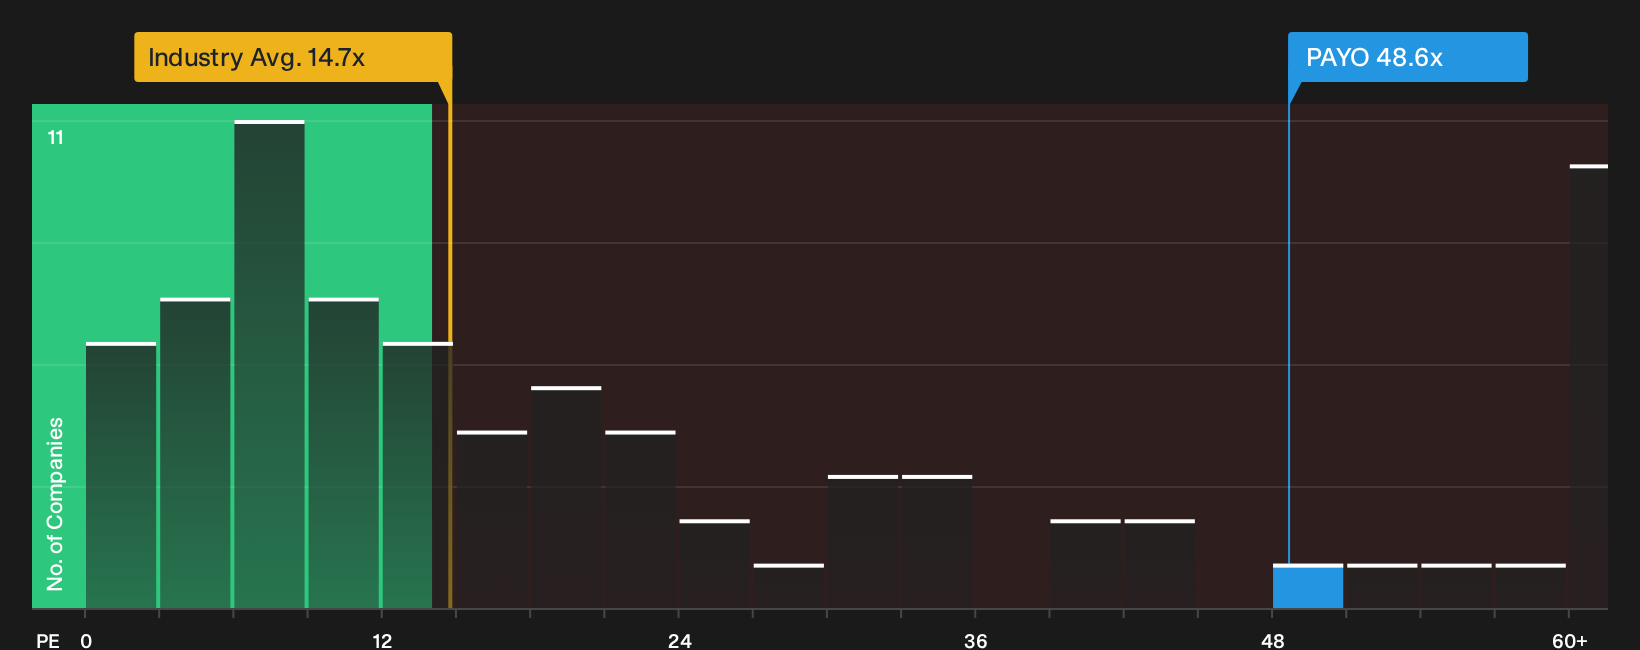
That 3% upside to Payoneer Global's $7.40 fair value sits awkwardly next to its current P/E of 48.6x, which is far richer than the US Diversified Financial industry at 14.7x and peer average of 17.3x, and even more stretched against a fair ratio of 21.9x. Does this valuation gap signal more downside risk than upside potential for late entrants?
For a clearer sense of how much conviction that rich P/E really demands from you, and how it compares across sectors and peers, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Payoneer Global's value and risk profile can cut both ways, so move quickly, review the full data, and weigh both the potential upsides and the issues flagged in 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Payoneer Global?
If Payoneer Global is on your radar, do not stop there. Broaden your opportunity set with a few targeted screens that surface different kinds of potential winners.
- Target quality at a discount by scanning 42 high quality undervalued stocks that pair stronger fundamentals with prices the market has not fully rewarded yet.
- Prioritise resilience and sleep better at night by filtering for 32 resilient stocks with low risk scores that score well on financial strength and volatility.
- Hunt for tomorrow's standouts early by reviewing a curated 9 elite penny stocks with strong financials before they land on everyone else's watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com