


EN
Why Everyone Is Watching Southwest Gas Holdings (SWX) Today
Southwest Gas Holdings (SWX) just released third quarter 2026 results, giving investors fresh numbers on sales, profit and earnings per share from its regulated natural gas operations across Arizona, Nevada and California.
The fresh earnings release lands after a bumpy few sessions for Southwest Gas Holdings, with the share price slipping around 2% over the past day and week. A roughly 9% one-month share price gain and about a 13% year-to-date share price return still point to improving momentum. Over a longer stretch, total shareholder return of about 18% over one year and more than 70% over three years suggests investors have been steadily rewarding the regulated utility story. Rate case outcomes, reaffirmed 2026 guidance and progress on the Great Basin 2028 expansion are reshaping expectations around both growth potential and future risk.
Compare Southwest Gas Holdings with other regulated utilities that have recently reported and are showing similar regulatory or earnings catalysts using our curated list of 32 resilient stocks with low risk scores.
Southwest Gas Holdings now trades around a 10% discount to analyst targets after its recent run. Is that gap a mispricing that reflects improving rate visibility, or is it a fair reflection of softer reported earnings and project execution risk ahead?
Most Popular Narrative: 10% Undervalued
On the most followed narrative, Southwest Gas Holdings screens about 10% below an estimated fair value of $100.63, compared with the latest close at $90.49. That gap rests on a view that rate cases, capital spending and balance sheet strength can support higher earnings than current results alone might suggest.
Accelerated infrastructure investment opportunities are now anchored by a larger US$2.3b capital plan for the Great Basin 2028 Expansion Project and a broader US$6.3b 5 year utility capital program. These are expected to expand regulated rate base and in turn support higher future regulated revenue and earnings.
See why 4 investors see Southwest Gas Holdings as 10% undervalued.
Result: Fair Value of $100.63 (UNDERVALUED)
Still, the bullish case for Southwest Gas Holdings depends heavily on constructive regulators and clean execution on the US$2.3b Great Basin 2028 expansion project.
Find out about the key risks to this Southwest Gas Holdings narrative.
Another View: What Multiples Say About Southwest Gas Holdings
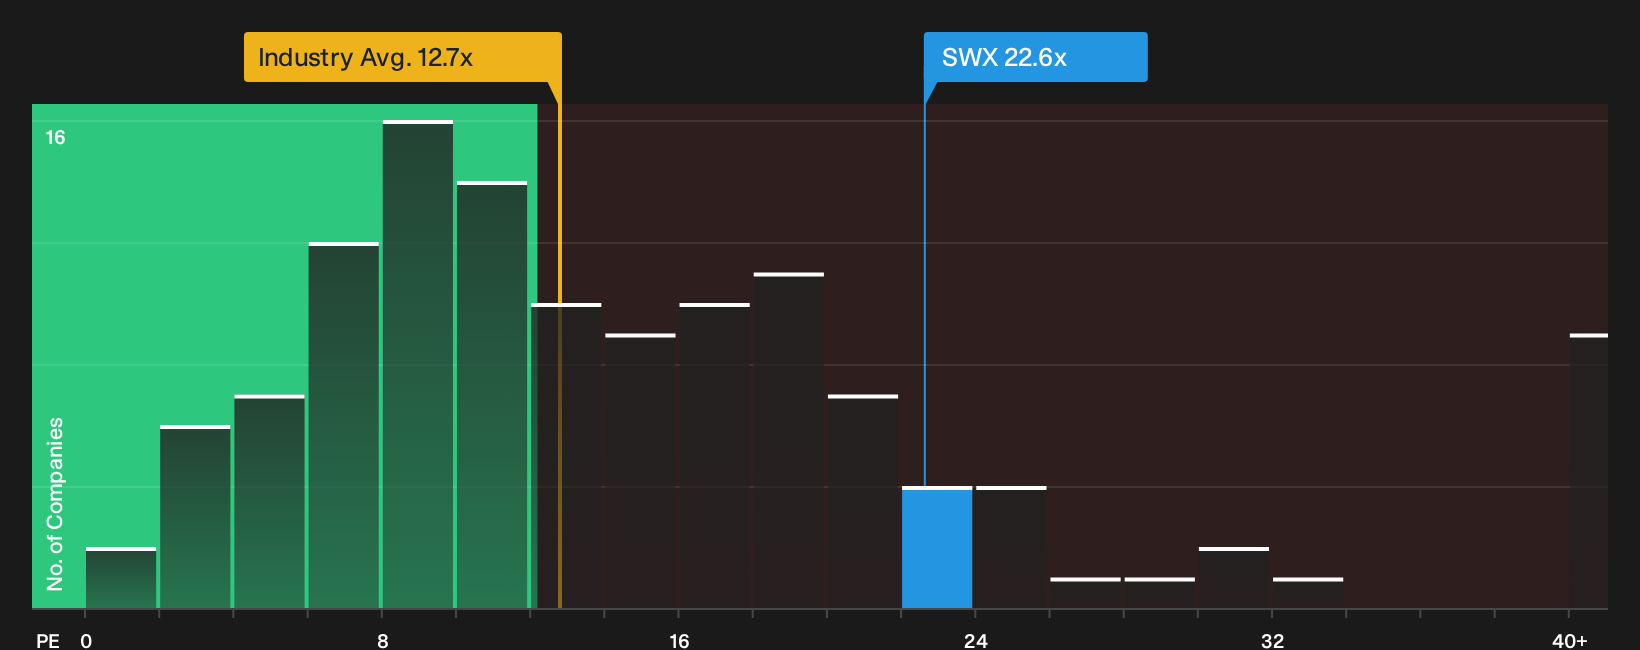
The first narrative leans on an estimated fair value of $100.63, yet the current market is charging a rich price for Southwest Gas Holdings when earnings are used as the yardstick. The stock trades on a P/E of 22.6x compared with 12.7x for the global gas utilities group and 15.5x across peers, while the fair ratio sits lower again at 21.1x. That kind of gap points to less room for error if earnings or regulation disappoint, so the real question is whether you think the story justifies paying well above the going rate for the sector.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can be useful, especially when Southwest Gas Holdings shows both flagged risks and clear potential rewards that investors are debating. Act quickly and stress test the bullish and cautious narratives for yourself by reviewing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Southwest Gas Holdings?
You have fresh context on Southwest Gas Holdings. Now widen the lens and pressure test your thesis against other opportunities using the Simply Wall Street Screener before capital moves elsewhere.
- Target resilient balance sheets by sorting through a curated list of solid balance sheet and fundamentals (25 results) that highlights businesses with financial strength at the core of their story.
- Hunt for potential mispricings by scanning a focused pool of 42 high quality undervalued stocks where quality and valuation filters work together for you.
- Prioritise steady cash returns by screening for 6 dividend fortresses that may offer higher yields without ignoring underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com