


EN
Ecovyst (ECVT) Could Be 33% Undervalued On Raised Guidance And Buybacks
Ecovyst (ECVT) just posted third quarter 2026 results that turned last year’s loss into a profit, increased sales, and led to higher adjusted EBITDA guidance along with a larger share repurchase plan.
Ecovyst’s share price is at US$10.18 after a 1-day share price return of 2.11%. The 30-day and 90-day share price returns are slightly down, while the 1-year total shareholder return of 21.92% points to stronger longer term momentum supported by today’s earnings and buyback update.
Scan beyond Ecovyst and explore other materials and industrials stocks that exhibit resilient demand and strong profitability profiles using our hand picked list of solid balance sheet and fundamentals (25 results).
Ecovyst now has fresh earnings, a higher profit baseline, and an active buyback in motion. The key question is whether to treat today’s move as an entry point or wait for calmer pricing during the valuation work ahead.
Most Popular Narrative: 33% Undervalued
The most followed Ecovyst narrative sees fair value at $15.17 per share compared with the latest close at $10.18. This puts the emphasis firmly on how the sulfur platform and recent deals could shift earnings and cash flow over time.
The ongoing build out of Ecovyst's integrated sulfur solutions platform, with the completed acquisitions of Chem32, Waggaman and Calabrian and the prior divestiture of Advanced Materials & Catalysts, is creating a more focused network that can serve shared customers and is expected to support future revenue and adjusted EBITDA growth.
The recent Calabrian acquisition at roughly 8x trailing 12 month adjusted EBITDA of US$24 million, with US$3 million to US$4 million of expected cost and revenue synergies over about three years and a profile described as higher margin and less capital intensive than Ecovyst's legacy business, creates scope for mix improvement in future net margins and adjusted EBITDA.
See why 3 investors see Ecovyst as 33% undervalued.
Result: Fair Value of $15.17 (UNDERVALUED)
Still, the Ecovyst narrative can change quickly if higher sulfur costs inflate sales but leave profit roughly flat, or if larger capex and the CFO transition disrupt cash generation.
Find out about the key risks to this Ecovyst narrative.
Another Take On Ecovyst’s Valuation
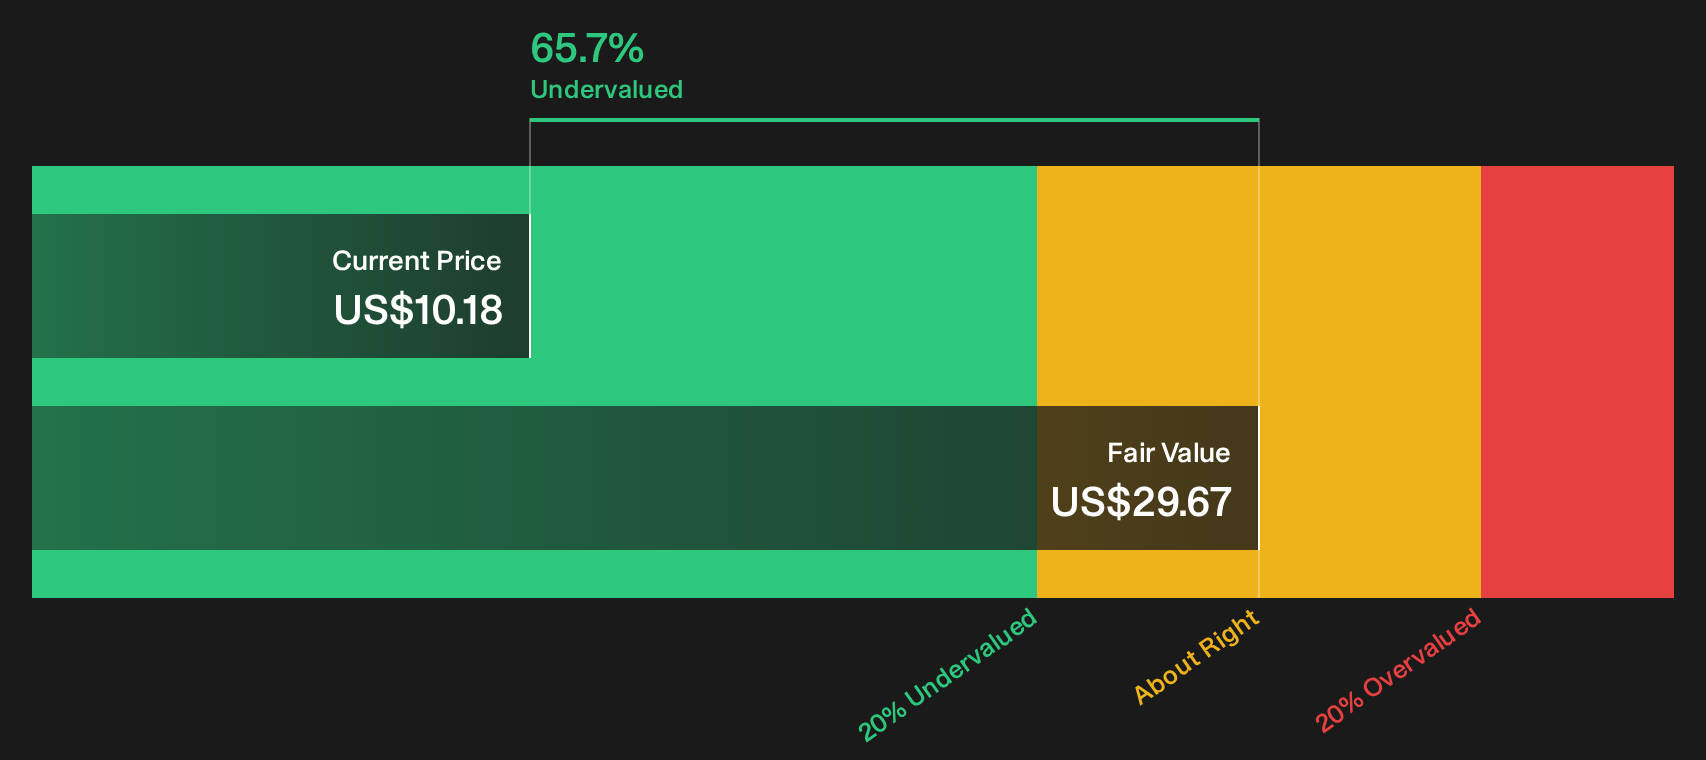
The bullish narrative leans heavily on Ecovyst’s analyst fair value of $15.17 per share, yet the SWS DCF model paints an even richer picture. In that framework, the stock screens as undervalued against an estimated future cash flow value of $29.67. Which lens do you trust more when cash flow and earnings point to different upside?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or clear message? Ecovyst now has fresh numbers and an active buyback, so move quickly, work through the data, and weigh the 3 key rewards and 3 important warning signs.
Looking For More Ecovyst-Like Investment Ideas?
If Ecovyst has your attention after these results, do not stop here. Broaden your watchlist with other opportunities that match different risk and return profiles.
- Target potential mispricings by scanning for quality companies trading below estimated worth through the 42 high quality undervalued stocks.
- Secure steadier income streams by focusing on businesses with robust payouts using the 6 dividend fortresses.
- Prioritize capital protection by filtering for financially resilient opportunities through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com