


EN
Arrowhead Pharmaceuticals (ARWR) Could Be 48% Undervalued Following Its $400 Million Refinancing
Arrowhead Pharmaceuticals (ARWR) has just overhauled its debt with a new US$400 million term loan from Sixth Street, cutting borrowing costs and pushing maturities out to 2031 to create more financial breathing room.
Arrowhead Pharmaceuticals has had a volatile run, with the share price down 34.47% over the past 90 days and 15.27% year to date. Long-term holders have seen a 45.05% 1-year total shareholder return and 114.81% over three years, suggesting recent refinancing and product progress are being weighed against earlier optimism as momentum cools from prior gains.
Scan beyond Arrowhead Pharmaceuticals and see how other biotechs are repositioning after major financing moves with our hand-picked 21 high quality undiscovered gems list.
Arrowhead Pharmaceuticals now has cheaper debt and more time on the clock, while the share price has cooled from big multi year gains. Does that reset leave the current valuation skewed toward upside or downside for new buyers?
Most Popular Narrative: 48% Undervalued
Against a last close of $57.44, the most followed narrative puts Arrowhead Pharmaceuticals closer to a fair value of about $110, which frames today’s pullback against much richer future assumptions built using a 7.6% discount rate.
Arrowhead's advancing late-stage clinical pipeline, especially the expected launch of plozasiran for FCS and SHTG, plus pivotal studies for three other RNAi therapies targeting major unmet needs, positions the company to capitalize on rising demand for innovative treatments driven by an aging population and increasing prevalence of chronic and genetic diseases, which could significantly accelerate revenue growth as approvals and launches materialize.
See why 15 investors see Arrowhead Pharmaceuticals as 48% undervalued.
Result: Fair Value of $110.18 (UNDERVALUED)
Still, the bullish Arrowhead Pharmaceuticals story leans heavily on plozasiran execution and partner funding, so any trial setback or collaboration wobble could quickly test that thesis.
Find out about the key risks to this Arrowhead Pharmaceuticals narrative.
Another View: What Arrowhead Pharmaceuticals’ P/S Ratio Is Telling You
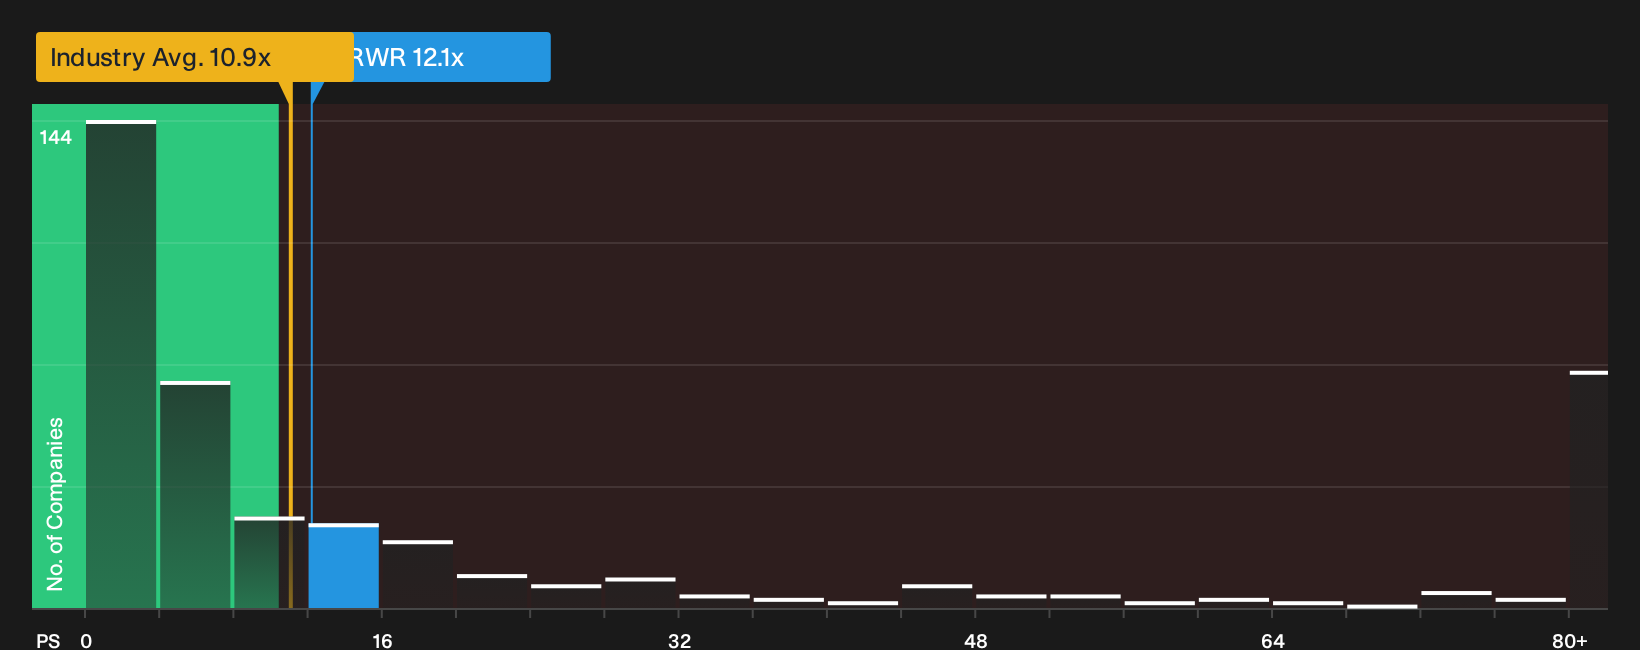
Analysts using future cash flows see Arrowhead Pharmaceuticals as deeply undervalued, yet today the stock trades on a P/S ratio of 12.1x versus 10.9x for the wider US biotech group and a 13x peer average, while the fair ratio sits higher at 15.7x. Does that mix of relative expensiveness against the sector but a discount to the fair ratio signal extra risk or leave room for the share price to catch up?
To see how this pricing gap could close in either direction based on the numbers alone, take a closer look at the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
The current P/S snapshot only shows part of the picture, so it helps to view Arrowhead Pharmaceuticals beside the rest of the market using the side by side valuation chart in
Next Steps
Mixed signals on Arrowhead Pharmaceuticals can feel confusing, so move fast, pull up the full dataset, and weigh both sides of the story using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Arrowhead Pharmaceuticals?
If you stop with Arrowhead Pharmaceuticals, you only see one angle. Broaden your watchlist now and potentially increase your chances of spotting opportunities early.
- Explore resilient potential by reviewing companies that score well on financial strength through the list of solid balance sheet and fundamentals (25 results).
- Search for quality at a discount by scanning companies flagged as attractively priced using the 42 high quality undervalued stocks.
- Balance income and stability by checking income focused opportunities with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com