


EN
Can Rapid7 (RPD) Justify Its Price As Earnings Beat Expectations?
Why Rapid7’s latest earnings moved the stock
Rapid7 (RPD) shook investor expectations after its third quarter update, topping revenue forecasts, lifting full year adjusted EPS guidance, and triggering a sharp 17% share price jump on the announcement.
The immediate reaction to Rapid7’s earnings sits within a choppy year. The share price has risen 25.84% over the past month and 33.45% across 90 days, yet the 1-year total shareholder return is only 7.22% and the 3-year total shareholder return has fallen 69.24%. As a result, the recent momentum reflects a shift in sentiment more than a long track record of gains.
Scan how Rapid7 compares with other security and infrastructure players by reviewing our curated list of 53 AI infrastructure stocks after moves like this earnings reaction.
Rapid7 now trades well above the average analyst target, yet its intrinsic value estimate still points to a sizeable gap in the other direction. Which reference point does the current jump lean closer to?
Most Popular Narrative: 29% Overvalued
Rapid7 closed at $15.44, while the most followed narrative places fair value around $11.98. The post earnings surge therefore sits well ahead of that long term estimate, which is built on an 11.08% discount rate.
The current valuation implies that Rapid7 will justify a premium multiple, even though ARR and 2026 revenue guidance point to a contracting top line. This is why this narrative holds that the stock is overvalued and leans bearish.
See why 15 investors see Rapid7 as 29% overvalued.
Result: Fair Value of $11.98 (OVERVALUED)
Still, if Rapid7 delivers on its planned margin lift and AI driven MDR gains traction, that could challenge the bearish view that is baked into this narrative.
Find out about the key risks to this Rapid7 narrative.
Another View: Rapid7’s cash flow valuation flips the story
The first narrative pins Rapid7 as about 29% overvalued relative to a long term fair value of $11.98. A different lens says something else. Our DCF model points to future cash flows worth about $30.24 per share, implying the current $15.44 price sits well below that estimate.
This gap between cautious earnings based targets and a far higher cash flow value raises a simple question: Which do you trust more, analyst multiples or the long run cash generation that the SWS DCF model is pricing in?
Look into how the SWS DCF model arrives at its fair value.
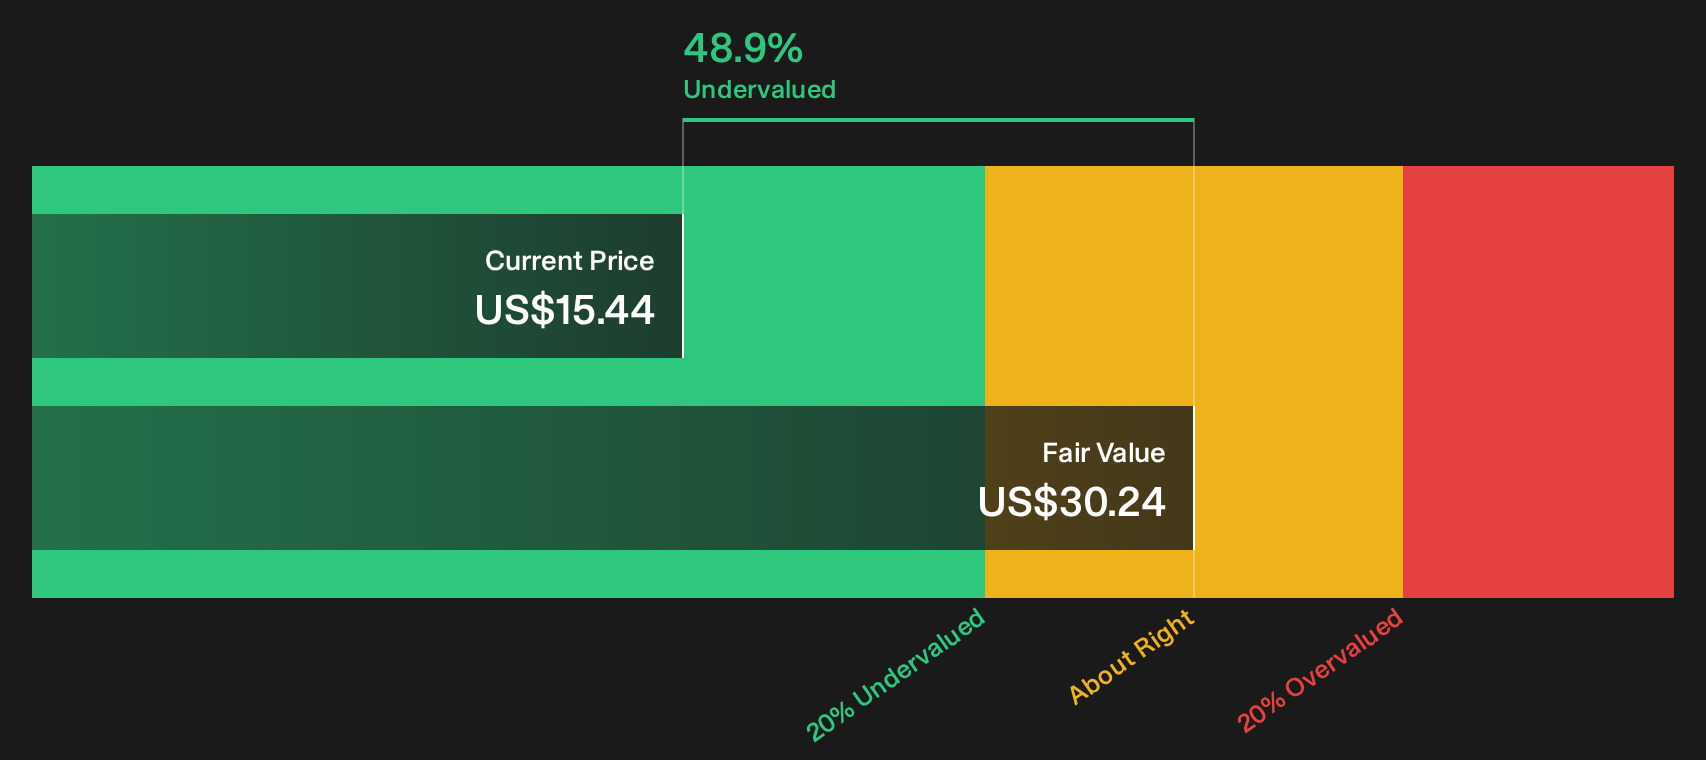
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rapid7 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the Rapid7 story feels split between risk and potential, that is the point. This is the moment to interrogate the data yourself and move quickly. To see both sides laid out clearly, go through the 2 key rewards and 4 important warning signs.
Looking for more Rapid7-like investment ideas?
Do not stop your research with Rapid7. Use the Simply Wall Street Screener to surface fresh opportunities that fit your style before the crowd leans in.
- Target potential bargains by focusing on proven quality with pricing that still looks reasonable through our 42 high quality undervalued stocks.
- Protect your downside by filtering for companies that pair dependable finances with modest risk profiles using the 32 resilient stocks with low risk scores.
- Spot underfollowed opportunities by scanning for strong fundamentals in lesser known stocks through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com