


EN
3 Undervalued Stocks Trading Up To 38% Below Fair Value
Higher interest rates from central banks like the Bank of England have made borrowing more expensive and put pressure on weaker balance sheets. That kind of backdrop tends to reward businesses that generate solid cash today rather than relying on distant hopes tomorrow. Cash rich companies that trade below what detailed cash flow models suggest they could be worth can attract patient buyers. This article highlights three such undervalued cash flow opportunities.
The three stocks below are just a sample of the opportunities that fit this cash flow focused idea. The full screen surfaced another 106 companies with similarly compelling stories that are not covered here.
If you want to quickly identify and analyze the highest conviction cash flow ideas, head straight to the Undervalued Stocks Based On Cash Flows screener.
Cisco Systems (CSCO)
Overview: Cisco Systems builds networking hardware, security tools, and subscription software such as SASE, Webex, and observability platforms that support recurring cash flows.
Operations: Cisco generates US$63.3b in revenue from computer networks, with US$34.4b from the United States and the rest split across APJC, EMEA, and other Americas.
Market Cap: US$407.9b
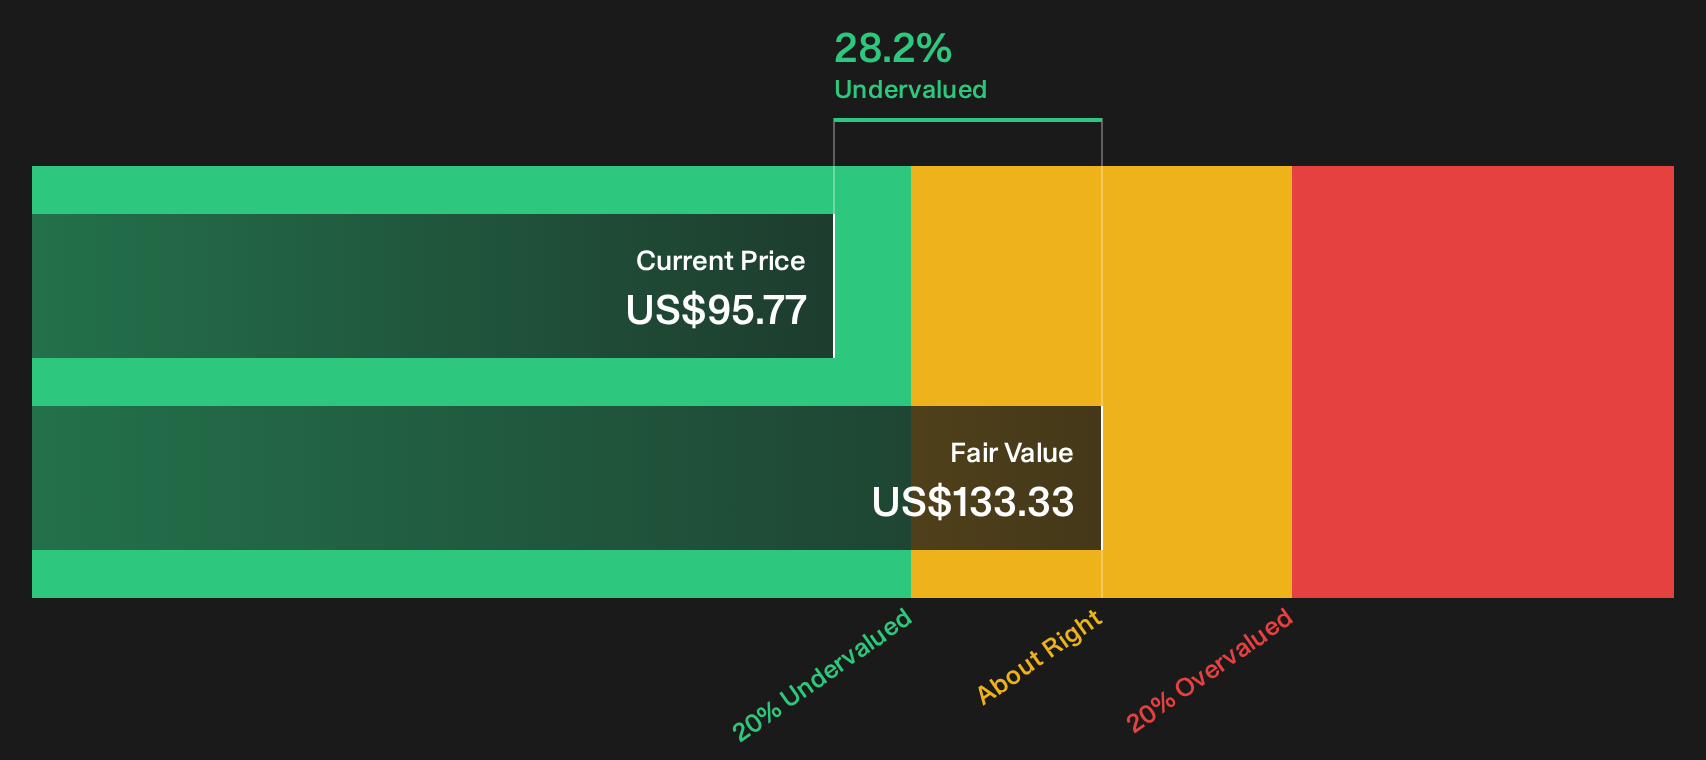
Cisco Systems fits this cash flow focused screen because a growing slice of its business is tied to software subscriptions and services that renew year after year, which helps support a discounted cash flow view of value that is rooted in recurring income rather than one off hardware cycles.
"The rollout transitions Cisco from experimental pilot programs to standardized, autonomous agentic workflows across sales, engineering, finance, legal, and customer support."
The real test for Cisco’s cash generation story now hinges on how one unseen pressure shapes the balance between AI spend and profitability.
That pressure point is exactly where the story gets interesting for long term holders, and the full narrative for Cisco Systems lays out how AI spend, cash strength, and valuation could be decoupling.
Lockheed Martin (LMT)
Overview: Lockheed Martin builds fighter jets, missiles, helicopters and space systems for the U.S. and allied governments under long-term defense contracts.
Operations: Lockheed Martin generates US$32.2b from Aeronautics and US$13.9b from Space, with US$54.9b of its sales coming from the United States.
Market Cap: US$137.5b
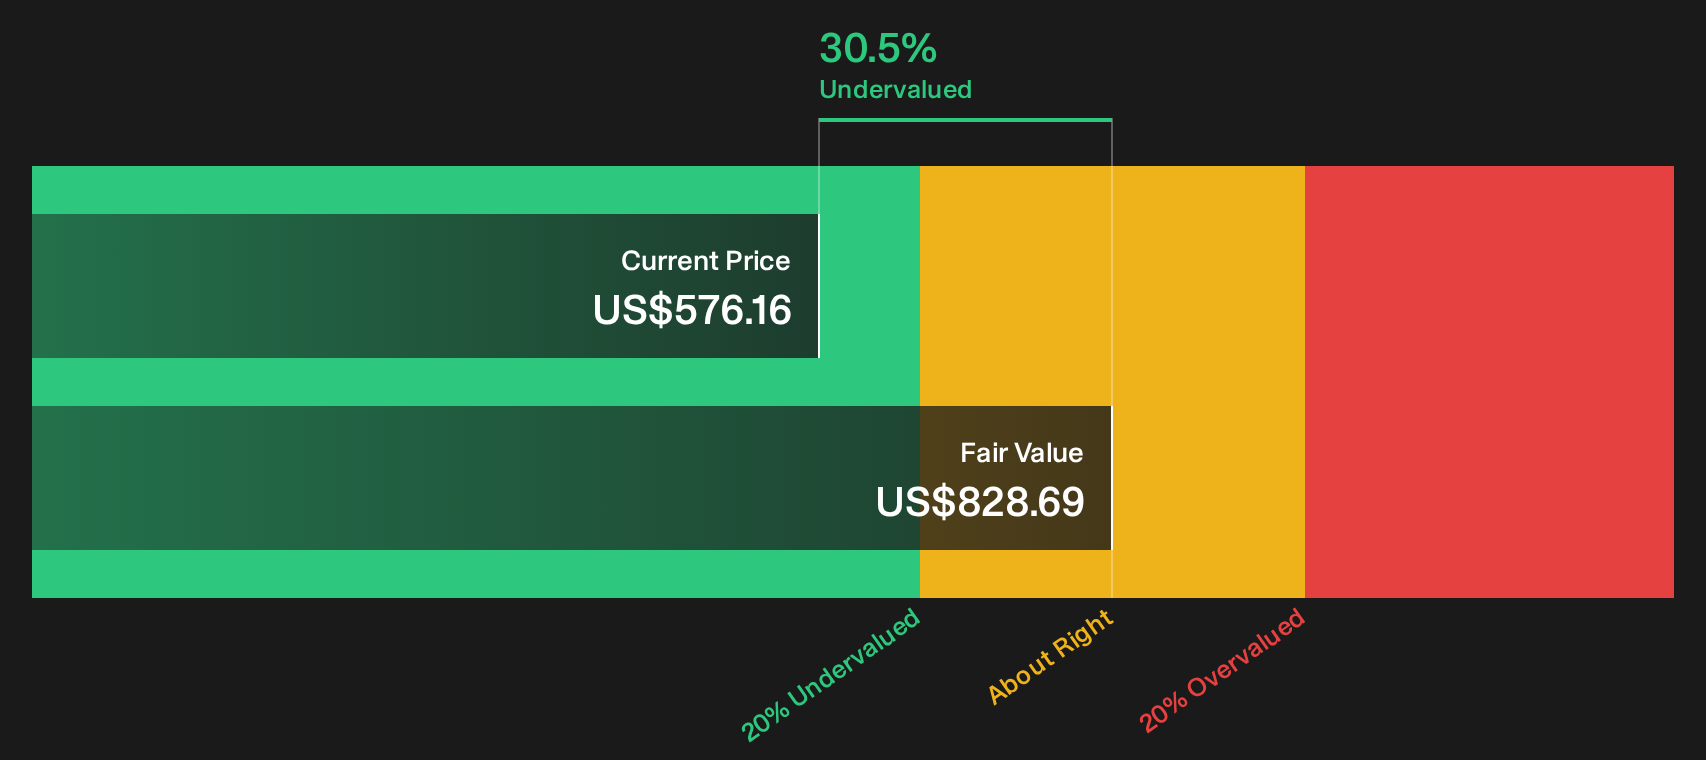
Lockheed Martin matters for this cash flow screen because its long-running defense programs can convert years of contracted work into steady free cash.
"Lockheed Martin is moving munitions like PAC‑3, THAAD, PrSM and JATM onto seven year framework agreements that aim to triple or quadruple production and allow the company to retain a larger share of cost savings from capacity investments such as robotics in Camden, which can support higher future revenue and structurally stronger net margins."
What happens to those projected margins depends heavily on how one unresolved cost sharing balance between customers and suppliers ultimately settles.
That unresolved balance is exactly where the full narrative for Lockheed Martin shows how accelerating demand, cash returns, and contract risks could all be pulling in different directions.
Oracle (ORCL)
Overview: Oracle runs global cloud software, databases, and infrastructure that help organisations manage data, applications, and AI driven workloads.
Operations: Oracle generates about US$62.8b from cloud and software, US$5.8b from services, and US$3.2b from hardware.
Market Cap: US$385.8b
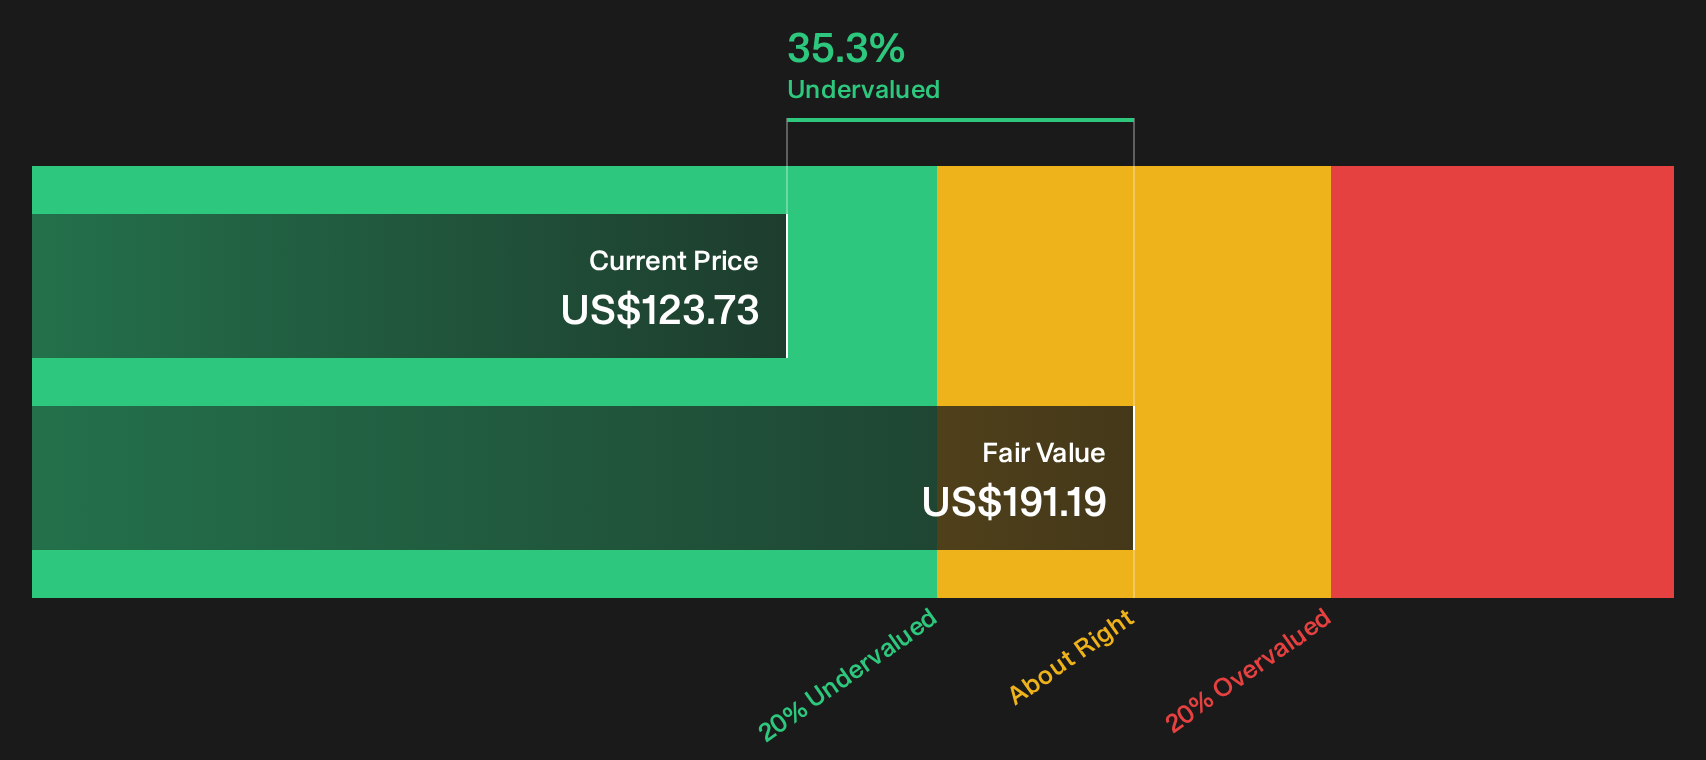
Oracle matters for this cash flow focused screen because its cloud subscriptions and infrastructure contracts can turn long software relationships into recurring cash flows that are central to a discounted cash flow view of value.
"Oracle’s Gen2 AI infrastructure was validated when OpenAI began leveraging OCI Superclusters, capable of scaling up to 32,768 Nvidia GPUs per cluster, positioning OCI as a key extension of the Microsoft Azure AI platform."
What those recurring AI and cloud commitments mean for Oracle’s future cash generation now hinges on how one funding and execution trade off plays out.
That trade off sits at the heart of the full narrative for Oracle, which maps how Oracle’s AI ambitions, cash engine, and valuation could be quietly accelerating.
Seeking Alternatives Before Others Catch On
Fresh ideas move first. Once momentum hits and watchlists fill up, the best entry points can be gone. Scan these under the radar lists now and review them before they become widely followed.
- Target resilient cash generators before the crowd by running the 42 high quality undervalued stocks while valuations, balance sheets, and cash flows still align with your criteria.
- Spot early AI candidates with existing earnings support by checking the curated set of 40 profitable AI stocks that aren't just burning cash before additional trading activity changes the price dynamics.
- Review potential long term income opportunities by using the hand picked 6 dividend fortresses while yields remain at current levels and focus is limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com