


EN
What Sociedad Química y Minera De Chile Stock's Blowout Quarter Means For Shareholders
- Sociedad Química y Minera de Chile reported quarterly revenue growth of 136.7% and very large earnings per share growth of about 7x, alongside a 4.44% dividend yield and net debt at 0.7 times EBITDA.
- The combination of rapid earnings expansion, ongoing dividend income of US$2.43 per share annually and modest leverage indicates a business currently balancing growth investment with a disciplined capital structure.
- We will now look at how Sociedad Química y Minera de Chile's sharp quarterly earnings surge could reshape the broader investment narrative.
Scan beyond Sociedad Química y Minera de Chile and line up other growth plus income opportunities with 42 high quality undervalued stocks that pair expanding earnings profiles with meaningful dividends.
Sociedad Química y Minera de Chile Investment Narrative Recap
To back Sociedad Química y Minera de Chile, you need to believe its lithium and specialty chemicals operations can turn strong recent execution into something durable, even as markets move around. The latest quarter, with revenue up 136.7% and earnings per share roughly 7x higher year on year, points to robust underlying demand and cost discipline, but also raises the bar for what counts as progress from here.
The key short term swing factor remains lithium pricing versus the firm’s planned capacity ramp in Chile and Australia. A very strong quarter does not remove the risk of a future market surplus or rising state payments in Chile, which could pressure margins just as multibillion dollar projects like Mt Holland and Salar Futuro absorb heavy cash outlays.
The most relevant context for this earnings surge is the multi year capital spending plan across Novandino Lithium, Mt Holland and Salar Futuro, with roughly US$3b earmarked for 2026 to 2028 and another US$3b planned for Salar Futuro. These commitments frame how investors might read the current 20.6% net margin and 0.7 times EBITDA leverage, since they signal management is preparing for higher volumes rather than a static portfolio.
For you as a shareholder, the question is whether Sociedad Química y Minera de Chile can turn today’s strong quarterly earnings into solid returns on that heavy project pipeline in a market where lithium demand and pricing may not always align with capacity additions. Execution on volume growth in lithium, iodine and specialty plant nutrition, while keeping net margins resilient under higher Chilean payments, will likely determine how this quarter is remembered in hindsight.
Sociedad Química y Minera de Chile's narrative projects US$8.7b revenue and US$2.3b earnings by 2029. This lines up with analyst assumptions of 8.8% yearly revenue growth and an earnings increase of about US$0.9b from the current US$1.4b level.
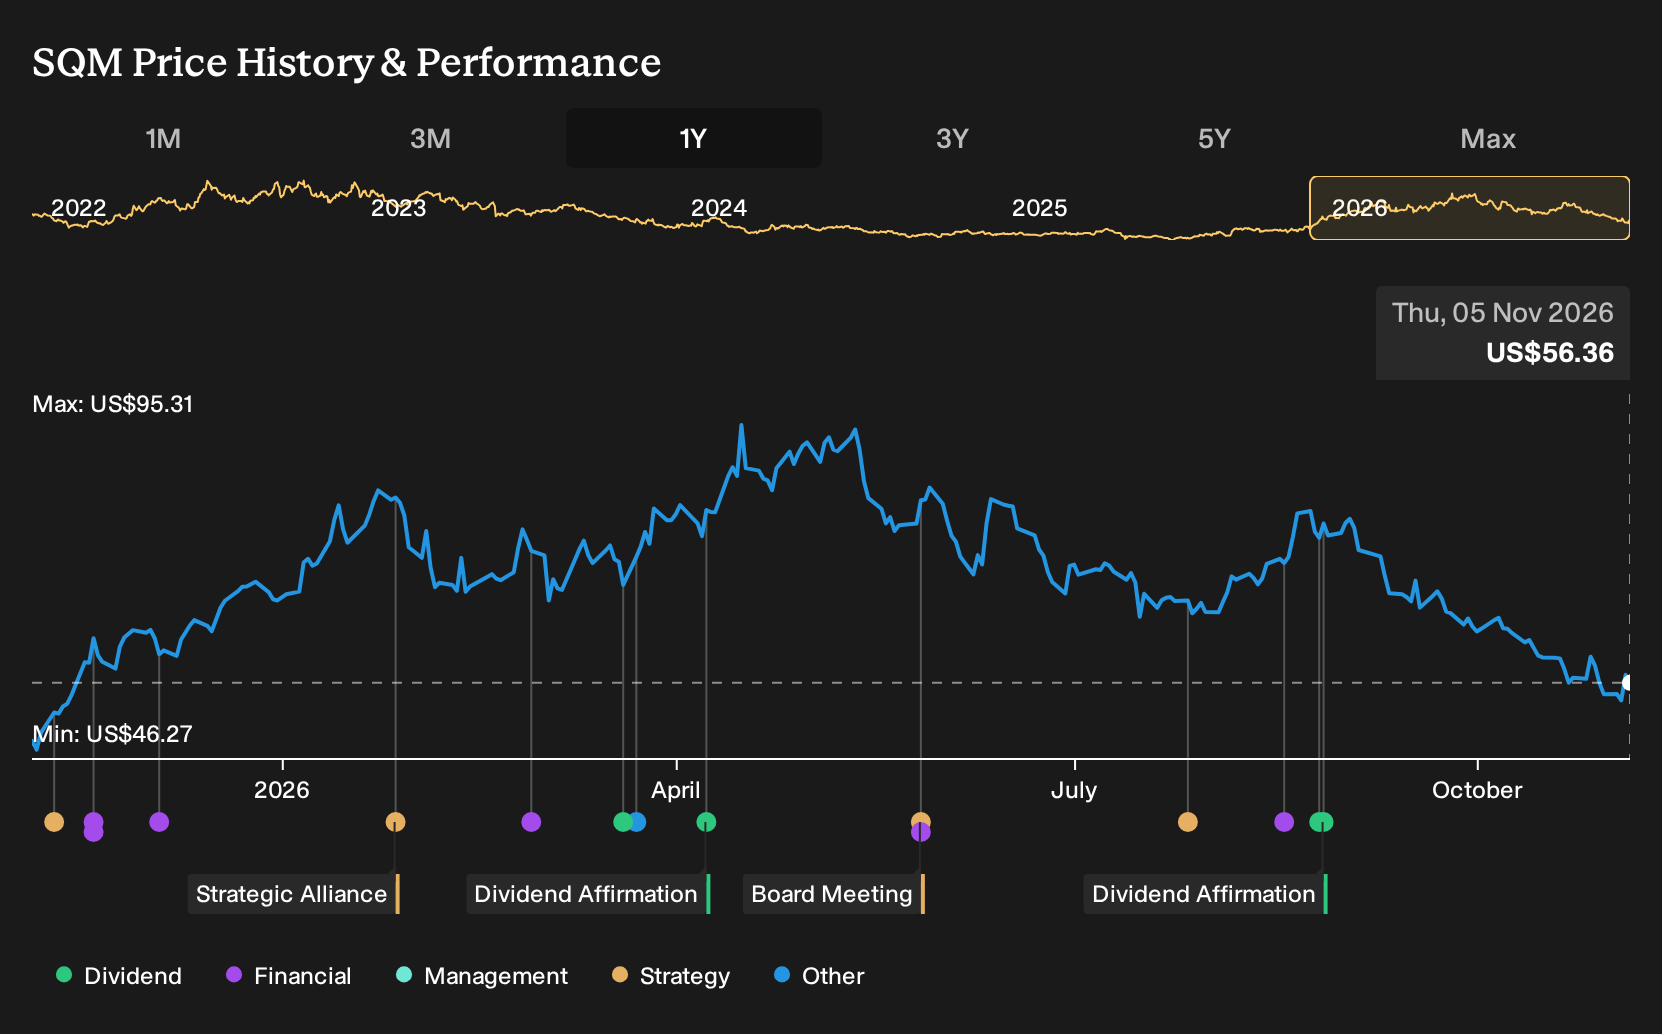
Uncover why Sociedad Química y Minera de Chile's fair value indicates a 47% potential upside to its current price before that discount begins to close.
Exploring Other Perspectives
One alternate view on Sociedad Química y Minera de Chile leans hard on lithium price risk. The most bearish analysts were modelling revenue at about US$5.7b and earnings near US$1.2b by 2029 before this latest quarterly jolt. That is a much more cautious story, so it is worth exploring several competing forecasts before deciding what this new data could change.
Explore 4 other Sociedad Química y Minera de Chile fair value estimates, including one that suggests it could be worth just $81.61.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Sociedad Química y Minera de Chile research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sociedad Química y Minera de Chile. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sociedad Química y Minera de Chile's overall financial health at a glance.
Looking for more investment ideas beyond Sociedad Química y Minera de Chile?
If Sociedad Química y Minera de Chile has sharpened your focus on where earnings power and balance sheet strength intersect, it can be useful to line up a wider watchlist that targets similar traits in other businesses.
- For investors who care most about resilient financial footing, consider stocks filtered through a list of solid balance sheet and fundamentals (25 results) that can help you focus on companies with the capacity to handle shocks without stressing their funding.
- If income is a priority for you, scan for reliable cash return stories by reviewing a 6 dividend fortresses that highlights businesses combining higher yields with ongoing payouts.
- To widen your opportunity set beyond well followed stocks, use a 21 high quality undiscovered gems that surfaces under the radar companies with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com