


EN
Earnings Jump Could Change The Case For National Presto Industries Stock
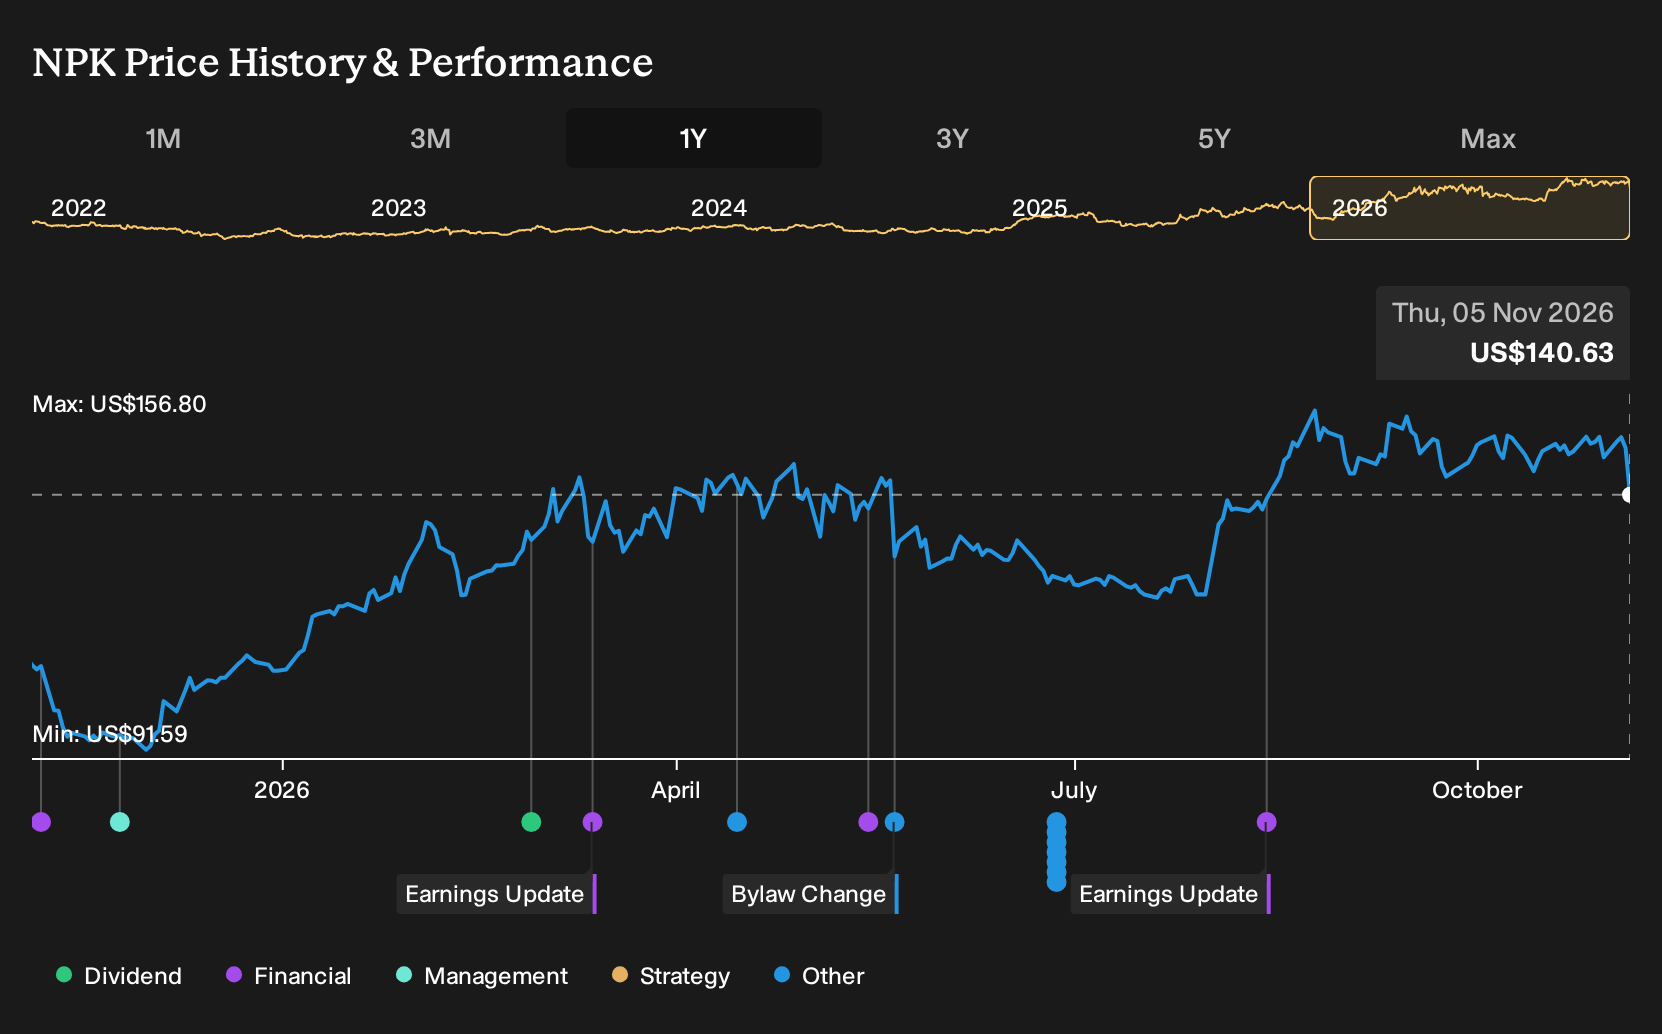
- National Presto Industries reported quarterly revenue growth of 21.7% and earnings per share that were more than triple the prior year, supported by a low net debt to EBITDA ratio of 0.5 that points to conservative use of leverage.
- The combination of rapid earnings expansion and a relatively clean balance sheet suggests National Presto Industries is funding growth from a position of financial strength rather than heavy borrowing.
- This analysis will examine how National Presto Industries' sharp earnings jump reframes the investment narrative and what that may indicate for long term expectations.
Scan beyond National Presto Industries and compare its sharp earnings jump with other financially resilient stocks using our curated 32 resilient stocks with low risk scores list.
What Is National Presto Industries' Investment Narrative?
To back National Presto Industries as a shareholder, you need to believe this mix of defense, housewares, and safety products can keep converting a long corporate history into consistent cash generation. The latest quarter, with 21.7% revenue growth and earnings per share more than triple the prior year, sits on top of a business that already reports high quality earnings and a low net debt to EBITDA ratio of 0.5. That combination suggests operations are not being strained by heavy borrowing, which can matter when capital needs rise in defense or manufacturing cycles.
The short term story now revolves around execution. The recent earnings jump puts a spotlight on whether current demand and pricing in the defense segment, which generates most of National Presto Industries revenue, can be sustained without eroding margins that were lower than last year. Forecast earnings growth of 8.9% a year and revenue growth of 6.1% a year point to a steadier, less explosive path compared with the latest quarter, so the key question is how management allocates cash between reinvestment, balance sheet conservatism, and shareholder returns in a business that can be capital intensive when contracts ramp.
Even so, the picture becomes more complicated once you look closely at one structural weak spot that has not gone away.
There's only one way to know the right time to buy, sell or hold National Presto Industries. Head to Simply Wall St's company report for the latest analysis of National Presto Industries's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between US$157.20 and US$162, which shows how differently retail investors can judge National Presto Industries even when using similar models. These views were set before the latest 21.7% revenue jump, so it is worth revisiting several community perspectives with that fresh information in mind.
Explore another National Presto Industries fair value estimate, including one that suggests it could be worth just $157.20.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your National Presto Industries research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for National Presto Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Presto Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond National Presto Industries?
Once you have formed a view on National Presto Industries, it can help to benchmark that thesis against other companies with different risk and income profiles. The Simply Wall St Screener is a quick way to line up fresh ideas against your own checklist so you can see where this stock really fits in your broader plan.
- If you want potential value combined with quality fundamentals, review a curated set of 42 high quality undervalued stocks that might deserve a place on your radar.
- If resilience and balance sheet strength matter most to you, focus on the list of solid balance sheet and fundamentals (25 results) to see which businesses keep financial risk in check.
- If income is a priority, scan through the 6 dividend fortresses and compare those yield opportunities with what National Presto Industries currently offers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com