


EN
Ulta Beauty (ULTA) Stock Looks Expensive On Current Earnings
Ulta Beauty has delivered strong multi year gains for shareholders, which puts a spotlight on whether the current US$649.45 share price still lines up with what its earnings can support. With the stock now reflecting years of optimism and execution, the key issue for you is how much profit power the business is actually being priced for today.
- The stock has returned 67.0% over the past 3 years, which puts real weight on the question of how much earnings strength is already reflected in the valuation.
- New partnerships, including moves into wellness wearables and broader product distribution through retailers such as WHOOP and K beauty brands, may support expectations for future profit growth and cash generation that investors are now weighing against current earnings.
- Your read on Ulta Beauty is one view; the desks covering it have another. See what analysts think Ulta Beauty's shares could be worth.
The stock's next move may depend on whether Ulta Beauty's current price can be fully explained by the earnings power that the business is generating today.
If you want a cleaner read on how Ulta Beauty's earnings-based price tag compares with other opportunities tied to profit power, line it up against companies in the 42 high quality undervalued stocks
Is Ulta Beauty Getting Expensive on Earnings?
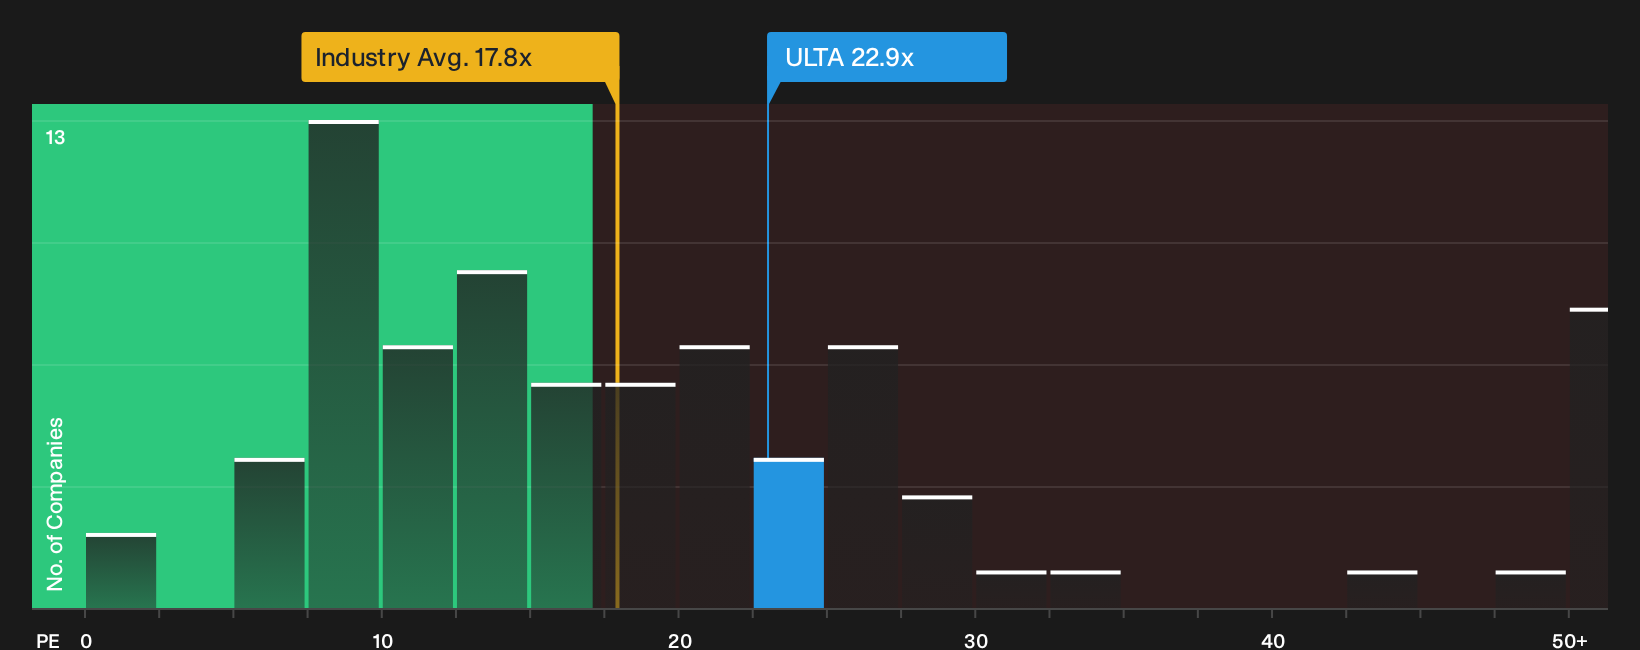
The P/E ratio suits Ulta Beauty because earnings remain a central anchor for how investors weigh the business. At a P/E of 22.9x, the stock trades slightly above both the specialty retail average of 17.8x and the peer group on roughly 22.4x. That gap tells you the market is willing to pay a higher price for each dollar of Ulta Beauty profit than for much of the sector.
The fair multiple implied by the model, which blends factors like profitability, growth expectations, size and sector risk, sits below where the shares change hands today, so on this framework the stock screens as overvalued. Because the WHOOP and broader wellness partnerships have raised the profile of Ulta Beauty and widened its reach, the current premium reflects a meaningful amount of confidence that these newer profit streams will justify the higher P/E. If you hold the view that the current earnings base already carries a full price tag, this valuation starting point becomes an important piece of your risk and return trade off to weigh. Explore the numbers behind Ulta Beauty's P/E valuation.
The Ulta Beauty Narrative: What Would Justify Today's Price?
Ulta Beauty's current valuation raises a clear question. What would need to happen to its growth, margins and earnings over time for today's price to look cheap or stretched on an earnings basis? Simply Wall St Narratives pick up that thread on the Community page, turning each scenario into a thesis about Ulta Beauty's fair value that you can revisit later to see how well it lines up with how the business actually develops.
Ulta Beauty fans in the community mostly agree on the engines that matter, but they disagree on how much extra potential is left in the current price.
Bull case: 11% undervalued
"Further monetization of Ulta Beauty's 47 million member loyalty base using new AI driven personalization and data tools can deepen brand marketing spend on UB Media and shift a higher share of revenue toward media and other high margin services…"
Discover why this Narrative puts Ulta Beauty at 11% undervalued.
Bear case: roughly fairly valued
"The current valuation implies the share price already reflects steady execution on Ulta Beauty's growth algorithm, so any potential upside depends on the company extending its track record of profitable growth and capital returns…"
Explore why this Narrative puts Ulta Beauty at roughly fairly valued.
One more Ulta Beauty check before you stop at the share price
The people setting Ulta Beauty's priorities, and the way their pay packets rise or fall with your outcomes, can matter as much as any P/E comparison. See who runs Ulta Beauty and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com