


EN
Broadridge Financial Solutions (BR) On NYSE Tokenization Push And The Valuation Debate
Why Broadridge’s latest NYSE partnership matters for investors
Broadridge Financial Solutions (BR) just tied its future a little closer to the New York Stock Exchange through an agreement to support NYSE's planned tokenized securities platform with on chain governance and digital transfer agency services.
Broadridge Financial Solutions has caught a strong short-term tailwind, with the share price logging a 22.22% 1 month share price return and 16.47% 3 month share price return, even though the year to date share price return is still down 12.04% and the 1 year total shareholder return has declined 8.80%. The 3 year and 5 year total shareholder returns of 16.20% and 20.75% point to more moderate gains over a longer holding period.
That recent momentum has arrived alongside fresh catalysts, including Q1 results, confirmation of 2027 guidance, a US$200m share repurchase in the quarter and the NYSE tokenized securities partnership. Together, these developments have sharpened the market’s focus on Broadridge’s recurring revenue profile and perceived risk profile.
Scan how Broadridge’s tokenization push compares with other infrastructure and fintech players showing similar momentum by reviewing the 21 high quality undiscovered gems in this space.
The Broadridge Financial Solutions share price has already sprinted ahead on the NYSE partnership story, so the real question now is how much of that value is already in the quote and how much is still on the table.
Most Popular Narrative: 55.1% Overvalued
Broadridge Financial Solutions last closed at $193.92, while the most followed narrative pegs fair value down at $125. That gap sets up a very different take on today’s NYSE partnership rally.
The catch: the stock has been cut nearly in half from its 2025 highs, on fears that tokenized securities and AI could eventually erode the need for a proxy middleman. That is a real risk worth watching, but it has not shown up in the numbers yet. Retention and organic growth remain intact.
See why 3 investors see Broadridge Financial Solutions as 55% overvalued.
Result: Fair Value of $125 (OVERVALUED)
Still, this story can flip if tokenized securities sidestep Broadridge’s proxy plumbing or if regulators rewrite fee structures in ways that compress the economics.
Find out about the key risks to this Broadridge Financial Solutions narrative.
Another View: Cash Flows Paint a Different Picture
The first narrative around Broadridge Financial Solutions leans on a fair value of $125 per share, which frames the current $193.92 price as rich. A different lens tells a very different story.
Using the SWS DCF model, Broadridge’s shares at $193.92 are trading below an estimated future cash flow value of $371.87 per share, which implies the stock screens as undervalued on this framework. One approach leans on earnings-based fair value, and the other leans on long term cash generation. Which one you weight more heavily will drive how you see today’s NYSE partnership bump.
Look into how the SWS DCF model arrives at its fair value.
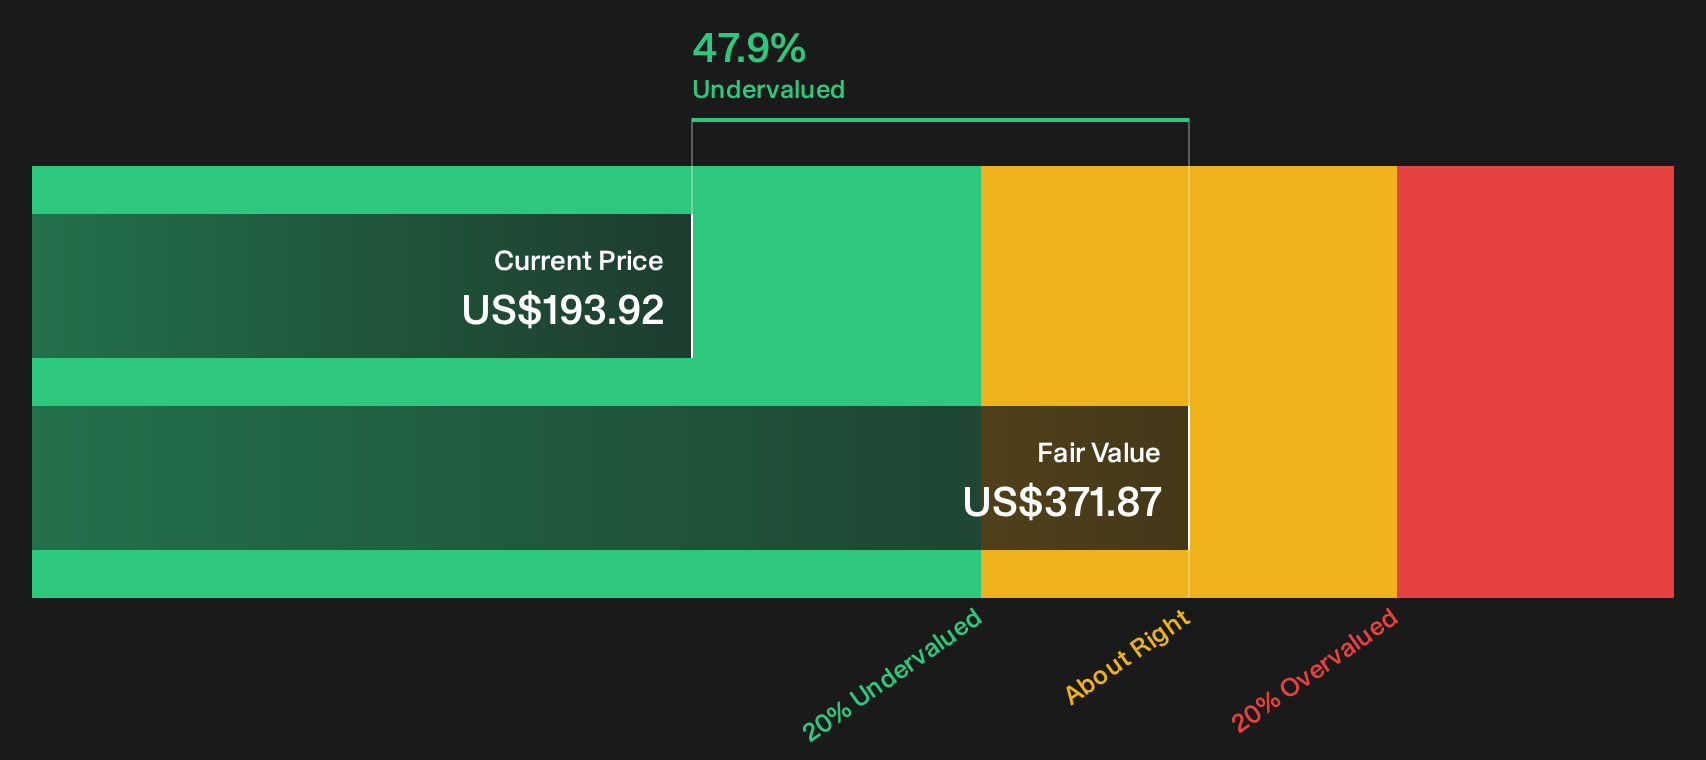
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Broadridge Financial Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Broadridge Financial Solutions can make sentiment feel stretched in both directions, so consider acting while the data is fresh and pressure test it yourself against the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Broadridge Financial Solutions?
If Broadridge Financial Solutions has your attention today, broaden your opportunity set and pressure test your thesis against fresh ideas that fit your own risk and return preferences.
- Target potential mispricing in quality companies by scanning a curated 42 high quality undervalued stocks that match strong fundamentals with prices that may not fully reflect them yet.
- Build a portfolio with income at the center by reviewing a hand picked 6 dividend fortresses that focus on meaningful yields and robust underlying businesses.
- Dial back portfolio stress by hunting through a 32 resilient stocks with low risk scores that screens for resilience when markets throw unexpected surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com