


EN
How Direct Line Integration At Aviva (LSE:AV.) Has Changed Its Investment Story
- Aviva has been integrating its Direct Line acquisition, reporting progress on cost synergies, underwriting focus, and plans for higher operating earnings per share between 2025 and 2028, while also managing heavier catastrophe losses in Canada linked to severe weather.
- The group is using this deal to deepen its position in both general insurance and wealth, aiming to leverage a large customer base for broader financial relationships and more capital-light fee income over time.
- Next, the focus shifts to how Aviva's Direct Line integration progress could reshape the existing investment narrative around capital-light growth and cash.
Scan beyond Aviva and see how other high quality insurers and financials are priced today by running the 15 high quality undervalued stocks alongside this Direct Line integration story.
Aviva Investment Narrative Recap
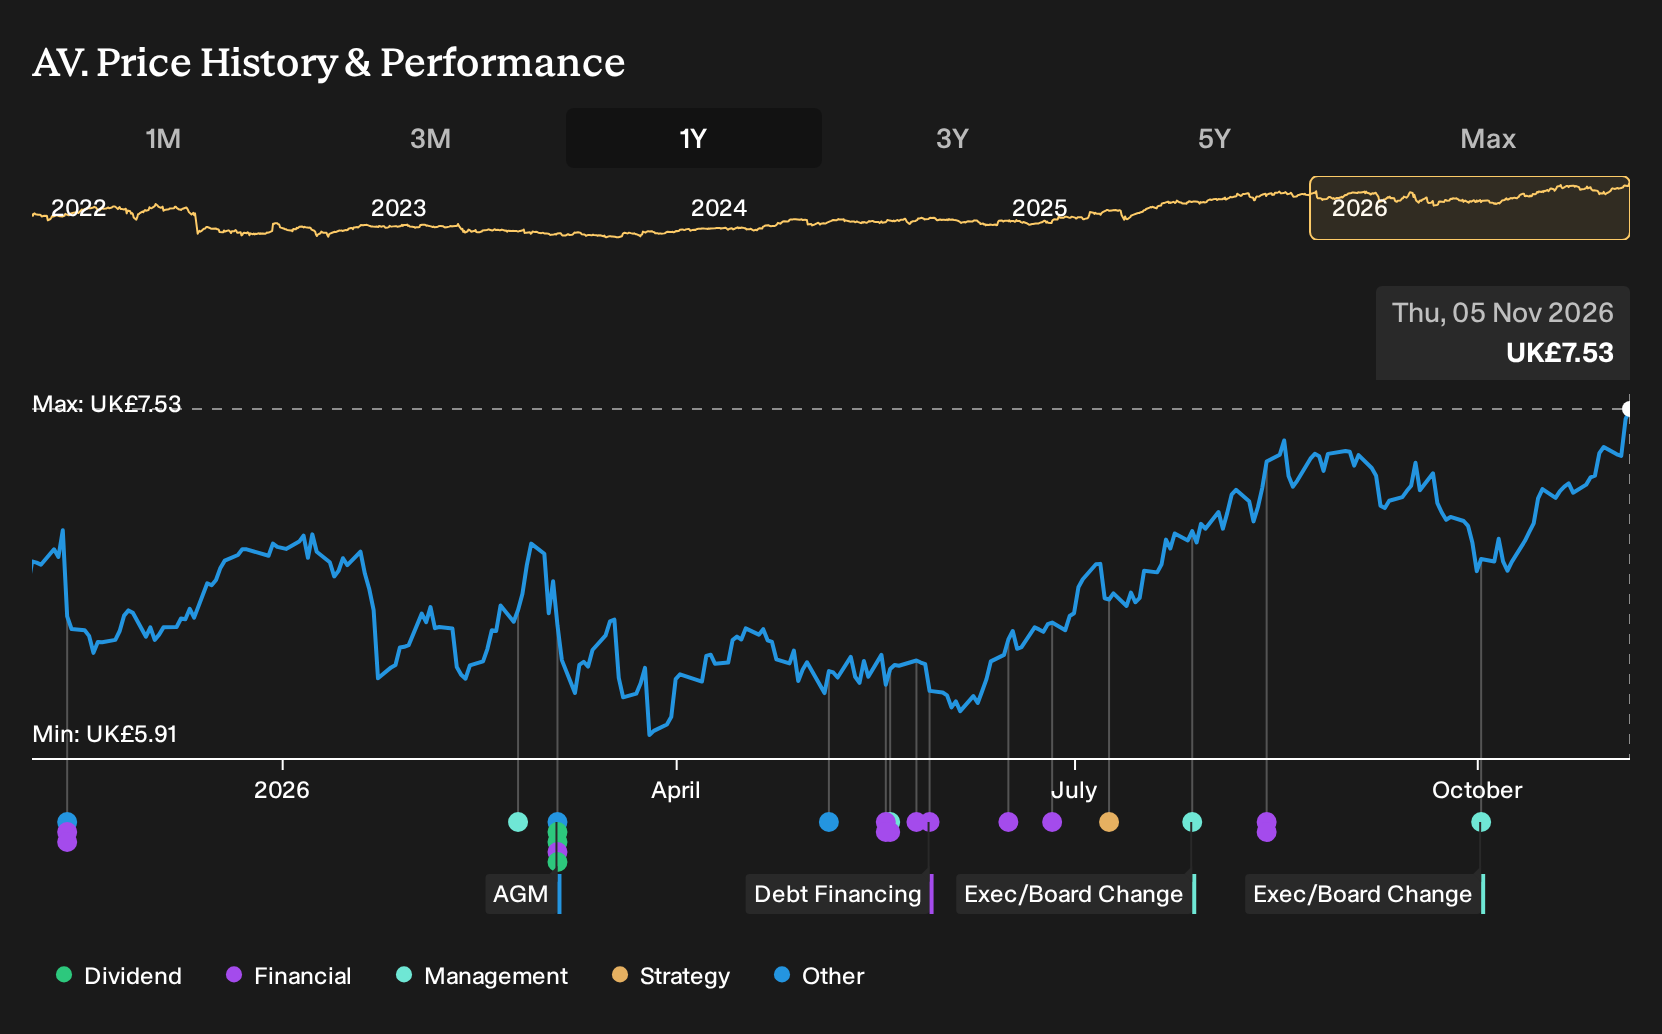
For Aviva, the shareholder story leans on capital light growth, disciplined underwriting and turning a large client base in the UK, Ireland and Canada into steadier fee income. The Direct Line deal and wealth business are central to that. The recent share price strength does not change that thesis, but it raises the bar for execution.
In the near term, the key operational swing factor is how cleanly Aviva beds in Direct Line while keeping underwriting tight, especially in UK and Canadian personal lines. The biggest risk sits in integration complexity and weather related catastrophe losses in Canada if severe conditions persist.
The most relevant recent development is Aviva’s progress update on Direct Line, including cost and capital synergies and the target to lift operating earnings per share between 2025 and 2028. That matters because it ties directly into the firm’s attempt to lean harder into fee heavy, capital light businesses as a larger share of group profit.
For you as an investor, the practical question is whether Aviva can keep delivering on those integration milestones while maintaining pricing discipline in motor and home and absorbing higher catastrophe claims. If management continues to execute on cost savings and digital efficiencies, that integration story remains a meaningful factor for both cash generation and dividend capacity.
What The Aviva Earnings Path Implies
Aviva's narrative projects £45.4b revenue and £1.9b earnings by 2029. That profile overlays on analyst expectations for 16.5% yearly revenue growth and an earnings increase of about £1.1b from £767.0m today.
Uncover why Aviva's fair value indicates an 8% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Seven fair value estimates from the Simply Wall St Community cluster between about £6.93 and £13.12, so some investors see Aviva as almost twice as expensive as others do. Those views were formed before the Direct Line deal update and do not reflect ongoing integration risk. Use them as a starting point to explore contrasting opinions.
Explore 6 other Aviva fair value estimates, including one that suggests up to 74% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aviva research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aviva. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aviva's overall financial health at a glance.
Looking For More Ideas Beyond Aviva?
Once you have a view on Aviva, it helps to compare it with other opportunities that share similar qualities or offer a different balance of risk and reward. The Simply Wall St Screener lets you filter for specific traits, so you can quickly zero in on a shortlist that fits your approach.
- If resilience matters most to you, start with companies that score well on risk and stability by checking out 4 resilient stocks with low risk scores.
- For investors who focus on balance sheet strength and fundamentals, build a watchlist from the list of solid balance sheet and fundamentals (9 results) to see which businesses look financially robust.
- If you prefer hunting for underappreciated opportunities with quality traits, scan through the 5 high quality undiscovered gems and see which stocks deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com