


EN
CECO Environmental Stock In Focus Ahead Of Earnings Report and Investor Conferences
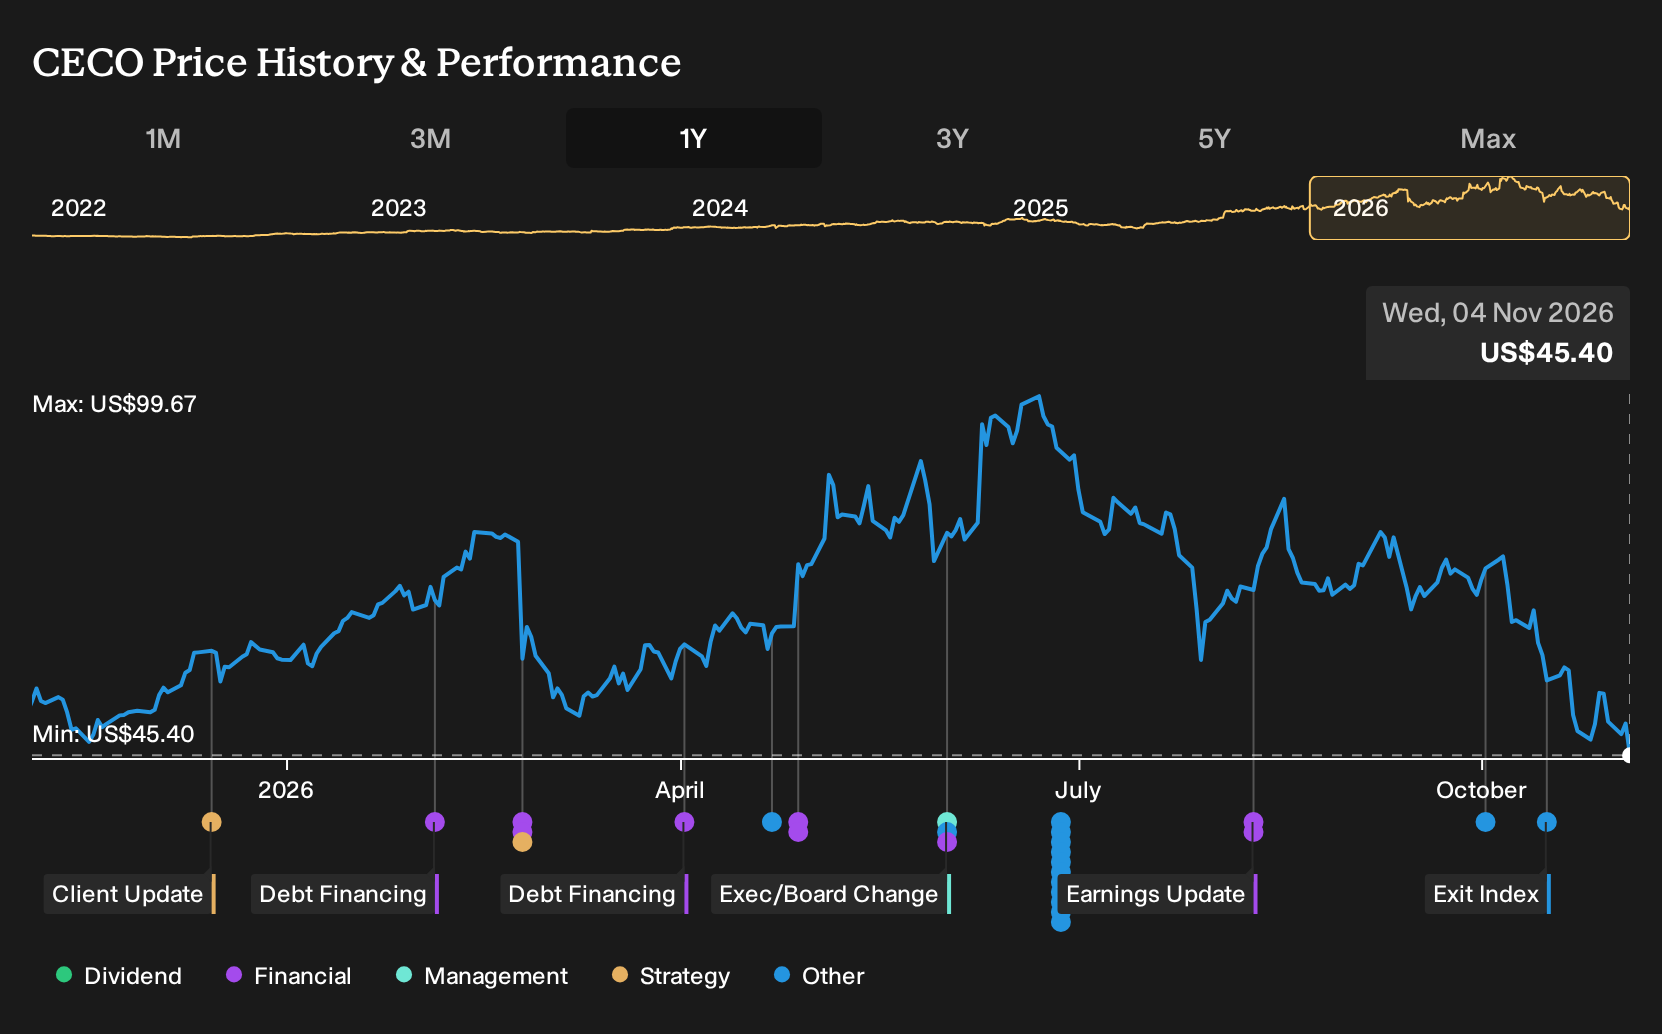
- CECO Environmental recently announced that CEO Todd Gleason and VP Marcio Pinto participated in November investor conferences and hosted one on one meetings, while the business prepared to release third quarter 2026 results supported by project backlogs across power generation, natural gas infrastructure, electronics and reshoring activity.
- The combination of an upcoming earnings release tied to specific end market demand drivers and direct investor engagement highlights how closely CECO Environmental’s order visibility, cost pressures and foreign currency effects are being scrutinized in relation to its long term project pipeline.
- We will look at how CECO Environmental’s investment narrative is shaped by upcoming third quarter results and CEO conference outreach.
Compare CECO Environmental’s conference-driven catalyst setup with other industrial players leaning into infrastructure, reshoring and energy demand by scanning our hand picked 40 power grid technology and infrastructure stocks today.
CECO Environmental Investment Narrative Recap
To own CECO Environmental, you need to be comfortable with a project heavy model tied to power generation, natural gas infrastructure, electronics, and reshoring work. The big swing factor in the near term is how cleanly that record backlog converts into revenue and cash on the upcoming third quarter 2026 update, especially within Engineered Systems and Industrial Process Solutions.
The sharpest risk right now sits around cost inflation, higher selling and administrative spend, and foreign currency drag squeezing margins while leverage questions remain in the background. November’s earnings print and commentary around order timing probably matter more to the story than the conference appearances themselves.
The most relevant fresh item is CECO Environmental’s plan for CEO Todd Gleason and VP Marcio Pinto to present at the Baird 2026 Global Industrial Conference and the 18th Annual Southwest Ideas Conference, with materials posted on the investor relations site. That timetable lands directly on top of the third quarter 2026 results on November 9.
Investors get an earnings release plus rapid fire conference Q&A, which can sharpen views on backlog quality, cost discipline, and foreign exchange sensitivity. This pairing could also surface more detail on Thermon integration, project phasing in power and gas, and how management is thinking about balance sheet flexibility if industrial water awards in the Middle East remain delayed.
CECO Environmental's narrative projects US$2.5b revenue and US$358.9m earnings by 2029. This aligns with analysts' expectations of 41.0% yearly revenue growth and an earnings change of roughly US$390m, moving from a loss of US$30.6m today to those forecast profits.
Discover why CECO Environmental's fair value suggests a 146% potential upside to its current price, which may not be available for much longer.
Exploring Other Perspectives
Not every analyst views CECO Environmental through the same lens. While the consensus narrative leans on record backlog, the most cautious group focused instead on execution risk in large power projects and a slower industrial water ramp. Those bearish estimates pencilled in revenue of about US$2.1b and earnings near US$231.3m by 2029, so your takeaway may shift as conference commentary and the upcoming results reshape these pre-news forecasts.
Explore 3 other CECO Environmental fair value estimates, including one that suggests it could be worth just $108.23!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CECO Environmental research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CECO Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CECO Environmental's overall financial health at a glance.
Looking For More Investment Ideas Beyond CECO Environmental?
If CECO Environmental has sharpened your thinking about project driven industrial stories, it can help to cross check those insights against a wider watchlist built with the Simply Wall St Screener.
- For investors who want potential upside but still care about quality, scan a curated mix of resilient businesses through our 21 high quality undiscovered gems.
- If capital preservation and steadier profiles matter more to you than chasing every swing, filter for companies with lower risk scores using the 32 resilient stocks with low risk scores.
- When you prefer balance sheets that can absorb shocks and fund growth internally, build a shortlist from the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com