


EN
Millicom International Cellular (TIGO) Could Be 18% Below Fair Value As Q3 Cash Flow Guidance Holds
Millicom International Cellular (TIGO) is back in focus after its Q3 2026 earnings call on 5 November, which paired record adjusted EBITDA with an earnings miss and reaffirmed full year equity free cash flow guidance.
Millicom International Cellular’s share price has slipped 12.54% over the past 30 days and 18.52% over 90 days, even as recent headlines focused on record adjusted EBITDA, 5G plans in Colombia, and the Guatemala litigation settlement. Despite that pullback, the share price has a 39.91% year to date gain, and the 1 year total shareholder return of 75.22% along with a very large 3 year total shareholder return suggest longer term momentum has been strong.
Spot similar turnaround stories by scanning our curated list of 21 high quality undiscovered gems that pair solid fundamentals with under-the-radar price action.Millicom International Cellular now trades at a meaningful discount to both analyst targets and one estimated intrinsic value, even after Q3 guidance was reaffirmed. Is this a mispriced cash flow story, or caution that fits the earnings miss and Colombia spend ahead?
Most Popular Narrative: 18% Undervalued
At a last close of $79.12 versus a narrative fair value of $96.39, Millicom International Cellular is framed as materially underpriced, with that gap resting heavily on how durable its cash generation and equity free cash flow trajectory prove to be.
The current valuation implies that Millicom shares are trading very strongly and at levels some reports describe as well above estimated intrinsic value. Yet this narrative still treats the stock as undervalued and assumes the market is underpricing the durability of its cash generation and balance sheet repair.
See why 20 investors see Millicom International Cellular as 18% undervalued.
Result: Fair Value of $96.39 (UNDERVALUED)
Still, the Millicom International Cellular story can shift quickly if higher net debt near US$8.1b bites harder, or if Guatemala related legal claims widen beyond existing provisions.
Find out about the key risks to this Millicom International Cellular narrative.
Another View: Millicom International Cellular Through A P/E Lens
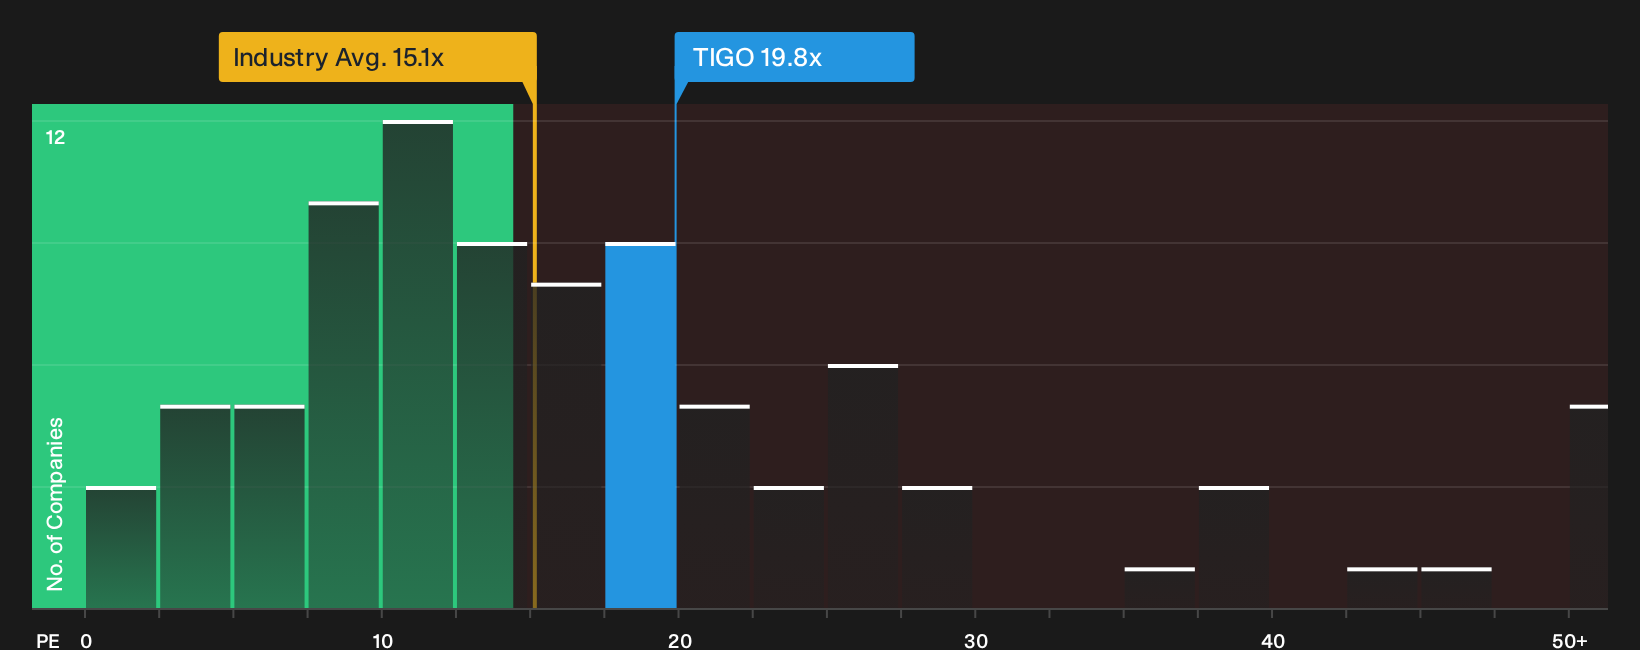
Our DCF work points to Millicom International Cellular trading well below an estimated future cash flow value of $306.44, yet the market is assigning a P/E of 19.8x, which is higher than the global wireless telecom average of 15.1x and below an internal fair ratio of 22x. Is this a genuine valuation cushion or just thinner compensation for taking on higher leverage and legal risk?
Investors who prefer earnings based gauges over cash flow models may want to study how that fair ratio could change if margins, interest costs or Guatemala outcomes move away from current assumptions, and how that would feed through to the P/E the market is willing to pay. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Millicom International Cellular so far, or a clear message hiding in plain sight. Dig into the data yourself, weigh the risks against the potential rewards, and then decide how you feel about the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Millicom International Cellular?
If you stop with Millicom International Cellular, you risk missing other setups where price, balance sheet strength, and income potential line up in your favor.
- Target resilient wealth builders by scanning a curated set of 32 resilient stocks with low risk scores that aim to balance upside with tighter risk controls.
- Hunt for quality at a discount by reviewing a focused group of 42 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- Build a cash flow friendly watchlist by checking out a handpicked pool of 6 dividend fortresses designed for investors who care about income as well as durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com