


EN
How Stronger Lending Growth Will Impact Metro Bank Shares (LSE:MTRO)
- Metro Bank Holdings reported a 37% year-on-year rise in lending across target segments in Q3 2026, with exit net interest margin at 3.45% and financial guidance reaffirmed for return on tangible equity targets over the next three years.
- The update highlights how Metro Bank Holdings is leaning into higher yielding lending and portfolio adjustments, and is using fixed rate treasury maturities to support stronger margin economics across its loan book.
- The focus now turns to how Metro Bank Holdings' stronger net interest margin may reshape its investment narrative for long term shareholders.
Scan beyond Metro Bank Holdings and line up other lenders and financials that could benefit from similar margin and balance sheet setups with the hand picked list of solid balance sheet and fundamentals (9 results).
Metro Bank Holdings Investment Narrative Recap
To own Metro Bank Holdings, you need to buy into a simple idea. The bank is trying to convert its relationship-led, branch-heavy model and relatively low-cost deposits into a higher net interest margin through a shift toward higher yielding lending. The latest update on lending growth and a 3.45% exit NIM speaks directly to that effort.
The key short term swing factor now is whether Metro Bank Holdings can keep improving margin and balance sheet mix without asset quality or funding costs biting back. Loan book risk concentration, high bad loan levels and a low allowance for bad loans remain important pressure points, so any signs of credit stress would quickly challenge the thesis.
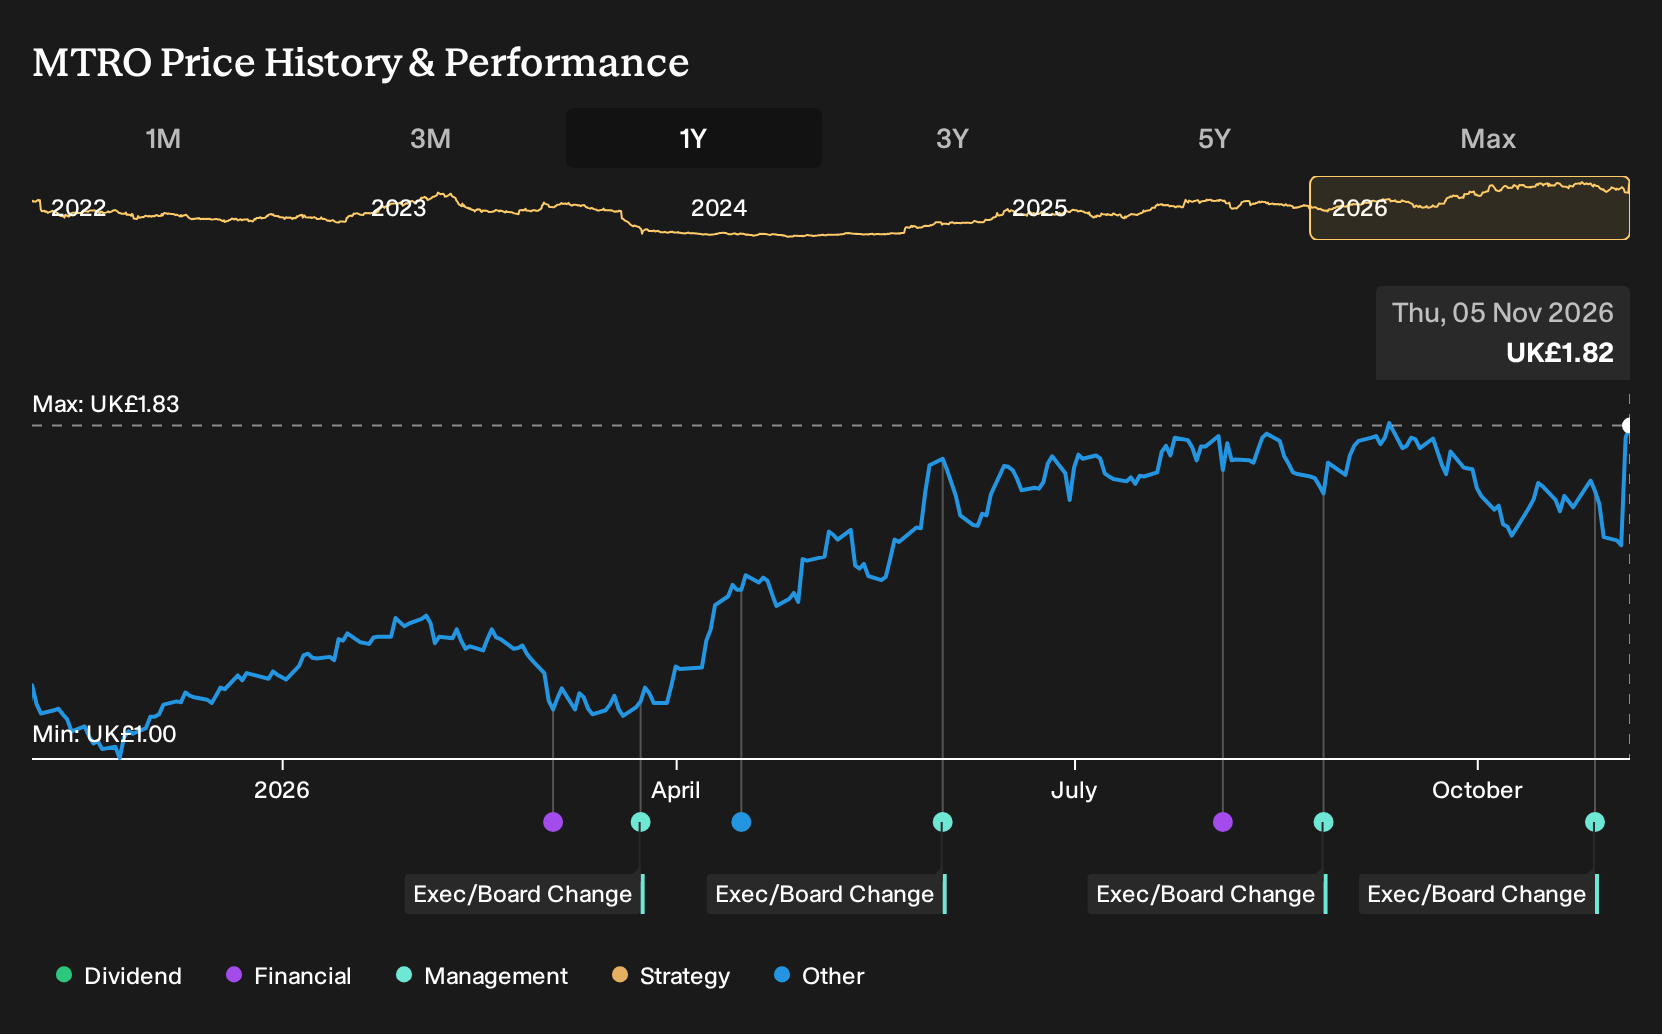
The board announcement around Chair Robert Sharpe stepping down at the end of his six year term in October 2026, with Catherine Brown as Interim Chair and Michael Torpey as Senior Independent Director, matters for this story. Chair and SID changes can influence how firmly the board backs management’s push into specialist and commercial lending.
For shareholders watching catalysts, the focus is whether this refreshed leadership duo can maintain continuity on balance sheet discipline while supporting Metro Bank Holdings’ margin targets and cost efficiency plans. Execution on asset rotation, digital investments and capital management will likely be judged through that governance lens over the next few reporting periods.
Metro Bank Holdings is tied to analyst forecasts that point to £913.1 million in revenue and £250.3 million in earnings by 2029. These projections assume yearly revenue growth of 16.3% and an earnings increase of about £196.6 million from £53.7 million today.
Uncover why Metro Bank Holdings' fair value indicates a 7% potential downside to its current price. This valuation gap leaves little room for error.
Exploring Other Perspectives
One alternate view puts board stability at the center of the Metro Bank Holdings story. The most optimistic analysts were already pencilling in revenue of about £956.5 million and earnings near £287.9 million by 2029 before this chair transition news. You can treat those richer forecasts as one end of a wide opinion range that may shift as governance evolves.
Explore another Metro Bank Holdings fair value estimate, including one that suggests it could be worth as much as £1.70.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Metro Bank Holdings research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Metro Bank Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Metro Bank Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Metro Bank Holdings?
If you want to stress test your view on Metro Bank Holdings, compare it against a wider watchlist built around balance sheet strength, income potential and valuation quality. The Simply Wall St Screener can help you quickly build that broader bench of candidates so you are not relying on a single financial stock to carry your thesis.
- For investors who want growth potential backed by strong finances, review 5 high quality undiscovered gems that combine robust fundamentals with less crowded ownership.
- If capital preservation and steadier profiles matter most to you, start with 4 resilient stocks with low risk scores that screen for resilient businesses with lower overall risk characteristics.
- Income focused readers who care about cash returns today can filter for 6 dividend fortresses that aim to pair higher yields with more durable payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com