


EN
Qualcomm (QCOM) Stock Slides As Q4 Earnings Meet Data Center Margin Pressure
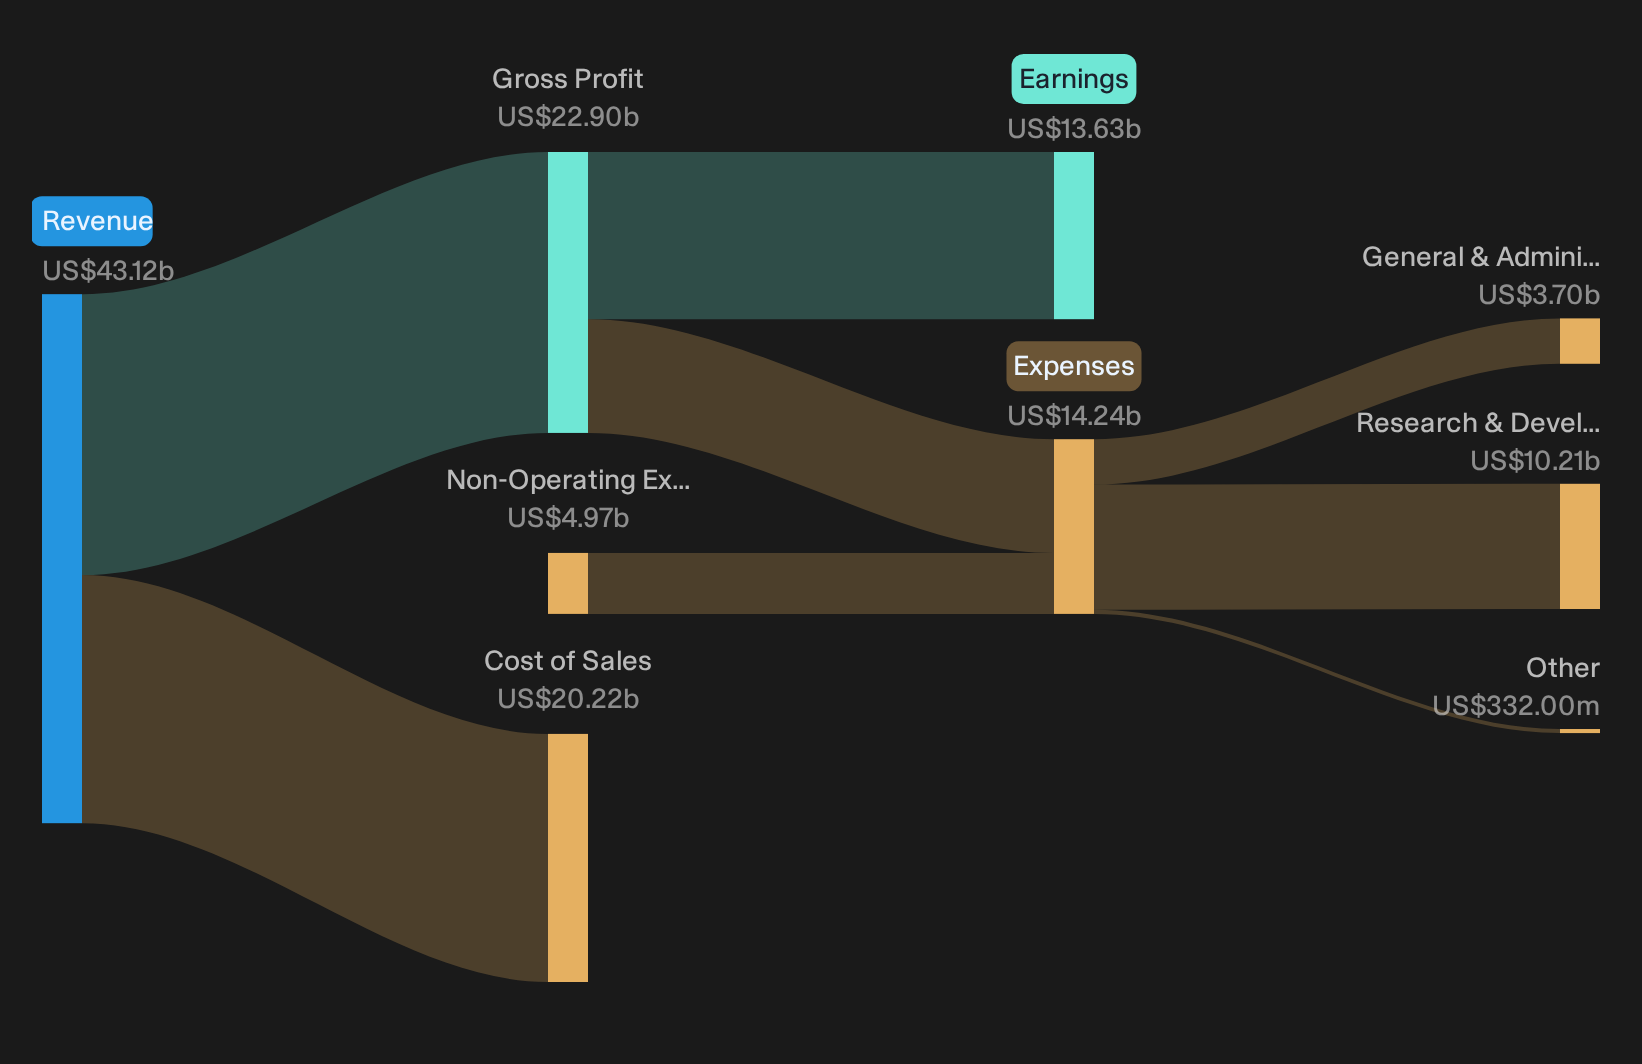
Qualcomm entered this Q4 2026 report carrying the label of a high margin chip powerhouse with a discounted P/E and a cleaner story around Apple and Huawei. The raw results were solid, with non GAAP revenue of US$10.4b and earnings per share of US$2.17, yet the stock fell 9.5% on the day to about US$156. That clash between a sharply lower valuation and still strong profitability, including a trailing net margin of 31.6%, is the expectation gap investors now need to examine.
Love Qualcomm's high margins and discounted P/E but uneasy about a sharp price drop after decent earnings? You can use our 42 high quality undervalued stocks to compare QCOM with other profitable stocks that still trade at compressed valuations.
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): US$10,322 million compared with US$11,271 million (down 8.4%)
- Net Income (Excl. Extra Items, Q4 2026 vs. Q4 2025): US$1,251 million compared with a loss of US$3,117 million (swing back to profit)
- Basic EPS (Q4 2026 vs. Q4 2025): US$1.18 compared with a loss of US$2.89 per share (return to positive earnings per share)
- Trailing Net Margin (Last 12 Months vs. Prior Year): 31.6% compared with 12.7% (very large improvement in profitability ratio)
Qualcomm just folded its fast-growing data center unit into QCT. Ask Charlie what Qualcomm’s new data center targets really imply.
Evaluating Qualcomm’s Non‑Handset Expansion Claims
Qualcomm’s bullish story hangs on non handset engines, not phones.
"Bullish analysts expect Qualcomm to grow non handset revenue across data center, automotive and IoT toward the company’s FY2029 target of US$40b, supported by long term data center agreements and design win pipelines."
The latest quarter gives that ambition some tangible markers. Automotive exited FY26 at roughly a US$8b annualized pace, with Q4 auto revenue up sharply and the first quarter above US$2b. Management folded data center into QCT and is already guiding to more than US$650m of data center revenue in Q1 FY27, with a reiterated US$5b FY27 target tied to multi year hyperscaler agreements.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Qualcomm Margins Strain Under Data Center Ambitions
Bearish investors worry that Qualcomm’s AI push wins revenue but erodes its historic profitability.
"Although Qualcomm is pitching a faster pivot into data center AI with targets for US$5b of data center revenue in fiscal 2027 and US$15b in fiscal 2029, the latest research suggests that initial custom ASIC ramps may come through on materially lower gross margins and could dilute QCT margins by around 150 to 200 basis points, which would limit the earnings benefit even if top line targets are met."
The latest print leans toward that concern. QCT is guided to a 20% to 22% EBT margin in Q1 FY27, and management acknowledged that folding in data center trims reported QCT margins by about 3 percentage points. Price increases and expected gross margin recovery from Q2 are helpful, yet near term guidance still shows profitability under pressure while data center revenue is only ramping from a relatively small base.
Hunt For Mispriced AI Plays
QUALCOMM shows that profit strength and share price can diverge for a time. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 42% below our estimate - uses AI centric networking and data center gear to shift revenue toward recurring consumption based services.
- Company 2 - 38% below our estimate - turns an AI infrastructure contract backlog and multicloud database expansion into subscription focused software and cloud revenue.
- Company 3 - 35% below our estimate - attacks high speed optical markets after acquiring silicon photonics capabilities to broaden a fast data connectivity stack.
That is three of the list. See the full list of 42 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com