


EN
Eaton Stock Earnings Beat Lifts Full Year Guidance
- Eaton reported record Q3 2026 results, with sales of US$8.9b and net income of US$1.1b, and raised full year earnings guidance while affirming a US$1.10 quarterly dividend declared in October.
- The company’s Electrical Americas and Electrical Global operations produced strong organic growth and margin gains alongside record orders and backlog, highlighting how recent acquisitions and capacity expansions are feeding into Eaton’s earnings profile.
- We will now look at how Eaton's upgraded full year earnings guidance shapes the broader investment narrative around its electrical focus.
Eaton Investment Narrative Recap
Eaton is still mainly an electrical and aerospace story, so the key point for a shareholder is that demand around grid, power and data center buildouts translates into resilient orders and solid execution on recent capacity and acquisition moves. Q3 2026 supported that thesis with record revenue and higher adjusted earnings guidance, which points to healthy underlying activity in those core franchises.
The main near term swing factor is how efficiently Eaton converts its record backlog into shipped product without eroding margins as new facilities ramp. A key risk is that weaker regions and legacy vehicle exposure, together with higher debt and execution on restructurings, could limit overall profitability even if electrical demand remains constructive.
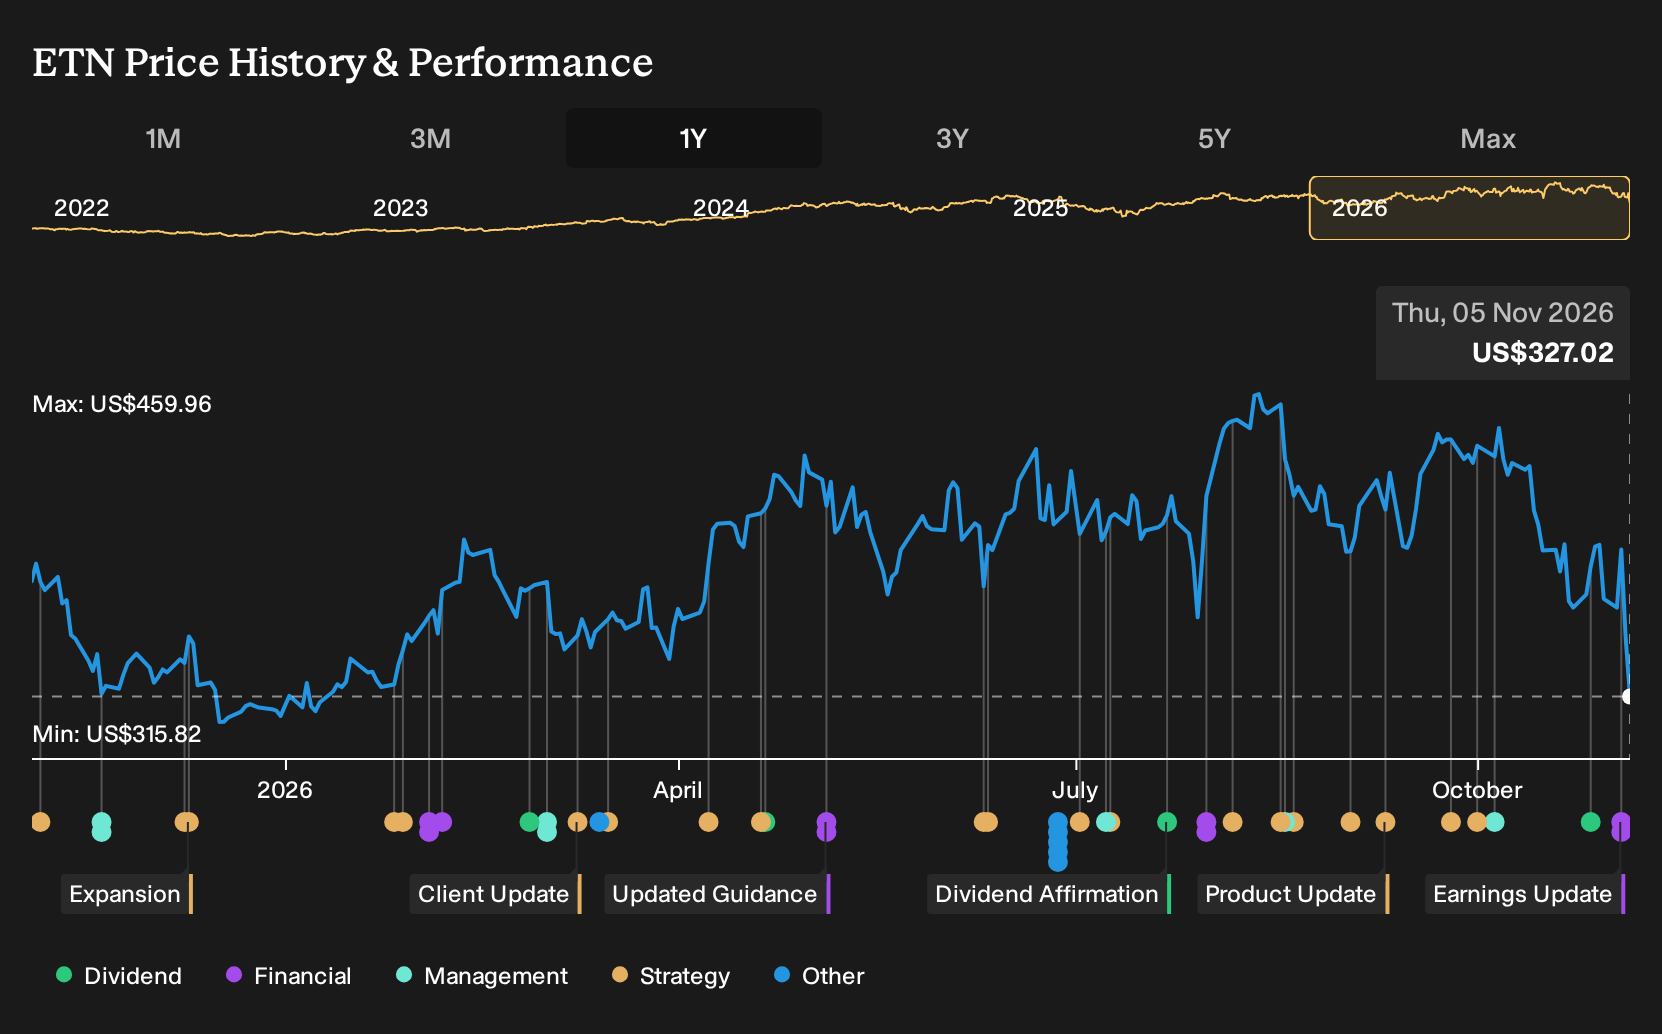
The most relevant recent announcement for this story is Eaton’s updated guidance calling for full year 2026 net income per diluted share of US$10.39 to US$10.49. That comes after Q3 results that exceeded the high end of prior guidance on every major metric, including record organic growth and record adjusted earnings per share.
For investors, that guidance range is useful because it connects the strong order book and capacity expansions to a concrete earnings outcome for this year. It also sets a bar that raises execution risk. Any shortfall in backlog conversion, integration of acquisitions such as Boyd Thermal or margin delivery in Electrical Global could pressure near term earnings and confidence in Eaton’s longer term electrical focused thesis.
Eaton's current earnings are US$3.8b, with analysts expecting consensus earnings of US$7.5b by 2029. That implies an earnings increase of about US$3.7b. The same forecasts assume revenue growth of 13.0% a year and lead to projected 2029 revenue of US$43.4b.
Uncover why Eaton's fair value indicates a 47% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate lens on Eaton focuses less on data center excitement and more on labor constraints as a risk. Before this earnings beat, the most optimistic analysts were already modeling revenue of about US$46.3b and earnings near US$8.1b by 2029. Those projections could shift meaningfully as this fresh guidance and Q3 performance get absorbed.
Explore 6 other Eaton fair value estimates, including one that suggests potential upside of as much as 63% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eaton research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking for more investment ideas beyond Eaton?
If Eaton’s electrical focus has your attention but you want a broader watchlist, the Simply Wall St Screener can help you quickly filter the market into focused shortlists that match your style and risk tolerance.
- If you care most about quality at a reasonable price, start with companies that look attractively valued on both earnings and balance sheet strength by scanning 42 high quality undervalued stocks.
- If smoother ride potential matters more than maximum upside, concentrate on businesses with stronger financial resilience and fewer flagged issues by checking the 32 resilient stocks with low risk scores.
- If you want to back under-the-radar opportunities with solid numbers, sort through a 21 high quality undiscovered gems that are already posting robust fundamentals but receive less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com