


EN
Is RELX (LSE:REL) Undervalued On Elsevier AI Growth Or Is The Rally Priced In?
RELX (LSE:REL) is back in focus after fresh commentary on its Elsevier division, where AI-enabled tools like LeapSpace and Sherpath AI are gaining traction and revenue growth has reached 6%.
Recent trading reflects that story gaining traction with investors. The share price is up 19.95% over the past month and 17.40% over 90 days, yet the 1-year total shareholder return is still down 4.53%. This indicates that momentum in RELX has picked up recently, while the longer record remains more mixed.
Scan how RELX compares with other AI-focused information providers by reviewing a hand-picked set of 4 AI small caps gaining attention after recent product launches and share price momentum.
Bulls see RELX as an AI powered compounder, while bears see a mature information group enjoying a short squeeze. Which picture fits the current valuation after this sharp rebound in the shares?
Most Popular Narrative: 10.5% Undervalued
On the most followed view of RELX, a fair value of £34.46 sits meaningfully above the last close at £30.84. This puts the recent AI driven rally in context instead of dismissing it as pure excitement.
The expanding use of AI-enabled fraud and identity solutions in Risk, where RELX processes around 145 billion digital transactions each year and over 90% of divisional revenue is already machine-to-machine, creates scope for customers to add more high value tools over time. This can support sustained revenue growth and operating leverage.
See why 83 investors see RELX as 11% undervalued.
Result: Fair Value of £34.46 (UNDERVALUED)
Still, the bullish RELX story frays quickly if AI competitors pressure pricing in Legal and Risk, or if open access policies squeeze returns in STM.
Find out about the key risks to this RELX narrative.
Another View: RELX On Earnings Multiples
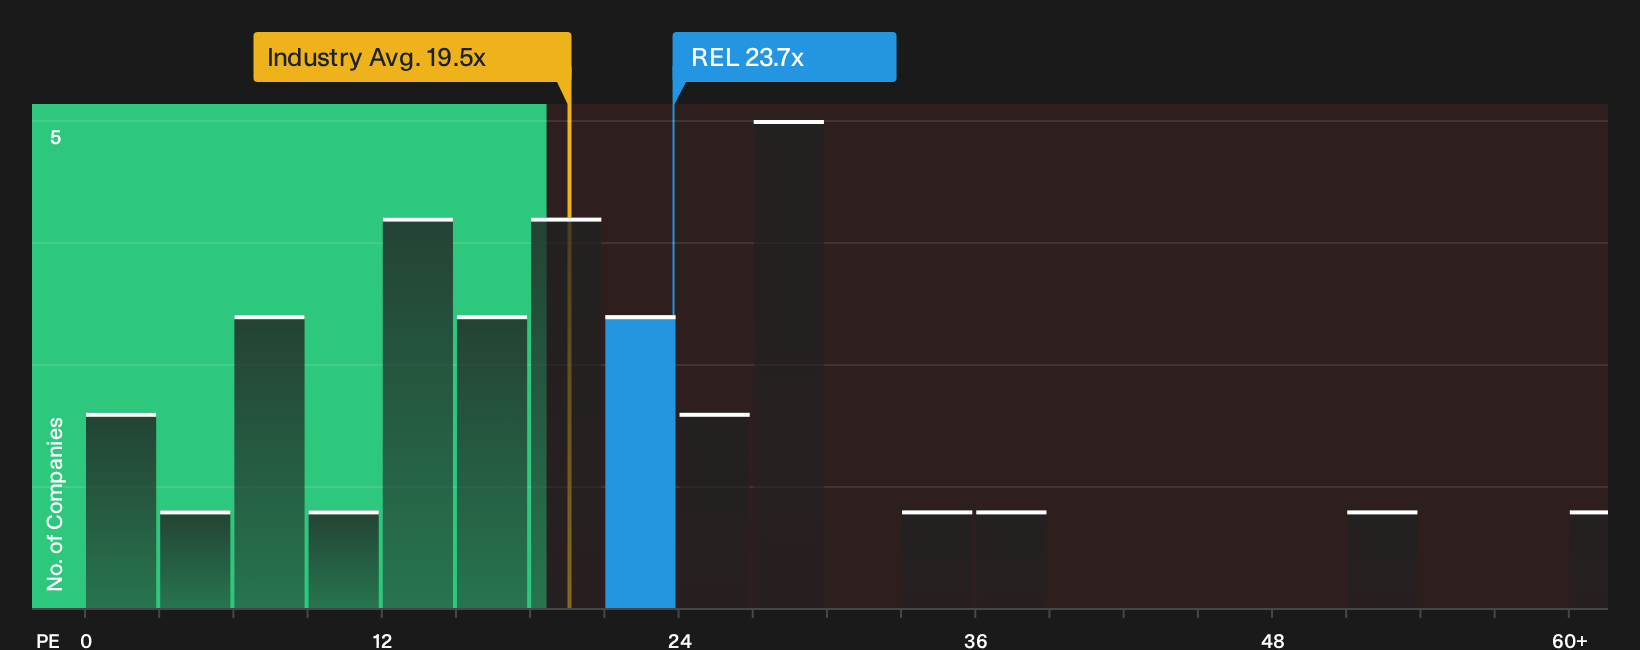
There is a very different read on RELX when you switch from fair value models to simple earnings multiples. The shares trade on a P/E of 23.7x, which is higher than both the peer average at 21.4x and the wider UK Professional Services group at 19.5x.
Set against that, the fair ratio is 34.3x. This implies the market could move toward a richer earnings multiple if sentiment and delivery line up. The gap between 23.7x today and a 34.3x fair ratio points to either valuation risk if expectations slip or room for re rating if they hold. How do you view that balance between risk and potential upside?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on RELX so far, with both optimism and concern in the air. Do not wait for consensus to settle. Review the full picture of risks and rewards for yourself with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond RELX?
Do not stop your research with RELX. Broaden your watchlist by scouting other potential opportunities that fit clear, simple criteria using the Simply Wall Street Screener.
- Target value opportunities by scanning a 15 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them yet.
- Strengthen portfolio resilience by searching a list of solid balance sheet and fundamentals (9 results) that can help you focus on companies with healthier financial footing.
- Hunt for future standouts by reviewing a 5 high quality undiscovered gems before they attract wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com