


EN
GFL Environmental (TSX:GFL) Could Be 11% Below Fair Value As Guidance Improves
GFL Environmental (TSX:GFL) just paired a fresh quarterly update with higher full year 2026 revenue guidance. This puts its recent sales performance and outlook for the rest of the year in sharper focus.
Recent trading reflects that story. The share price has climbed to CA$64.57, with a 30 day share price return of 6.73% and a 90 day gain of 12.10%. The 3 year total shareholder return of 65.07% points to longer term momentum that investors are weighing against the fresh guidance and recent net losses.
Scan how GFL Environmental compares with other waste and infrastructure businesses showing similar momentum and guidance upgrades by reviewing the hand picked list of solid balance sheet and fundamentals (5 results) in the same sector.
GFL Environmental now trades below both analyst targets and an estimated intrinsic value, even after the recent jump. Is that discount a mispricing, or a simple reflection of ongoing net losses and execution risk?
Most Popular Narrative: 11% Undervalued
The most followed narrative on GFL Environmental pegs fair value at about CA$72.67, above the last close at CA$64.57. That gap is based on expectations for free cash flow, acquisitions and margin resilience to play through under a 6.94% discount rate.
The current valuation implies the share price does not fully reflect a business generating about $2.29b of adjusted EBITDA in 2026, pro forma EBITDA of roughly $2.72b with SECURE and over $1.13b of adjusted free cash flow at roughly 42% conversion on a leverage-neutral basis.
See why 22 investors see GFL Environmental as 11% undervalued.
Result: Fair Value of CA$72.67 (UNDERVALUED)
Still, softer construction and special waste volumes, along with the Missouri regulatory issues around fees, could pressure GFL Environmental's pricing power and future earnings path.
Find out about the key risks to this GFL Environmental narrative.
Another View: What GFL Environmental’s P/S Ratio Is Telling You
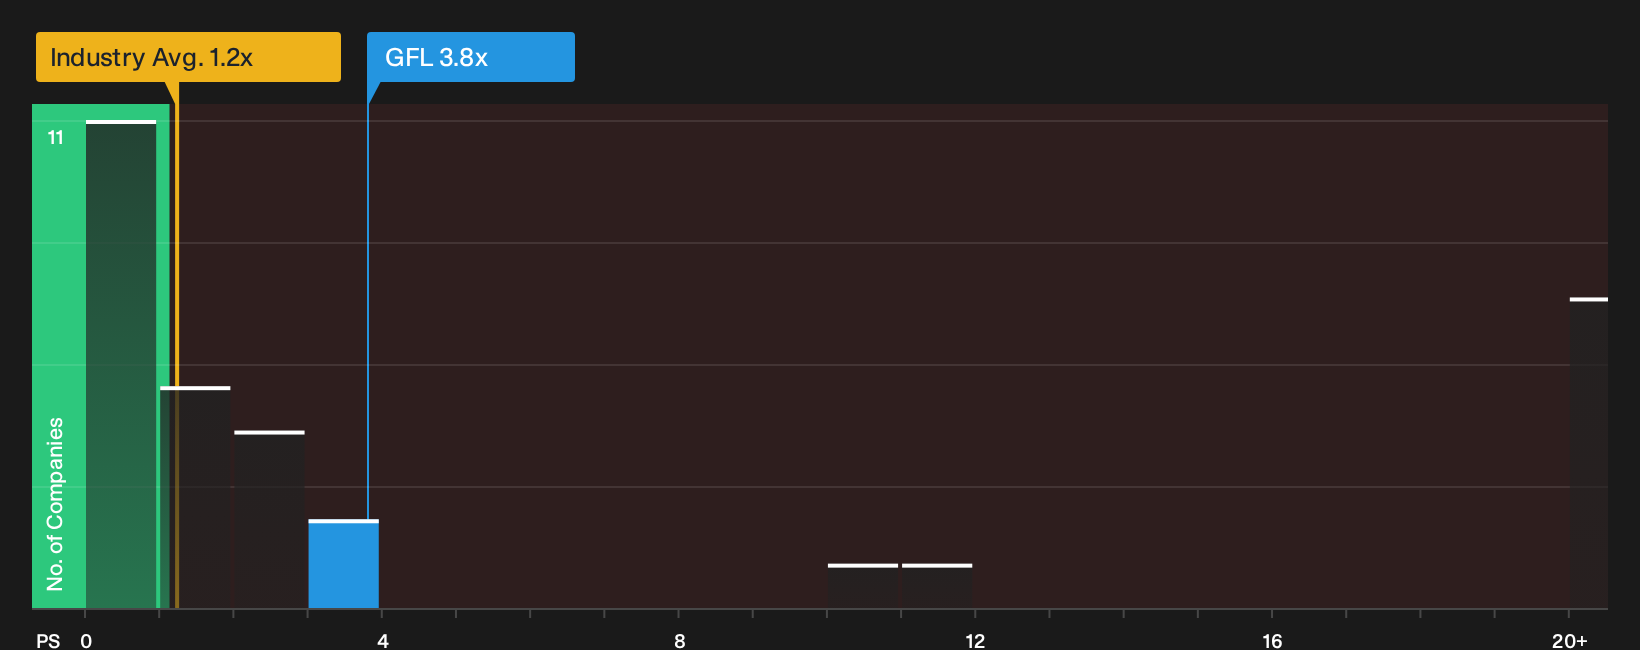
The fair value story on GFL Environmental looks very different when you switch from cash flow models to a simple sales based lens. The stock trades on a P/S of 3.8x, above the 3.6x fair ratio, the 2.6x peer average and the 1.2x industry level. This lifts valuation risk even with the DCF upside case in mind. Does that premium reflect quality, or just optimism being priced in early?
To weigh those trade offs in more detail, it helps to see how the current multiple compares across the full valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the GFL Environmental story so far. If the blend of concerns and potential upside has you undecided, spend a few minutes with the numbers yourself and pressure test both sides of the argument using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond GFL Environmental?
If GFL Environmental has you thinking harder about valuation and risk, consider expanding your research. Broader context from other stocks can sharpen every decision you make.
- Target reliable cash generators by comparing businesses with strong earnings quality and disciplined balance sheets using the 6 high quality undervalued stocks.
- Prioritise resilience by reviewing companies that combine lower risk scores with steadier fundamentals through the 8 resilient stocks with low risk scores.
- Look for financially robust potential market outliers with the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com