


EN
STERIS (STE) Climbed After Its Latest Update, What Is Drawing Investors In?
STERIS (STE) just delivered quarterly results that topped analyst expectations on both revenue and earnings, supported by solid contributions from its Healthcare Products and Life Sciences units, as well as a higher full-year adjusted EPS outlook.
The earnings beat and raised outlook have quickly fed into price action, with STERIS showing a 21.79% 30 day share price return and a 9.47% 7 day move, even though the 1 year total shareholder return declined 1.20% and the 3 year total shareholder return is 30.54%.
Ride this earnings momentum by lining up STERIS against a curated group of quality healthcare and medical stocks using our list of solid balance sheet and fundamentals (25 results).The question now is simple. After STERIS surged on an earnings beat and a higher full year outlook, does the current valuation still leave enough upside to justify new risk, or has most of the reward already been claimed?
Most Popular Narrative: 3% Undervalued
On the latest numbers, the most followed narrative pegs STERIS at a fair value of $263.13, slightly above the last close of $254.12. This leaves a modest valuation gap tied to how recurring chemistries and services fuel earnings over time.
Continued mix shift toward recurring chemistries and services, which now account for roughly 80% of STERIS revenue versus about 20% a decade ago, can add stability to organic revenue and support operating leverage into earnings.
Customer moves to localize medical device and pharmaceutical manufacturing and maintain resilient supply chains are increasing the need for sterilization capacity and aseptic equipment.
See why 7 investors see STERIS as 3% undervalued.
Result: Fair Value of $263.13 (UNDERVALUED)
Still, the STERIS narrative can crack if tariff costs squeeze margins more than expected, or if the North Carolina chemistries project disrupts cash generation.
Find out about the key risks to this STERIS narrative.
Another View: STERIS Through The Market’s Lens
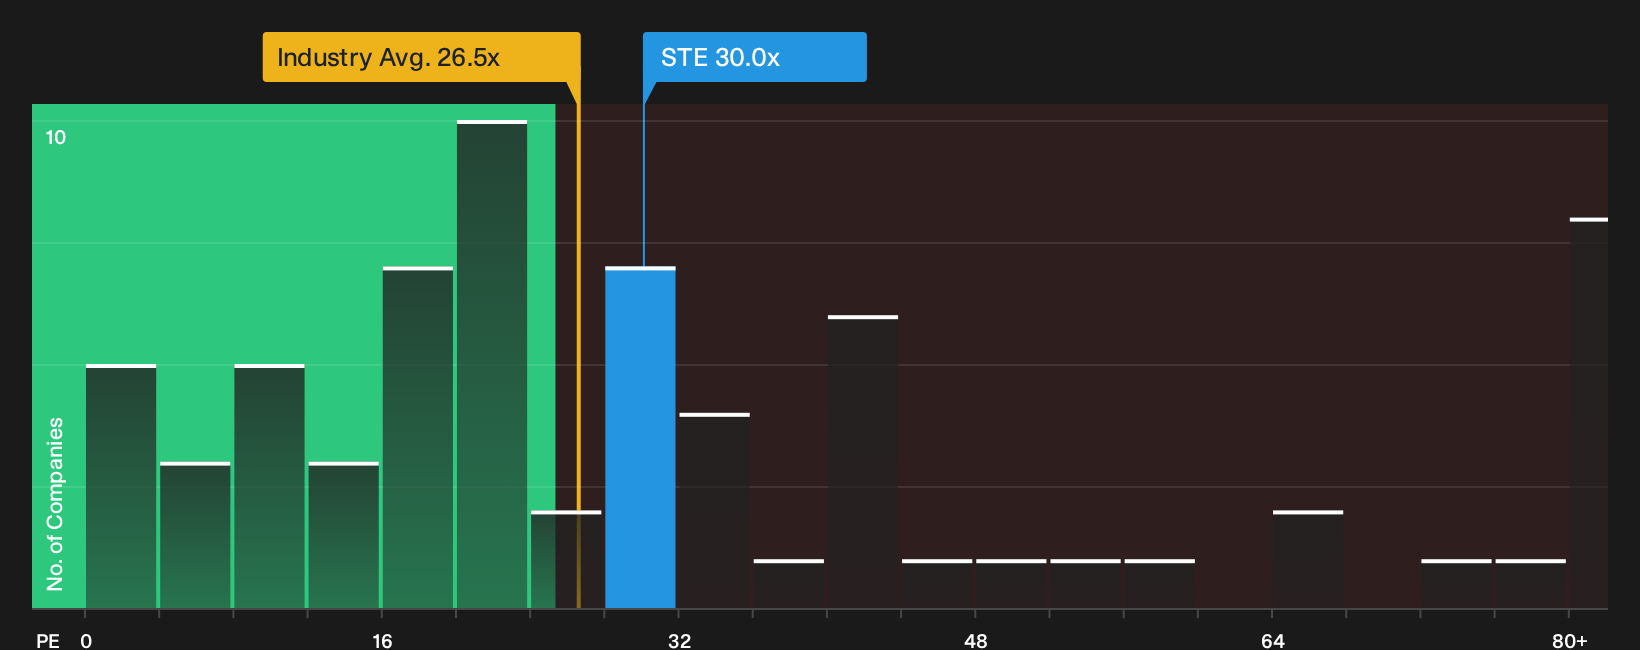
That fair value of $263.13 leans on earnings forecasts and narrative assumptions. The market, though, is currently paying about 30x P/E for STERIS, compared with 26.5x for the wider US Medical Equipment group and an estimated fair ratio of 27.5x. That richer multiple suggests investors already accept some valuation risk. If sentiment cools even slightly, how much of that premium holds up?
See what the numbers say about this price in more detail in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around STERIS is upbeat, but the real edge comes from testing that optimism against the underlying numbers yourself and moving before consensus hardens. To see what optimists are focusing on, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond STERIS?
If STERIS has your attention, do not stop there. Broaden your watchlist with fresh ideas so you are not late to the next opportunity.
- Target resilient compounding potential by scanning a curated 42 high quality undervalued stocks that pair balance sheet strength with compelling valuations.
- Build a smoother ride for your portfolio and focus on capital preservation first by zeroing in on 32 resilient stocks with low risk scores.
- Add punch to your income strategy and hunt for reliable cash payouts using our curated set of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com