


EN
Costco Stock And 2 Consumer Staples Names Facing A Margin Test
Tariffs that pushed prices higher, an election backlash and fresh talk of bigger government have pulled U.S. consumer staples and retailers into the political spotlight. Domestic-oriented brands now sit closer to the fault line where trade policy, labor power and regulation meet your weekly shopping basket. This article unpacks that story and highlights 3 stocks from the screener that, based on the news, could either benefit or face new pressure.
The stocks discussed below are simply a starter set from the idea. The full screen surfaced 11 more U.S.-focused consumer staples and retailers with equally compelling stories tied to domestic sourcing, labor exposure and regulatory risk.
If you want to identify which of these businesses best fits your own thesis, head straight to the U.S. Domestic-Oriented Consumer Staples and Retailers screener to filter, analyze and highlight your highest conviction angles.
Lifeway Foods (LWAY)
Overview: Lifeway Foods produces probiotic cultured dairy products like drinkable kefir and cheeses for North American shoppers, fitting the domestic everyday-staples theme.
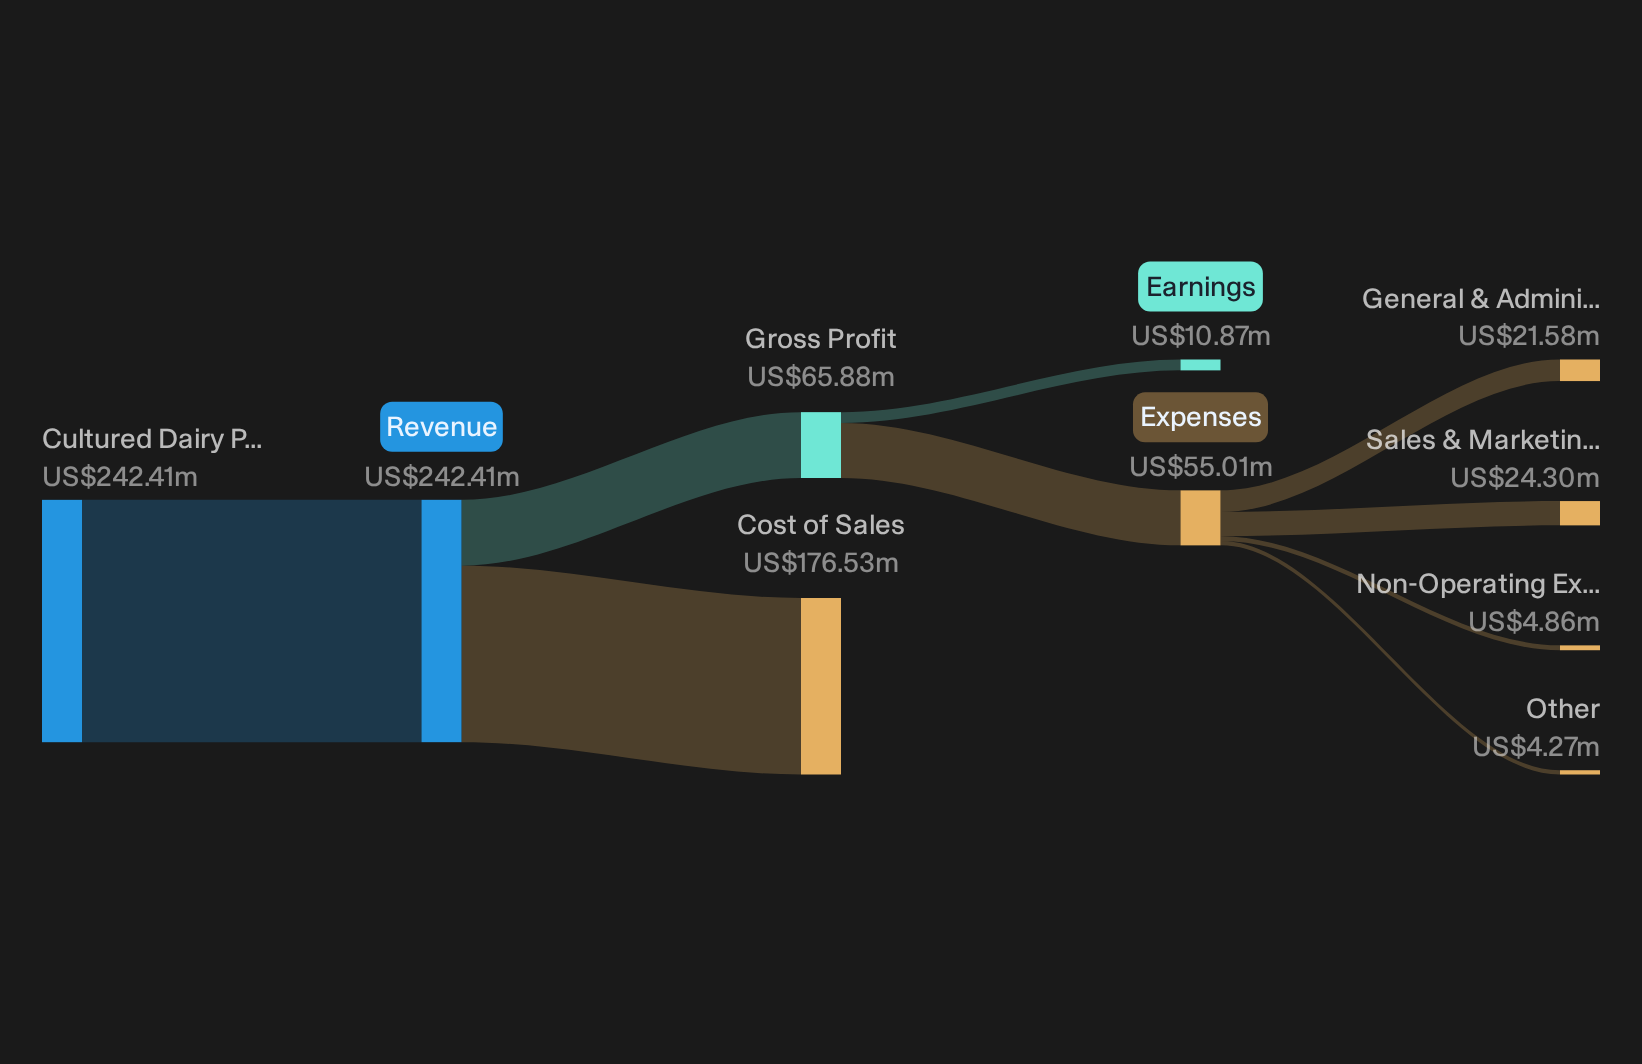
Operations: Lifeway Foods generates about US$242 million in revenue from cultured dairy products, with all reported sales coming from the United States.
Market Cap: US$337 million
For this screener, Lifeway Foods matters because it ties everyday probiotic dairy habits directly to U.S. manufacturing and sourcing, at a time when tariff reversals and heavier regulation could reshape where and how essentials are produced.
"The approximately US$45 million expansion of the Waukesha facility, which management expects to complete in early 2027, targets a doubling of capacity and more than tripling of bottling speeds and can increase operating leverage and net margins as volumes run across the larger footprint."
The real swing factor is how one still-developing cost pressure interacts with that extra volume to either widen or squeeze future profitability.
That cost pressure question is exactly what the full narrative for Lifeway Foods unpacks, showing where Lifeway Foods could see accelerating strength or where margins might quietly stall.
J. M. Smucker (SJM)
Overview: J. M. Smucker makes branded everyday foods, coffee, snacks and pet products for primarily U.S. households, giving the screener another domestically anchored pantry play.
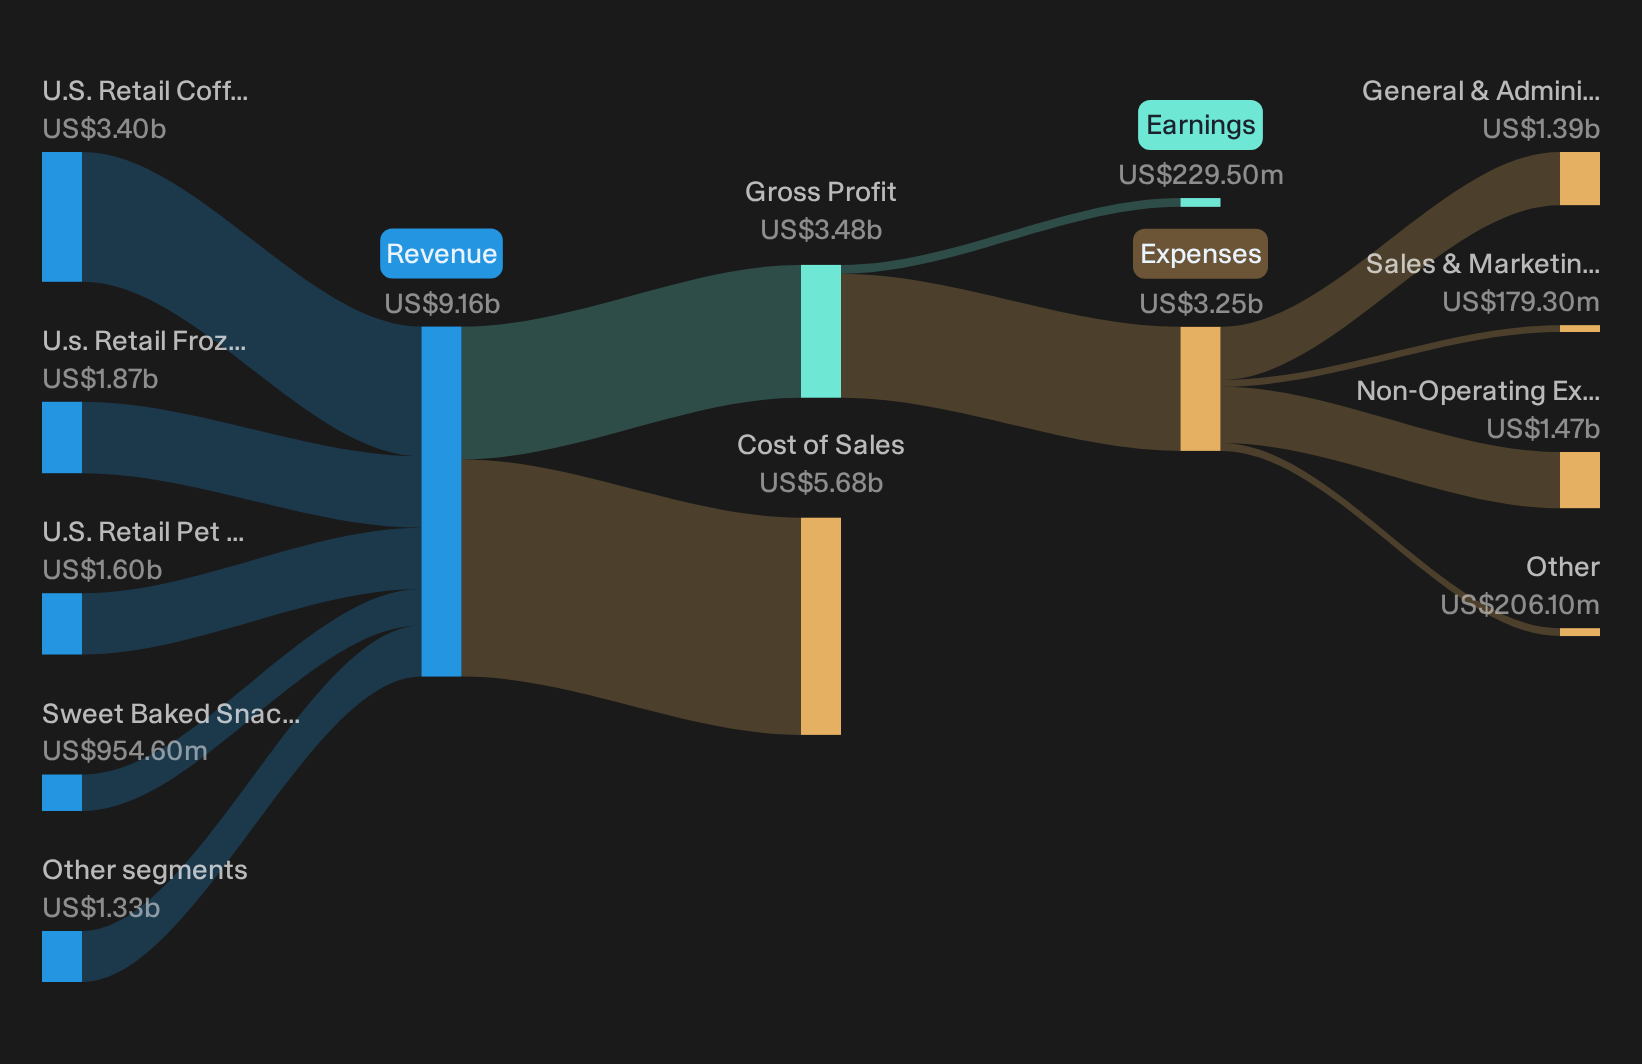
Operations: J. M. Smucker generates about US$3.4b from U.S. Retail Coffee, US$1.9b from Frozen Handheld and Spreads, US$1.6b from U.S. Retail Pet Foods, plus smaller segments, with US$8.7b of its US$9.2b sales coming from the United States.
Market Cap: US$14.1b
J. M. Smucker slots neatly into this domestically oriented staples screen because its coffee, peanut butter, frozen sandwiches and pet treats fill U.S. cupboards and fridges. Its heavy reliance on U.S. production and distribution shapes how trade policy, labor costs and new regulations filter through to household essentials.
"Ongoing expansion of the Uncrustables platform, including record quarterly volume and the move past US$1b in annual net sales, positions J. M. Smucker to keep lifting frozen handheld revenue and support earnings as fixed production costs are spread over higher output."
What really matters for investors now is how one unresolved cost pressure interacts with that volume story to either support or strain future margins.
That margin tension is exactly where the story gets interesting, and the full narrative for J. M. Smucker shows how J. M. Smucker’s volume engine could accelerate or mask brewing risks.
Costco Wholesale (COST)
Overview: Costco Wholesale runs membership-only warehouse clubs that sell bulk groceries, household essentials and basic goods to value-focused shoppers worldwide.
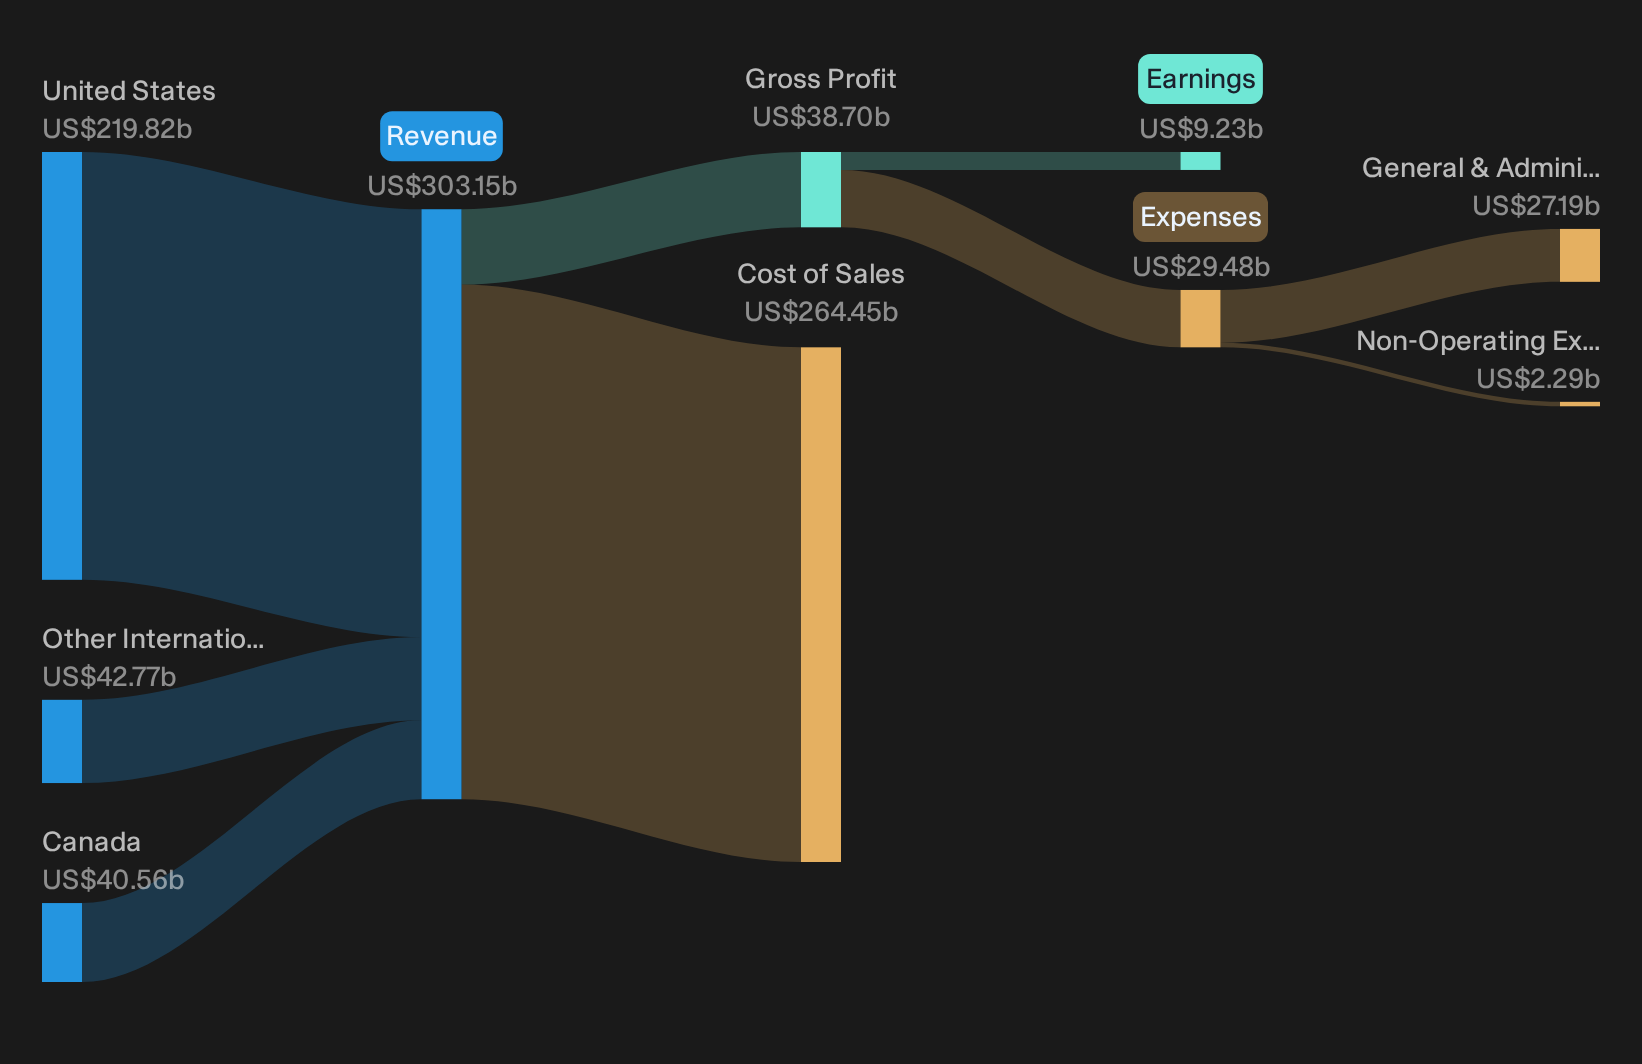
Operations: Costco generates about US$303.2b from membership warehouses, with roughly US$219.8b of sales from the United States and US$83.3b from other regions.
Market Cap: US$463.7b
Costco Wholesale fits this domestic-oriented staples screen because its warehouse model leans heavily on U.S. shoppers who rely on bulk food and household basics, and its scale gives it room to absorb tariff swings while still fighting to keep basket prices sharp.
"The modernization of the ad business and app functionality under Millerchip is a key catalyst for margin expansion in my forecast."
What could really shift the Costco Wholesale story is how one less-obvious pressure shapes the balance between rock-bottom prices and future profitability.
That trade off is exactly what the full narrative for Costco Wholesale unpacks, showing where Costco Wholesale’s pricing power, membership engine and cost pressures may be quietly decoupling.
Curious About What You Might Be Missing?
Fresh ideas move first. By the time the crowd spots a breakout, momentum can be flying or already dropping. Scan these curated lists while it matters and get in early.
- Target dependable portfolio anchors with income potential by running through a curated mix of 6 dividend fortresses before yields compress and attention catches up.
- Hunt for future compounding machines by filtering a carefully assembled 21 high quality undiscovered gems that remains under the radar for now but will not stay quiet forever.
- Position ahead of the AI build out by reviewing a focused group of 53 AI infrastructure stocks while infrastructure spending, demand and capital flows are still forming the early trend.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com