


EN
Jet2 (AIM:JET2) Black Friday Push And Egypt Return Put Valuation Back In Focus
Jet2 (AIM:JET2) has put its 2026 Black Friday sale and the planned return of flights and holidays to Egypt in 2027 at center stage, giving investors fresh clues about demand for its leisure travel offering.
Recent price moves suggest investors are warming to these initiatives, with Jet2’s share price up 4.65% over the past week and 3.13% over the past month. However, a 6.67% decline over 90 days shows that momentum has only recently started to build from a softer patch.
Scan how other travel and leisure stocks are reacting to shifting holiday demand with our curated 5 high quality undiscovered gems collection. These opportunities sit off the usual radar but share Jet2’s consumer theme.
Jet2 trades about 11% below the average analyst target after a recent bounce, yet its own fair value estimate screens at a slight premium to the market. Is that discount a sign of caution or an opportunity that may be mispriced?
Most Popular Narrative: 11% Undervalued
With Jet2 last closing at £14.84 against a narrative fair value of £16.63, the most followed storyline in the market leans toward the current price underrating its long term cash generation potential under a 10.18% discount rate.
Robust cash generation, a conservative balance sheet, and prudent management of debt and liquidity provide the financial flexibility to compound shareholder returns via dividends and buybacks, while also insulating earnings from macroeconomic shocks.
Product diversification, expanding both the range of destinations and holiday options and targeting younger and less affluent demographics without sacrificing quality, broadens Jet2's addressable market and should support stable revenue with a more risk-mitigating customer mix.
See why 39 investors see Jet2 as 11% undervalued.
Result: Fair Value of £16.63 (UNDERVALUED)
Still, the Jet2 story could change quickly if competition in the UK flight market squeezes ticket yields, or if rising fuel and environmental costs pressure margins more than expected.
Find out about the key risks to this Jet2 narrative.
Another View: Jet2 Looks Expensive On Cash Flows
On simple earnings ratios Jet2 looks inexpensive, yet the SWS DCF model tells a very different story. It puts future cash flow value closer to £2.66 per share, well below the current £14.84 price. That gap raises a clear question: Is the profit today masking weaker long term cash economics?
For a closer look at how this cash flow result is built up over time, and what assumptions sit underneath it, review the Look into how the SWS DCF model arrives at its fair value.
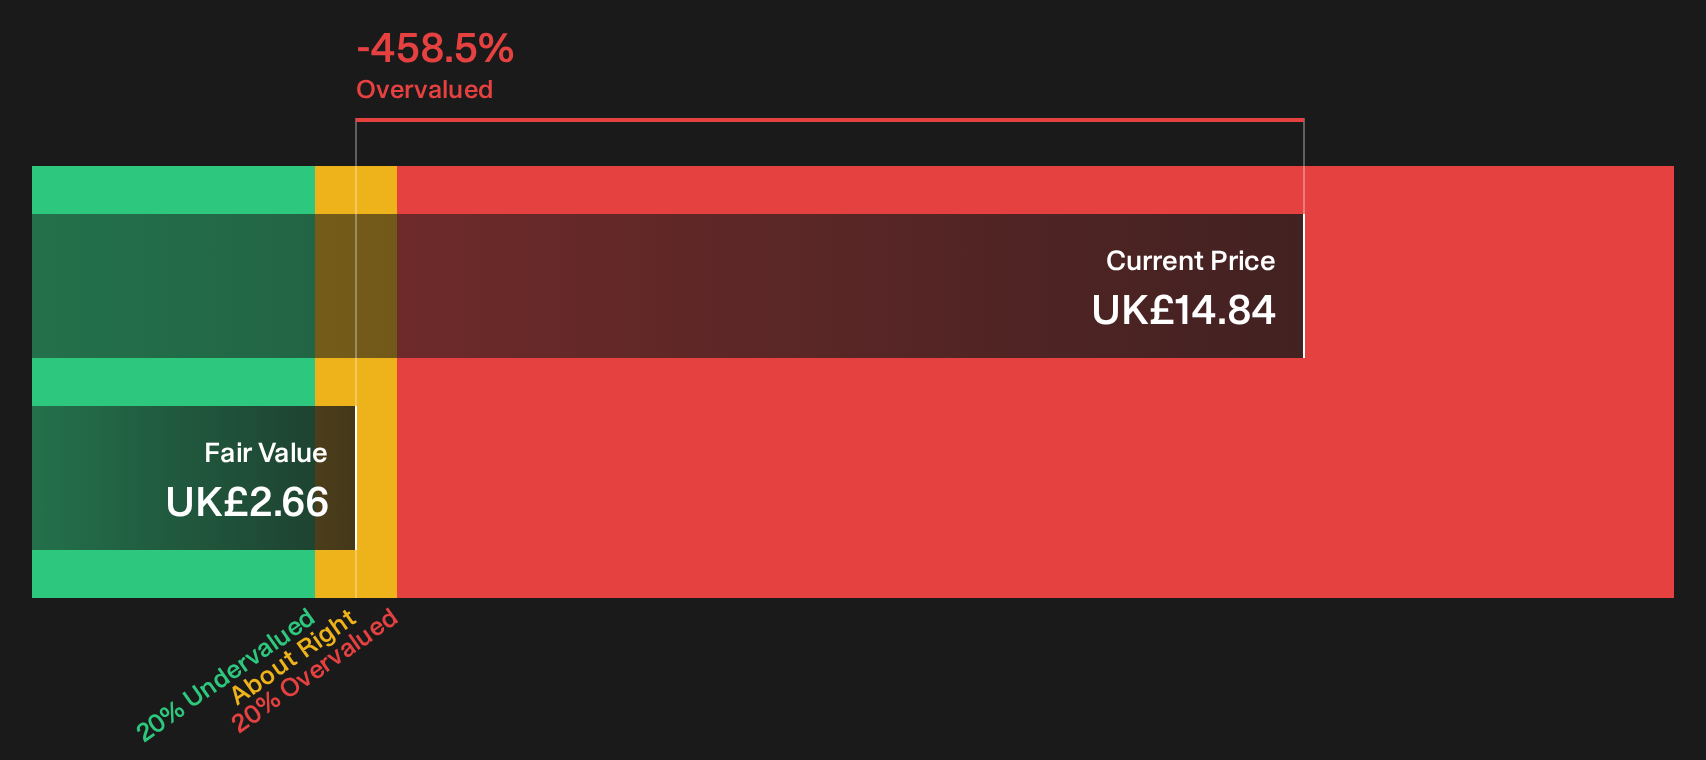
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jet2 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages or a clear setup for patient holders, you do not have to wait for consensus to decide. Act while sentiment is still forming and review the 3 key rewards
Hunting For More Ideas Beyond Jet2?
If Jet2 has sharpened your focus on travel and leisure, do not stop there. Broader ideas can help balance risk and opportunity across your portfolio.
- Target steadier compounding potential by scanning a curated 6 dividend fortresses list designed for investors who care about income resilience as much as price action.
- Upgrade your opportunity set by filtering for quality businesses trading below estimated worth through the focused 15 high quality undervalued stocks.
- Dial back portfolio stress and concentrate on durability by screening companies that pass a resilience check in the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com