


EN
HubSpot (HUBS) Could Be 20% Undervalued As Q3 Beat Meets Softer Outlook
HubSpot (HUBS) is back in focus after its third quarter 2026 update, which paired a detailed earnings release with fresh guidance and a new US$1b share repurchase authorization.
Despite the fresh US$1b buyback plan and Q3 beat, HubSpot’s latest earnings and softer Q4 outlook have been met with a sharp reset in expectations. The share price is down 14.45% over the past week and 46.38% year to date, while the 1-year total shareholder return has fallen 48.10%, pointing to fading momentum as investors reassess growth, AI execution and risk around the new pricing model.
Compare HubSpot’s reset with peers by scanning our hand picked list of 35 high quality undervalued stocks that currently show stronger price momentum and more resilient sentiment around growth expectations.
After a 46% year to date slide in HubSpot, alongside a fresh US$1b buyback and slower Q4 guidance, does the current valuation still compensate you for the execution and growth risks now on the table?
Most Popular Narrative: 20% Undervalued
HubSpot’s most followed narrative pegs fair value at $257.67, above the last close of $204.96. This frames the current share price as a discount that depends heavily on how its AI and platform story plays out.
Rapid adoption and expansion of AI-based functionality such as Customer Agent, Prospecting Agent, and connectors to leading LLMs are driving higher customer engagement, sticky workflows, and early-stage monetization opportunities especially via credit-based AI features, setting the stage for stronger net dollar retention and potentially higher net margins in 2026 and beyond.
See why 68 investors see HubSpot as 20% undervalued.
Analysts behind this fair value use an 8.58% discount rate and build in revenue of $5.0b and earnings of $636.7m by 2029, paired with a 22.3x P/E on those future earnings. That combination underpins the $257.67 figure and implies that today’s price already assumes both meaningful profit growth and a step up in long term margins.
The same framework also assumes earnings growth of 49.5% per year over the next three years and a future return on equity of 38.2%. Those are ambitious inputs, so your own view on HubSpot’s ability to scale AI monetization, manage competition and execute internationally becomes crucial if you are using this narrative as an anchor for any decision.
Result: Fair Value of $257.67 (UNDERVALUED)
Still, if HubSpot’s AI agents or credit based pricing struggle to gain traction, or international expansion slows, that 20% “undervaluation” case could unwind quickly.
Find out about the key risks to this HubSpot narrative.
Another View: HubSpot’s Price Tag Looks Heavy
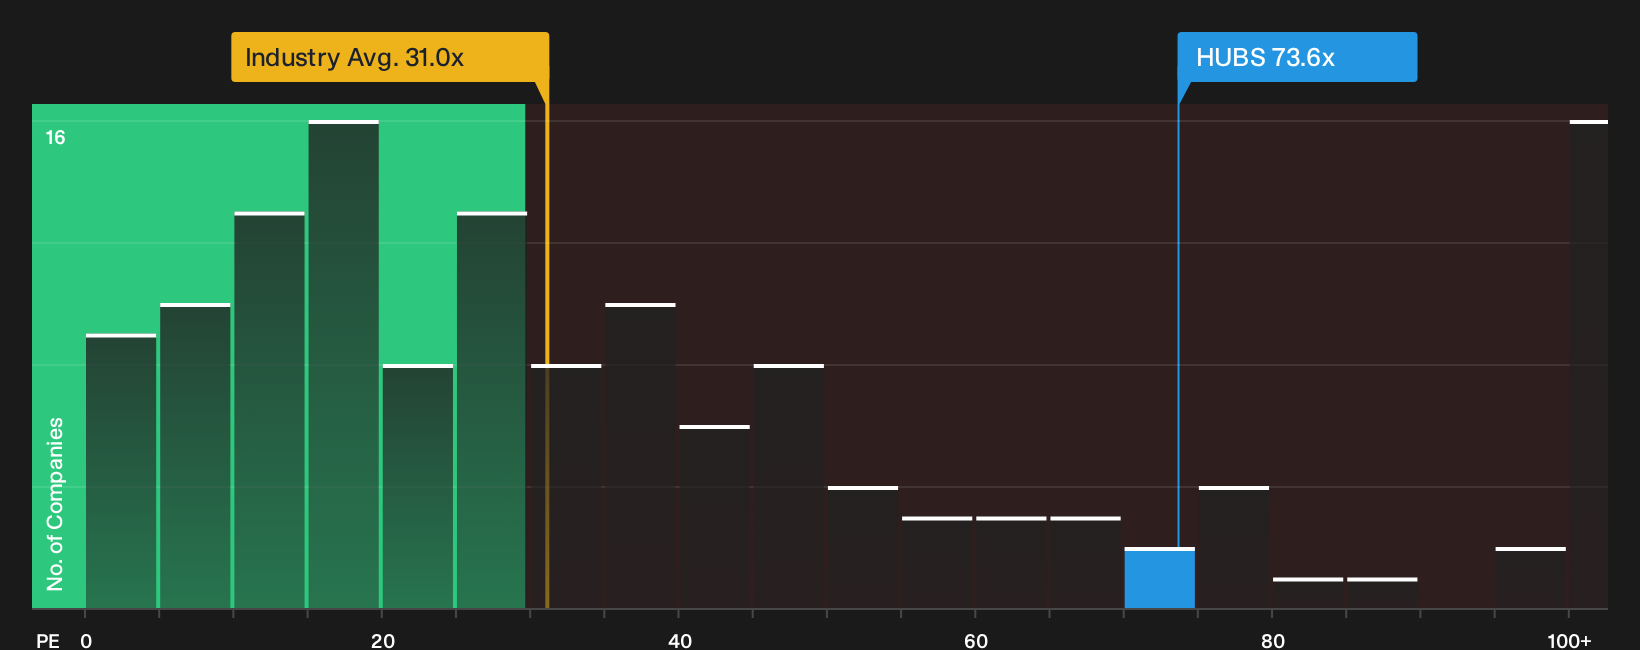
The earlier fair value narrative paints HubSpot as 20% undervalued. A simple earnings multiple tells a very different story. The stock trades on a P/E of 73.6x against a US Software industry average of 31x and a fair ratio of 66.1x, which signals a rich entry point if that gap closes.
If the market leans more on this earnings yardstick than on growth forecasts, the question becomes how comfortable you are paying a premium today for returns that still rely heavily on execution in AI and international expansion. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these rarely resolve on their own, so move quickly to review the underlying data and pressure test your stance on HubSpot. To weigh the upside against the concerns in detail, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond HubSpot?
If HubSpot has you rethinking your watchlist, this is the moment to broaden your field of vision and line up a few fresh contenders.
- Spot underpriced quality by scanning a focused group of 35 high quality undervalued stocks that pair sturdier fundamentals with more constructive sentiment.
- Prioritize staying power and sleep better at night by running through a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- Get ahead of the crowd by reviewing a curated pool of 19 high quality undiscovered gems before they end up on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com