


EN
Shareholder Payout Plan Could Reshape The Case For Woodside Energy Shares
- Woodside Energy Group has outlined a new shareholder distribution framework tied to adjusted operating cash flow, detailed a multi hundred million dollar annual cost reduction plan from 2028, and updated timelines for major LNG and oil projects including Scarborough, Trion, and Louisiana LNG.
- The shift toward a cash flow linked payout policy, combined with organisational simplification and project updates, reflects a tighter focus on capital efficiency and operating discipline at Woodside Energy Group.
- This analysis examines how Woodside Energy's revised cash flow based shareholder distribution policy may reshape the existing investment narrative around LNG growth.
Scan beyond Woodside Energy Group and see how other LNG focused producers are repositioning their cash flows and project pipelines with our hand picked 41 power grid technology and infrastructure stocks
Woodside Energy Group Investment Narrative Recap
To own Woodside Energy Group, you need to believe that its LNG led portfolio can convert large, long life projects into steady operating cash flow, while cost cuts and portfolio pruning keep margins supported. The short term hinge remains project execution at Scarborough and Louisiana LNG, where construction progress and start up timing carry real weight for future output and cash generation.
The biggest risk right now is operational underperformance or further delays across key assets, such as a tighter Scarborough window or recurring Beaumont and FPSO issues, which could drag on revenue and EBITDA. The latest cash flow linked payout framework does not change that core execution risk, although it may sharpen management focus on operating discipline.
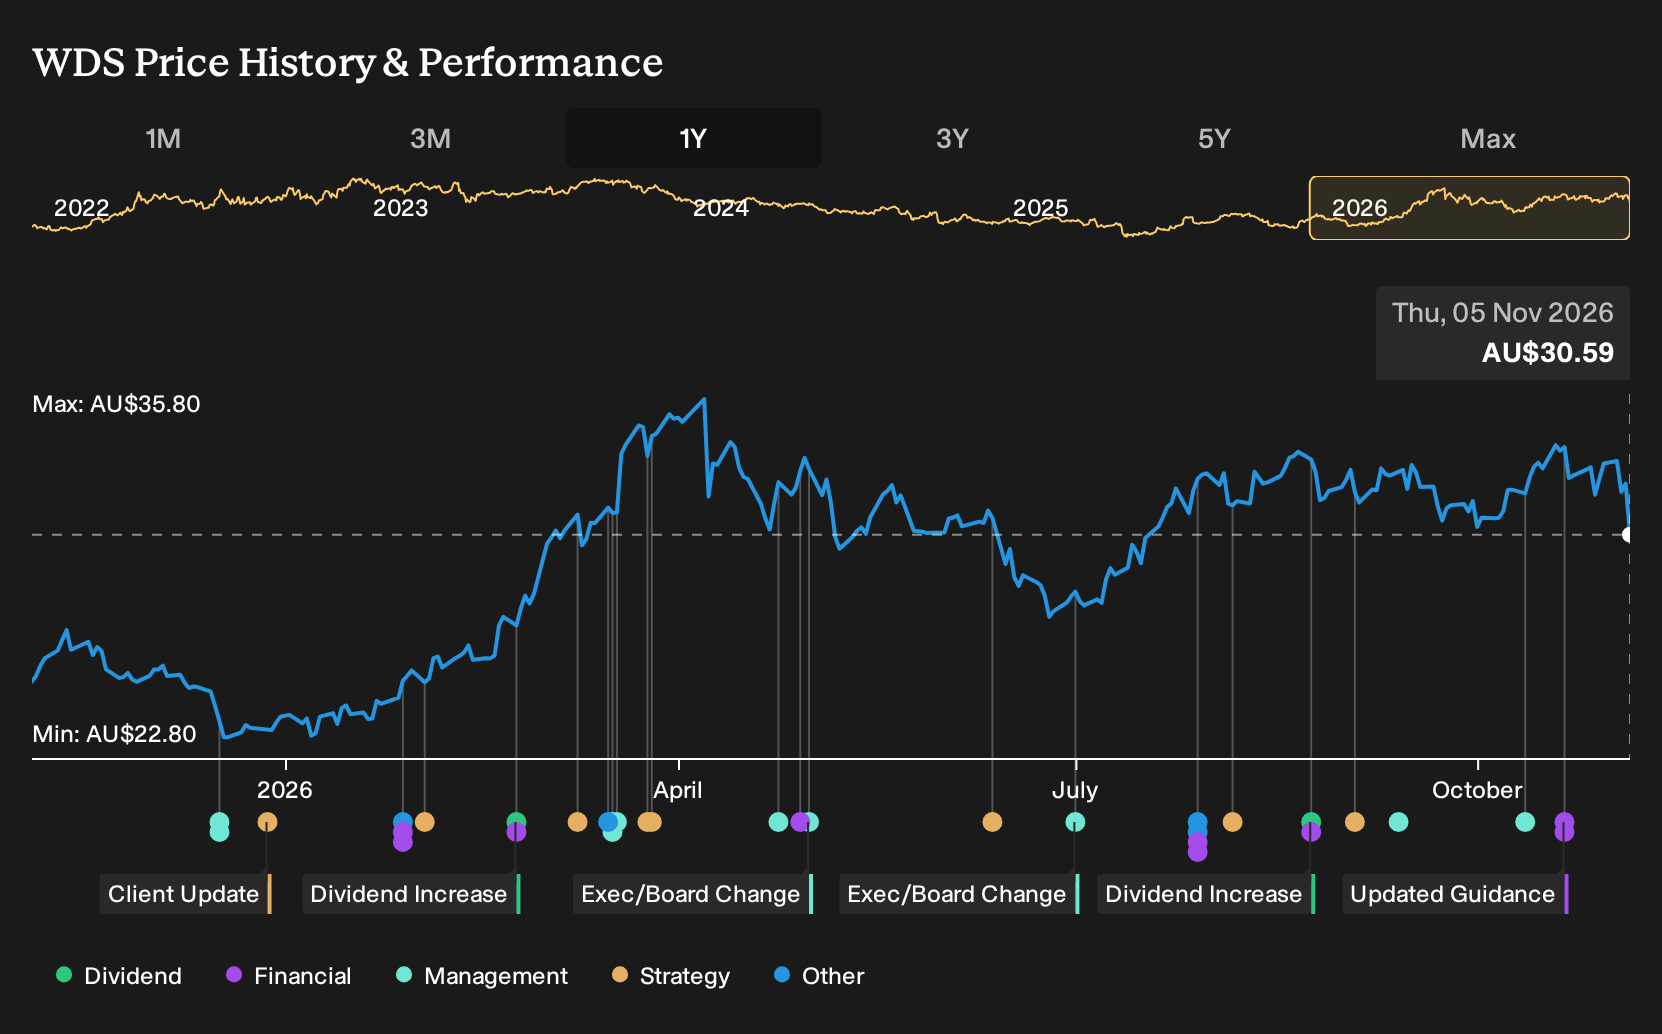
The most relevant recent shift for this QatarEnergy contract backdrop is Woodside Energy Group's new shareholder distribution policy tied to adjusted operating cash flow. Management is signalling that as Scarborough, Trion and Louisiana LNG move through construction and into production, a defined slice of cash generation is earmarked for investors through a mix of base dividends and variable distributions.
For you, the interest is less about headline payout percentages and more about what this implies for project delivery and risk. A cash flow based framework puts a spotlight on uptime, cost control and timely ramp up at core LNG hubs. If operational issues at assets like Okha FPSO or Beaumont persist or widen, that could reduce headroom for both distributions and future project spending.
What The Consensus Growth Story Implies For Woodside Energy Group
Analysts are sketching a Woodside Energy Group profile built around moderate top line expansion and slightly slimmer profit margins, rather than a high growth LNG surge. Revenue is projected to rise by 5.1% each year over the next three years while profit margins ease from 22.2% today to 20.4% by 2029. That mix points to a business where new LNG capacity and cost cuts have to work hard just to offset softer margins and keep earnings moving in the right direction.
On the earnings line, the consensus view pegs profit at about $3.3b by 2029, compared with $3.1b today. That is an increase of roughly $0.2b over the next few years, not a step change. For you as a holder or potential investor, the message is simple. The market is not baking in a dramatic earnings surge from Scarborough, Trion or Louisiana LNG at this stage. It is assuming that incremental volume growth and a cleaner portfolio are enough to edge earnings higher even as unit profitability tightens slightly.
The P/E assumptions reinforce how much of the Woodside Energy Group LNG build out is already embedded in expectations. To line up with the current consensus price target, analysts assume the stock trades at 17.1x those 2029 earnings compared with about 14.0x today and roughly 15.6x for the broader Australian oil and gas peer group. That kind of multiple expansion would usually require either very strong confidence in long term cash generation, lower perceived risk around project delivery, or both. It also means any disappointment around project timing or uptime could influence how quickly the market is willing to pay up for those future earnings.
Underpinning all of this is a discount rate assumption of about 7.2% used to bring those future cash flows back to today. That rate effectively captures what analysts see as the risk profile across LNG growth, cost reduction and policy exposure. If your own view of project risk or commodity volatility differs meaningfully from that, your assessment of fair value for Woodside Energy Group could diverge from the current consensus, even if you accept the same revenue and earnings trajectory.
Woodside Energy Group's narrative projects $16.1b revenue and $3.3b earnings by 2029. This requires 5.1% yearly revenue growth and an earnings increase of about $0.2b from $3.1b today.
Uncover why Woodside Energy Group's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts see the QatarEnergy contract backdrop very differently. They focus on Woodside Energy Group’s ability to turn its LNG and oil project queue plus the US$350m annual cost cuts into about US$18.1b of revenue and US$4.0b of earnings by 2029. Those projections pre date this news, so you may want to test how today’s developments could shift that optimistic script.
Explore 5 other Woodside Energy Group fair value estimates, including one that suggests there could be as much as 88% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Woodside Energy Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Woodside Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodside Energy Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Woodside Energy Group?
Once you have a view on Woodside Energy Group, it can help to widen the lens and compare it with other opportunities that match your risk tolerance and income needs. The Simply Wall St Screener lets you filter for different profiles so you are not relying on a single story or sector.
- Focus on businesses that pair quality with attractive pricing by scanning a curated 5 high quality undervalued stocks that may offer a stronger balance between fundamentals and expectations.
- If capital protection sits higher on your agenda, you might prefer steadier profiles identified through a 6 resilient stocks with low risk scores that screens for companies with more resilient risk scores.
- For those hunting for less crowded ideas with robust metrics, there is a 14 high quality undiscovered gems that filters for under the radar stocks displaying strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com