


EN
Fortinet (FTNT) On Raised 2026 Outlook And New AI Products Looks Fully Valued
Fortinet (FTNT) just posted third quarter results with revenue of US$2,078.4 million and net income of US$635.5 million, and lifted its 2026 revenue outlook while rolling out new AI focused security products.
Fortinet’s recent run of AI focused product launches and upgraded 2026 revenue guidance has arrived amid a sharp reset in the share price. The 30 day share price return is down 32.35% and the 90 day share price return is down 18.95%, even though the year to date share price return is up 66.14% and the 3 year total shareholder return is up 160.5%. This points to long term momentum colliding with more cautious sentiment after a strong multi year rally.
Compare Fortinet's AI driven security story with other potential beneficiaries of the same theme by scanning the hand picked 53 AI infrastructure stocks.
The share price has reset hard while Fortinet still trades below both analyst targets and one intrinsic value estimate. Does that gap signal mispricing, or is it a fair response to the new risk profile?
Most Popular Narrative: 3.1% Overvalued
Fortinet closed at $129.39 while the most followed narrative pegs fair value at $125.56. The stock is framed as slightly ahead of that estimate rather than deeply mispriced.
Fortinet’s current valuation prices in a lot of future perfection, making it an expensive stock by traditional metrics. As of mid-July 2026, the stock trades at a Price-to-Earnings (P/E) ratio of roughly 60x, which is a significant premium compared to the broader market and well above its recent 2024 and 2025 levels. Its Price-to-Sales (P/S) ratio tells a similar story, sitting in a range of about 16x to 18x. This means investors are paying a steep multiple for every dollar of revenue the company generates. A P/E over 60 can leave very little room for error if macroeconomic conditions or spending on data centers change.
See why 17 investors see Fortinet as 3% overvalued.
Result: Fair Value of $125.56 (OVERVALUED)
Still, Fortinet’s premium P/E and reliance on AI data center demand leave the story exposed if security spending or enthusiasm for the theme cools suddenly.
Find out about the key risks to this Fortinet narrative.
Another View On Fortinet’s Value
The narrative crowd sees Fortinet as 3.1% overvalued at $129.39 versus a fair value of $125.56. The SWS DCF model lands in a different place, with an intrinsic value of $145.99, which implies the stock trades at an 11.4% discount. Is that a genuine margin of safety or just generous assumptions meeting a hot AI story?
Look into how the SWS DCF model arrives at its fair value.
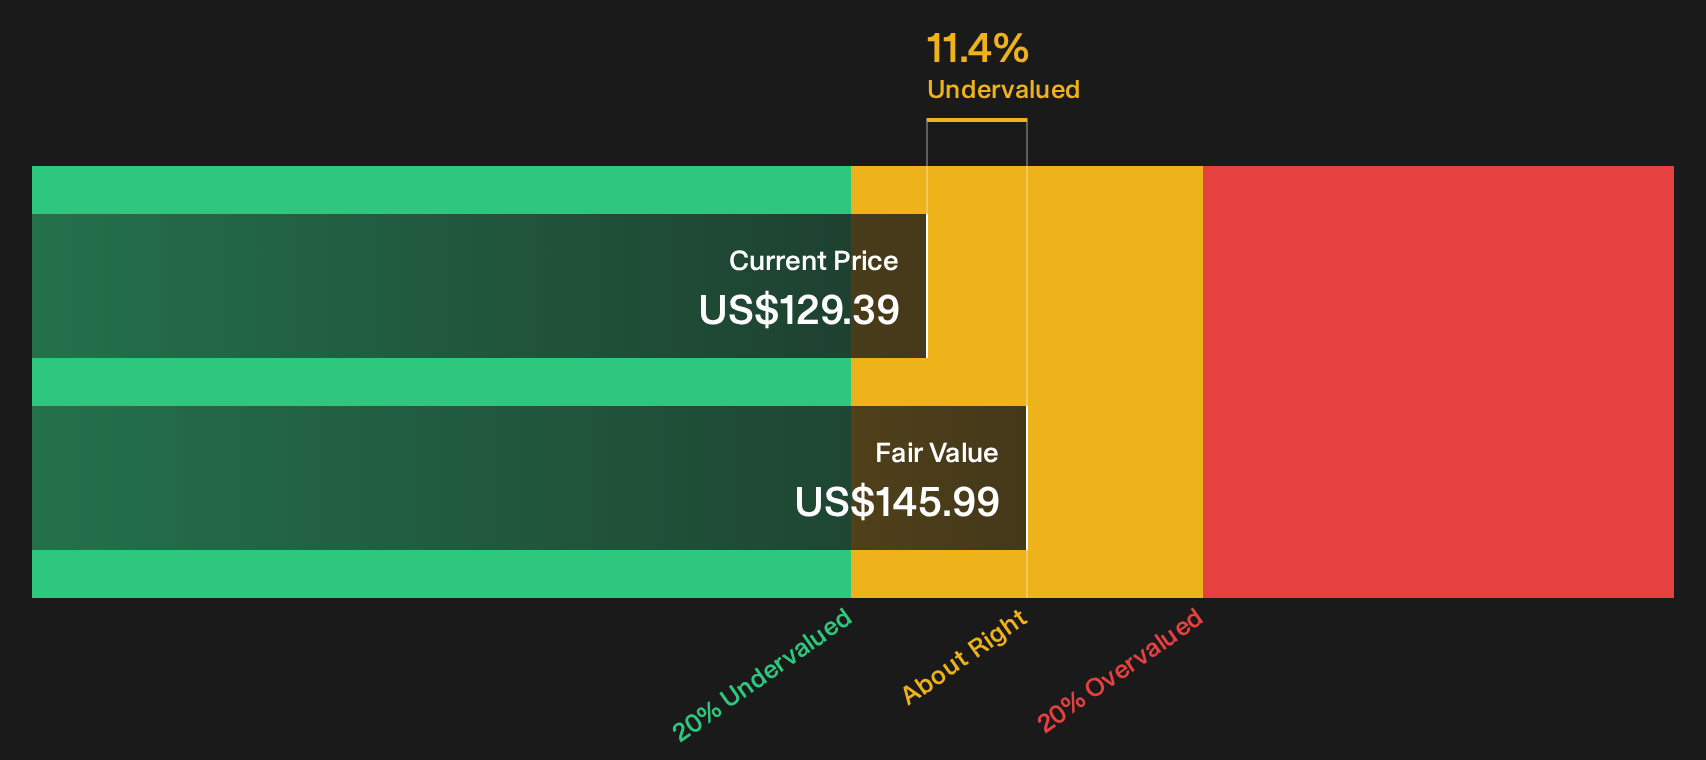
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fortinet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Fortinet is split, which is exactly when fresh eyes matter most. Move quickly, review the data, and weigh the 3 key rewards.
Looking for more investment ideas beyond Fortinet?
If Fortinet has sharpened your interest in cybersecurity and AI, you may want to expand your watchlist with a few targeted sets of stocks that match different goals and risk levels.
- Focus on resilience first and scan for 31 resilient stocks with low risk scores that aim to keep volatility in check while still giving your capital room to work.
- Look for quality at a discount and review the 35 high quality undervalued stocks that combine stronger fundamentals with prices that have not fully caught up.
- Prioritise financial strength and filter for companies on the list of solid balance sheet and fundamentals (24 results) that may be better placed to withstand shocks and fund their operations and development plans.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com