


EN
Hyster-Yale Materials Handling (NYSE:HY) reports sales below analyst estimates in Q3 2026 earnings
Lift truck and material handling solutions manufacturer Hyster-Yale Materials Handling (NYSE:HY) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 15.5% year on year to $827.4 million. Its non-GAAP loss of $0.77 per share was 92.5% below analysts’ consensus estimates.
For more on Hyster-Yale Materials Handling, read our free full research report.
Hyster-Yale Materials Handling (HY) Q3 2026 highlights:
- Revenue $827.4 million vs S&P analysts’ consensus estimates of $926.5 million (15.5% year-on-year decline, 10.7% miss)
- Adjusted EPS -$0.77 vs S&P analysts’ consensus estimates of -$0.40 (92.5% miss)
- Operating margin -1.1%, down from 0.2% in the same quarter last year
- Free cash flow margin 3.2%, similar to the same quarter last year
- Market capitalization $538.3 million
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Hyster-Yale Materials Handling’s revenue grew at a sluggish 2.5% compounded annual growth rate over the last five years, falling short of our benchmarks.
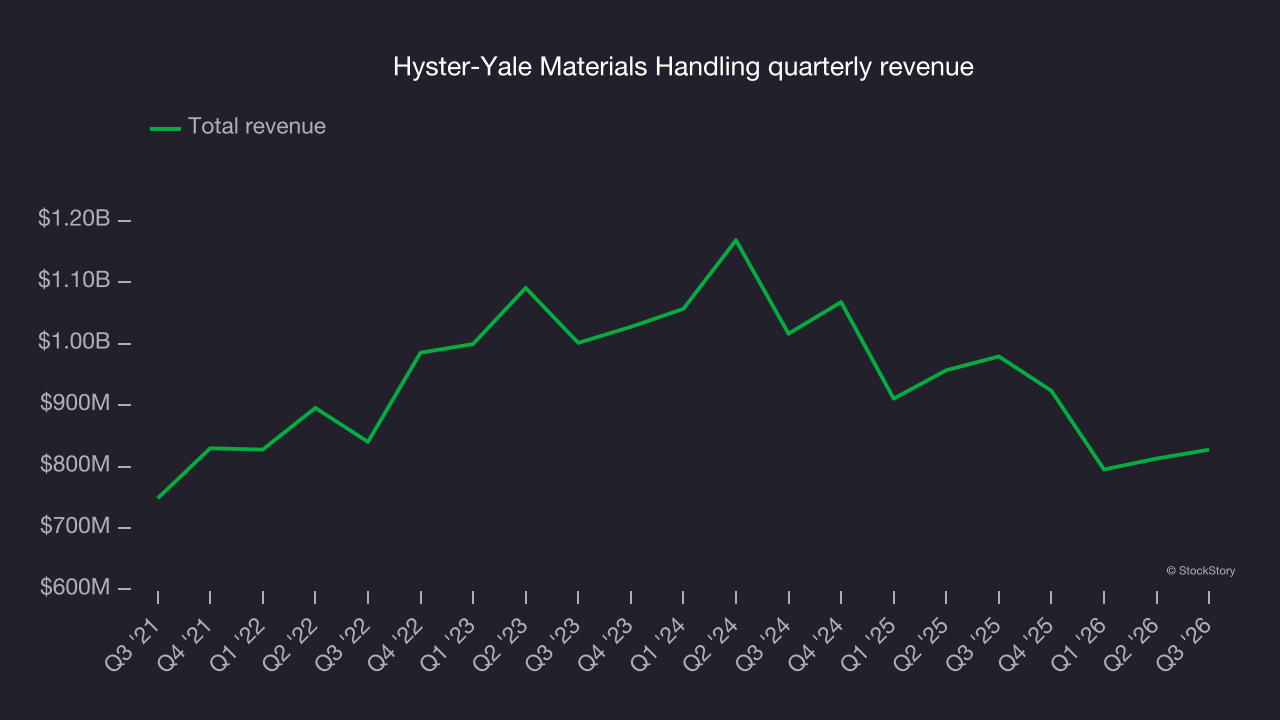
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Hyster-Yale Materials Handling’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 11.3% annually. 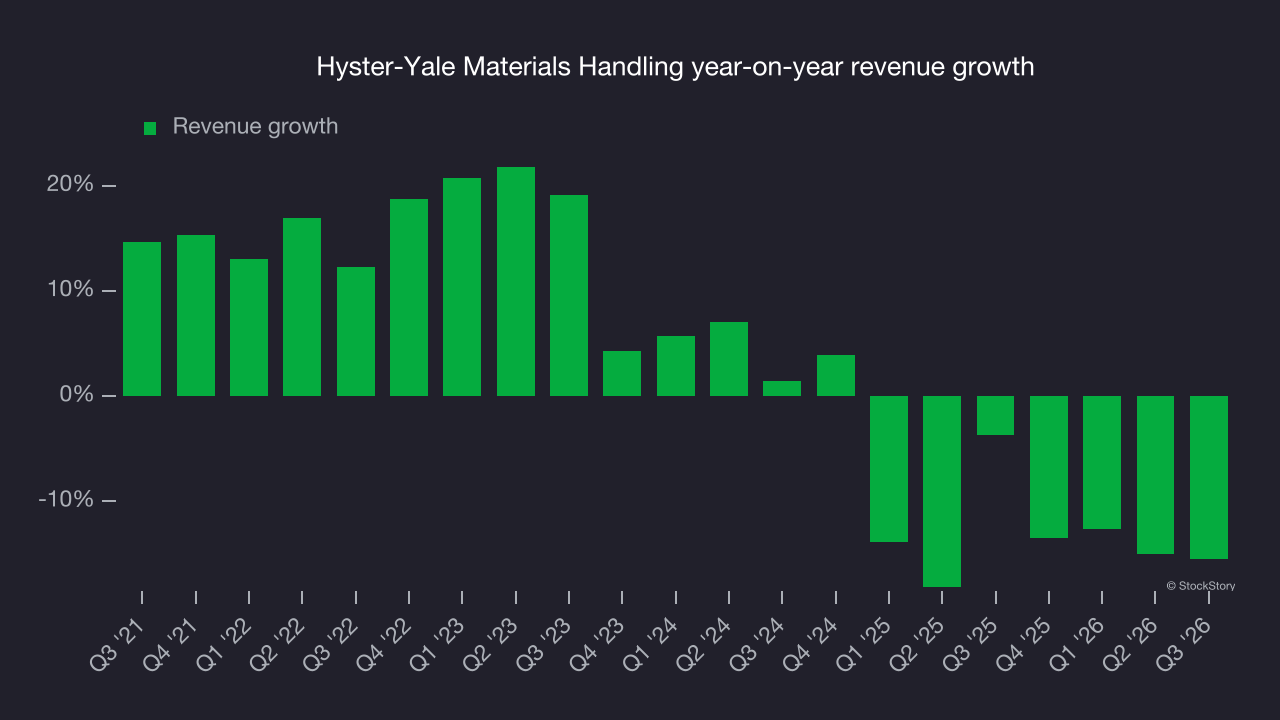
This quarter, Hyster-Yale Materials Handling missed Wall Street’s consensus estimates and reported an uninspiring 15.5% year-on-year revenue decline, generating $827.4 million of revenue.
Looking ahead, sell-side analysts expect revenue to grow 10.9% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection suggests its newer products and services will fuel better top-line performance.
Operating margin
Hyster-Yale Materials Handling’s operating margin has generally stayed the same over the last 12 months, averaging 1.5% over the last five years. This profitability was inadequate for an industrials business and was caused by its suboptimal cost structure and low gross margin.
Analyzing the trend in its profitability, Hyster-Yale Materials Handling’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
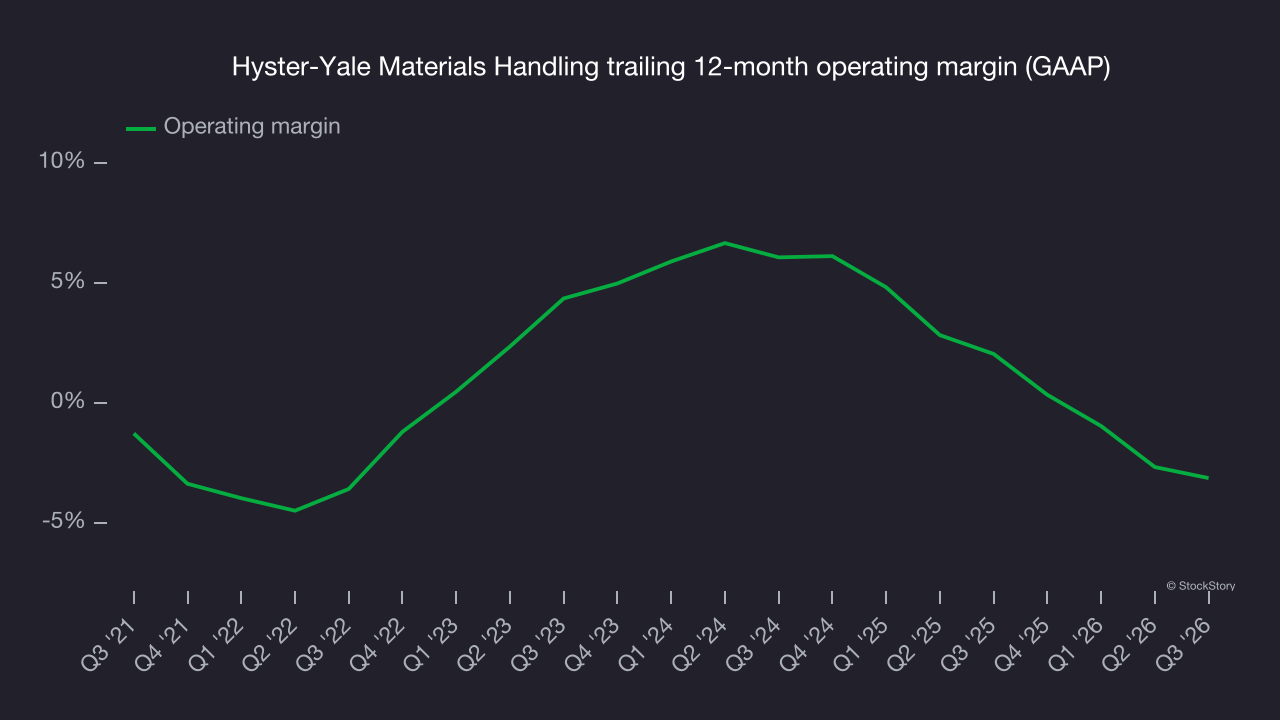
This quarter, Hyster-Yale Materials Handling generated an operating margin of negative 1.1%, down 1.3 percentage points year on year. Its operating margin decreased more than its gross margin, suggesting it was less efficient as expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Hyster-Yale Materials Handling’s earnings losses deepened over the last five years as its EPS dropped 89.1% annually. Falling EPS warrants caution, as diminishing earnings could imply changing secular trends and preferences. If conditions shift unexpectedly, Hyster-Yale Materials Handling’s low margin of safety could leave its stock price susceptible to large declines.
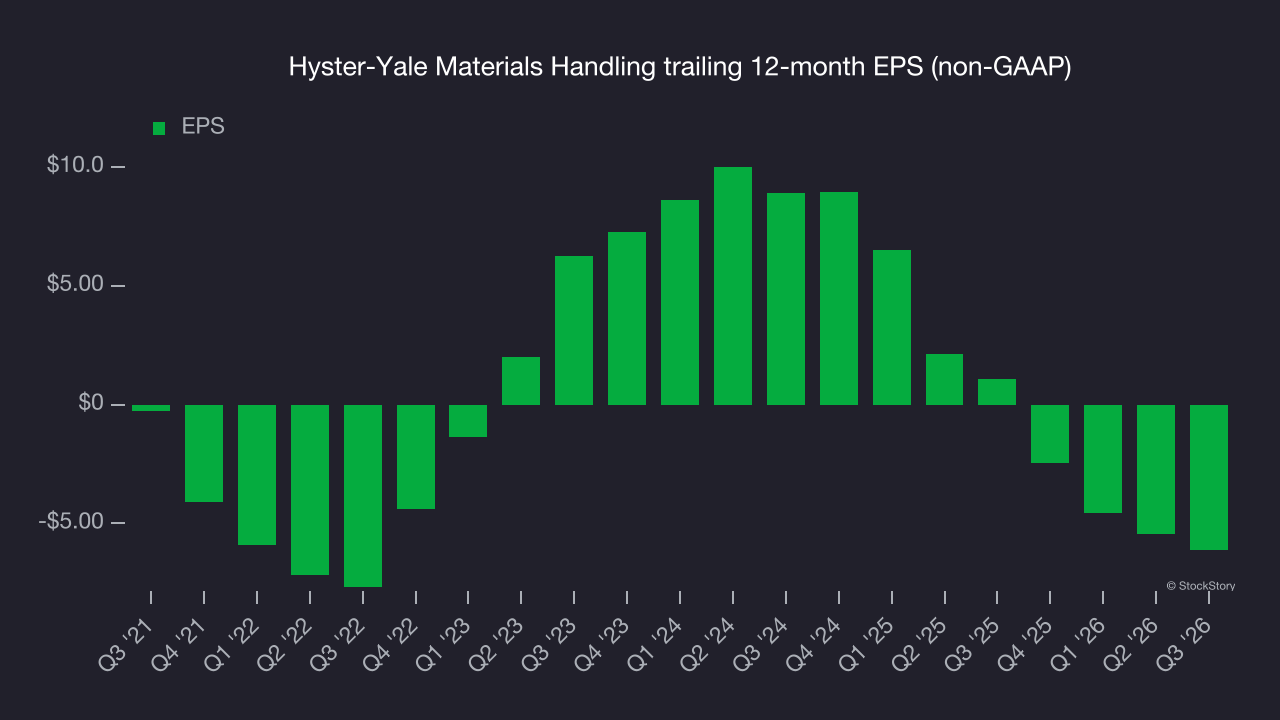
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
Hyster-Yale Materials Handling’s EPS declined by more than its revenue over the last two years, dropping 63.9%. This indicates the company struggled to adjust to shrinking demand.
A closer look at Hyster-Yale Materials Handling’s earnings can help explain its performance. Hyster-Yale Materials Handling’s operating margin has declined over the last two years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Hyster-Yale Materials Handling reported adjusted EPS of negative $0.77, down from negative $0.09 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects a recovery. Analysts forecast Hyster-Yale Materials Handling’s full-year EPS will turn positive, moving from negative $6.11 to positive $1.31, according to S&P.
Key takeaways from Hyster-Yale Materials Handling’s Q3 results
Hyster-Yale Materials Handling’s quarter offered few positives: revenue missed Wall Street’s consensus estimates, and EPS also fell short. These results could have been better. Shares edged lower 1.4% to $26.75 immediately after the report.
Hyster-Yale Materials Handling’s latest earnings report disappointed. One quarter doesn’t define a company’s quality when assessing whether the stock is a buy at the current price. The latest results matter, but longer-term business quality and valuation are more important to that decision. For more on Hyster-Yale Materials Handling, read our free full research report here.