


EN
What Cordero Permits Mean For Discovery Mining Stock
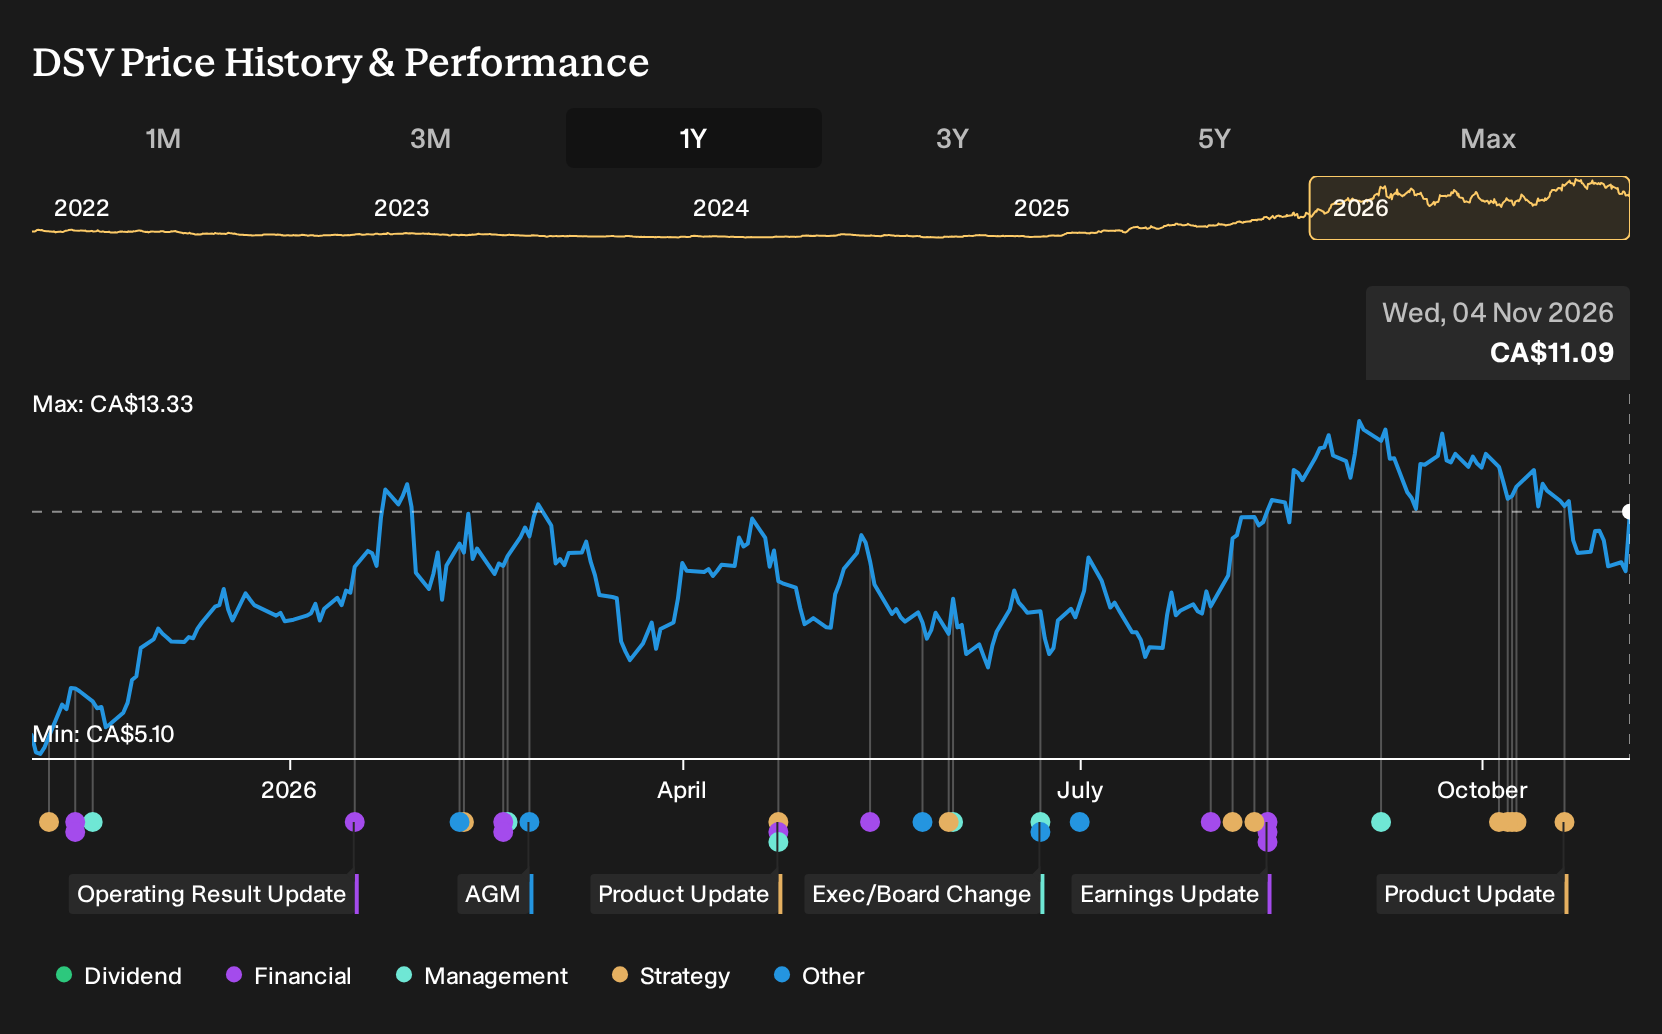
- Discovery Mining recently secured new permits for the Cordero project and outlined planned gold production at the Porcupine Complex, signaling clearer development paths for both assets.
- The pairing of fresh Cordero approvals with Porcupine production plans highlights how Discovery Mining is attempting to convert project optionality into potential operating cash flows.
- This article examines how Discovery Mining's investment narrative is being reshaped by the new Cordero permits and the planned Porcupine output.
See how Discovery Mining compares with other metals producers turning project pipelines into potential cash flow by reviewing the hand picked 34 elite gold producer stocks.
Discovery Mining Investment Narrative Recap
To own Discovery Mining today, you need to be comfortable with a story that ties Porcupine cash generation to long life optionality at Cordero. The recent permits in Mexico and clearer Porcupine production plans give more visibility on where future tonnes and ounces could come from, even if actual timing and scale still need to be proven in operations.
In the near term, the key swing factor is how efficiently Porcupine runs while capital is going into mills, fleets and tailings. The biggest risk is that heavy spend across Porcupine and Cordero meets weaker gold or silver prices, which could squeeze free cash flow and make it harder to fund the exploration and expansion program already on the table.
The new Cordero approvals look most relevant because they directly tackle one of the most visible execution risks in the Discovery Mining story. Environmental permits and land use costs at Cordero were flagged as potential pressure points. Progress here reduces uncertainty around access to the orebody and moves the Mexican asset closer to a potential construction decision.
For catalysts, investors are now watching how quickly those Cordero permits translate into on the ground work and updated capital estimates, alongside how Porcupine output tracks against the fresh plans. The upside case leans on turning that project pipeline into reliable production, while the risk case hinges on cost creep, slower mill upgrades and prolonged sensitivity to metal prices.
Discovery Mining's current analyst narrative points to revenue of $1.7b and earnings of $332.8 million by 2029, built on an assumed 14.8% yearly revenue growth rate and an earnings increase of about $91 million from $241.6 million today.
Uncover why Discovery Mining's fair value indicates a 39% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Discovery Mining focuses on the more aggressive Kidd Met expansion story, where bullish analysts previously pencilled in $2.6b of 2029 revenue and $694.7 million of earnings. You can see how that much more optimistic path might shift again once the new Cordero permits and Porcupine plans are fully digested.
Explore 6 other Discovery Mining fair value estimates, including one that suggests as much as 531% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Discovery Mining research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Discovery Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Discovery Mining's overall financial health at a glance.
Looking for more Discovery Mining style investment ideas?
If the Discovery Mining story has sharpened your thinking on risk, reward and project pipelines, it can help to line it up against other potential opportunities using a structured stock search rather than instincts alone.
- If you want potential mispriced opportunities with solid fundamentals, start by scanning a curated 5 high quality undervalued stocks that filters for quality and price together.
- For investors who care most about resilience and balance sheet strength, narrow your universe to a list of solid balance sheet and fundamentals (6 results) so you are focusing on financially sturdier businesses first.
- If you prefer ideas that are less crowded and potentially overlooked, cast a wider net across a 8 high quality undiscovered gems and see which stories deserve a closer look next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com