


EN
Is Amcor (AMCR) Still Undervalued As Sales Beat But EPS Guidance Was Trimmed?
Amcor (NYSE:AMCR) just delivered a mixed quarterly update that combined higher sales, softer earnings per share, trimmed guidance, and a slightly higher dividend. For investors, that blend of signals raises fresh questions about risk and reward.
The quarterly update has landed against a backdrop of improving momentum in Amcor’s shares, with a 1 month share price return of 16.03% and a 7 day gain of 6.22%. The 1 year total shareholder return of 27.51% points to stronger long run rewards as investors reassess growth potential and dividend income against the trimmed earnings outlook.
Scan how Amcor’s combination of rising sales, tighter margins, and a higher dividend compares with other packaging and materials companies in the 35 high quality undervalued stocks.
After a 16% jump in a month and a trimmed earnings outlook, Amcor now sits in an awkward middle ground. Does that mix of momentum and caution still offer value, or reward investors who wait for a cheaper entry?
Most Popular Narrative: 3% Undervalued
Amcor’s most followed valuation storyline points to a fair value of about $50.18, only modestly above the latest $48.50 close. This view puts more weight on cash flows and margins than on the recent share price run.
The plan to recover more than US$500 million of working capital over the next 12 months and to use a portion of an expected US$2.5b of free cash flow in the following 12 month period for roughly US$1b of debt reduction supports lower interest expense and more flexibility for earnings accretive capital allocation.
See why 43 investors see Amcor as 3% undervalued.
Result: Fair Value of $50.18 (UNDERVALUED)
Still, if organic volumes stay weak or Berry integration synergies slip behind the US$650m target, the current Amcor narrative could quickly look stretched.
Find out about the key risks to this Amcor narrative.
Another View: Amcor Looks Expensive On Earnings
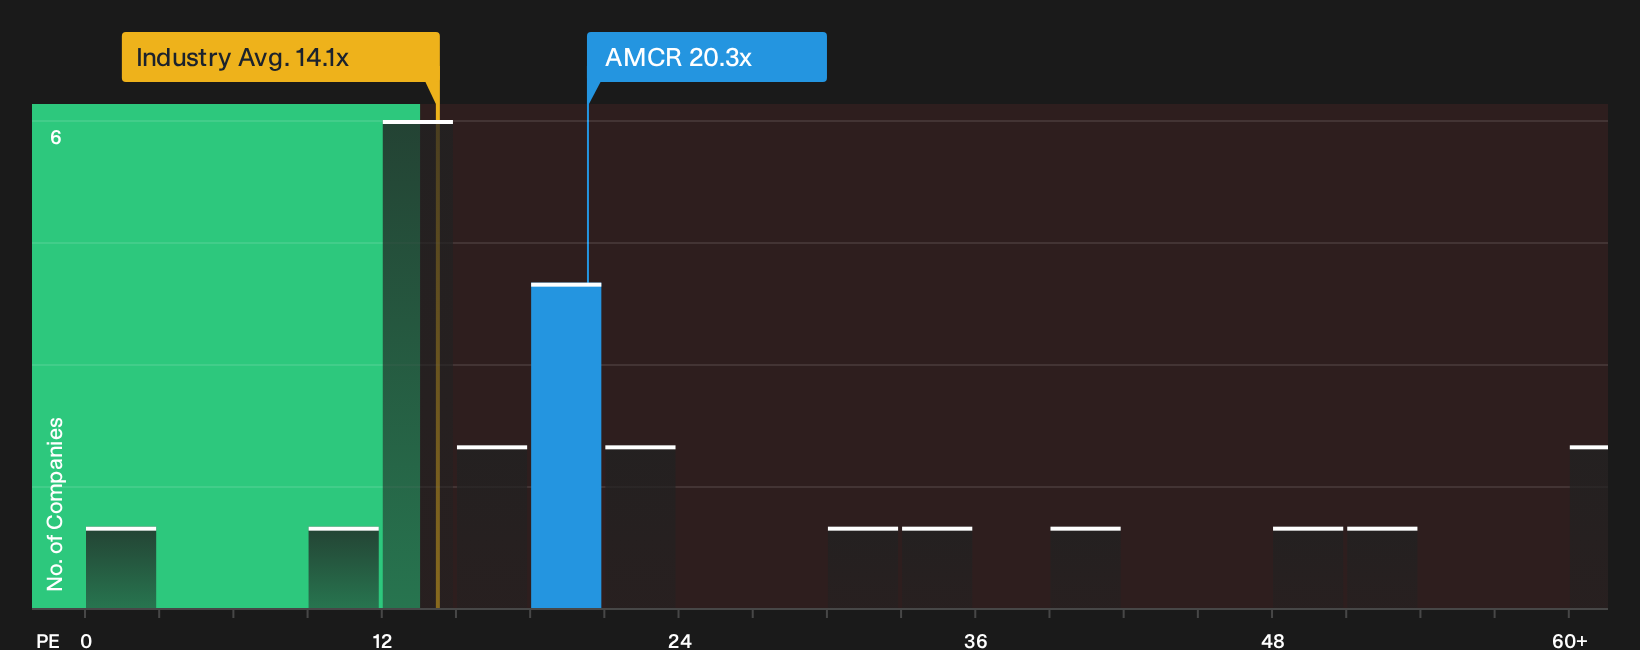
The story changes once you step away from cash flows and look at what investors are paying for Amcor’s earnings today. On a P/E of 20.3x, the stock trades above its fair ratio of 19.5x and well ahead of the global packaging average of 14.1x.
That gap suggests investors are already paying a premium for Amcor compared with both its own fair ratio and sector peers. This raises a simple question for anyone using earnings based valuation: How much future progress on synergies and margins do you want to pay for upfront?
For a closer look at how this earnings based view stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Amcor’s valuation story can easily pull you in either direction, so move quickly, test the numbers yourself, and weigh both sides. For the clearest blend of upside potential and areas of concern, review the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Amcor?
If Amcor has sharpened your focus on pricing, growth, and income, it may be worth broadening your watchlist. Fresh ideas often appear where fewer investors are looking.
- Spot potential long term compounders by scanning the 19 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Reduce portfolio stress by checking out 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Strengthen your income stream by reviewing the 5 dividend fortresses that aim to combine higher yields with durable cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com