


EN
Aflac (AFL) Stock May Be 28% Undervalued After Q3 Earnings Beat
Aflac has delivered a strong share price run in recent years, and that puts fresh attention on whether the insurance group’s current valuation is really supported by the returns it earns on its capital. With the stock now trading around US$125, the question is how much of its profitability profile is already reflected in that price.
- Aflac has returned about 150.5% over the past 5 years, which makes it important to ask whether the underlying returns on capital justify that kind of compounding.
- The company’s latest earnings update and its 44th consecutive annual dividend increase suggest management still sees its capital position and cash generation as strong enough to support ongoing shareholder payouts, which can influence how investors think about the value created on each dollar retained in the business.
- Prefer to judge Aflac on earnings? See why Aflac's 12.9x P/E tells a different valuation story.
The issue now is whether the returns Aflac earns on its capital are high and durable enough to make today’s share price look sensible on that basis.
If you want to see how Aflac’s return on capital profile compares with other opportunities, you can compare it with companies in the solid balance sheet and fundamentals stocks screener (24 results).
Is Aflac a Bargain on Excess Returns?
The Excess Returns model looks at how much profit Aflac generates on each dollar of equity above its estimated cost of capital and then projects that forward. On the inputs here, book value is $60.35 per share and the average return on equity sits at 13.53%, compared with a cost of equity of $4.50 per share. That leaves an estimated excess return of $3.92 per share, alongside a stable EPS figure of $8.42. This points to a business earning more than the model assumes is required to compensate shareholders for risk.
Those excess profits are paired with a stable book value projection of $62.25 per share, which suggests the model is not assuming aggressive balance sheet expansion to justify the outcome. The recent Q3 2026 earnings beat and the 44th consecutive dividend increase help explain why, despite that track record of distributions, the Excess Returns model still places Aflac's estimated intrinsic value meaningfully above the current share price of $125.30. Find out what Aflac could be worth using our Excess Returns estimate.
The Aflac Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Aflac leaves off, by spelling out which expectations for Aflac's growth, profitability and earnings would need to hold for the shares to be worth materially more or less than today. Each narrative sets out a fair value as a thesis about how the insurer operates and allocates capital so you can watch over time whether that story continues to match the numbers.
One of the top community narratives on Aflac: 6% overvalued
"The current valuation, alongside an Underperform rating and a US$103 price target from one research firm, suggests the market is cautious about Aflac’s ability to grow earnings beyond what capital returns and investment income already support..."
Discover why this Narrative puts Aflac at 6% overvalued.
Aflac’s price tag is only half the story for investors
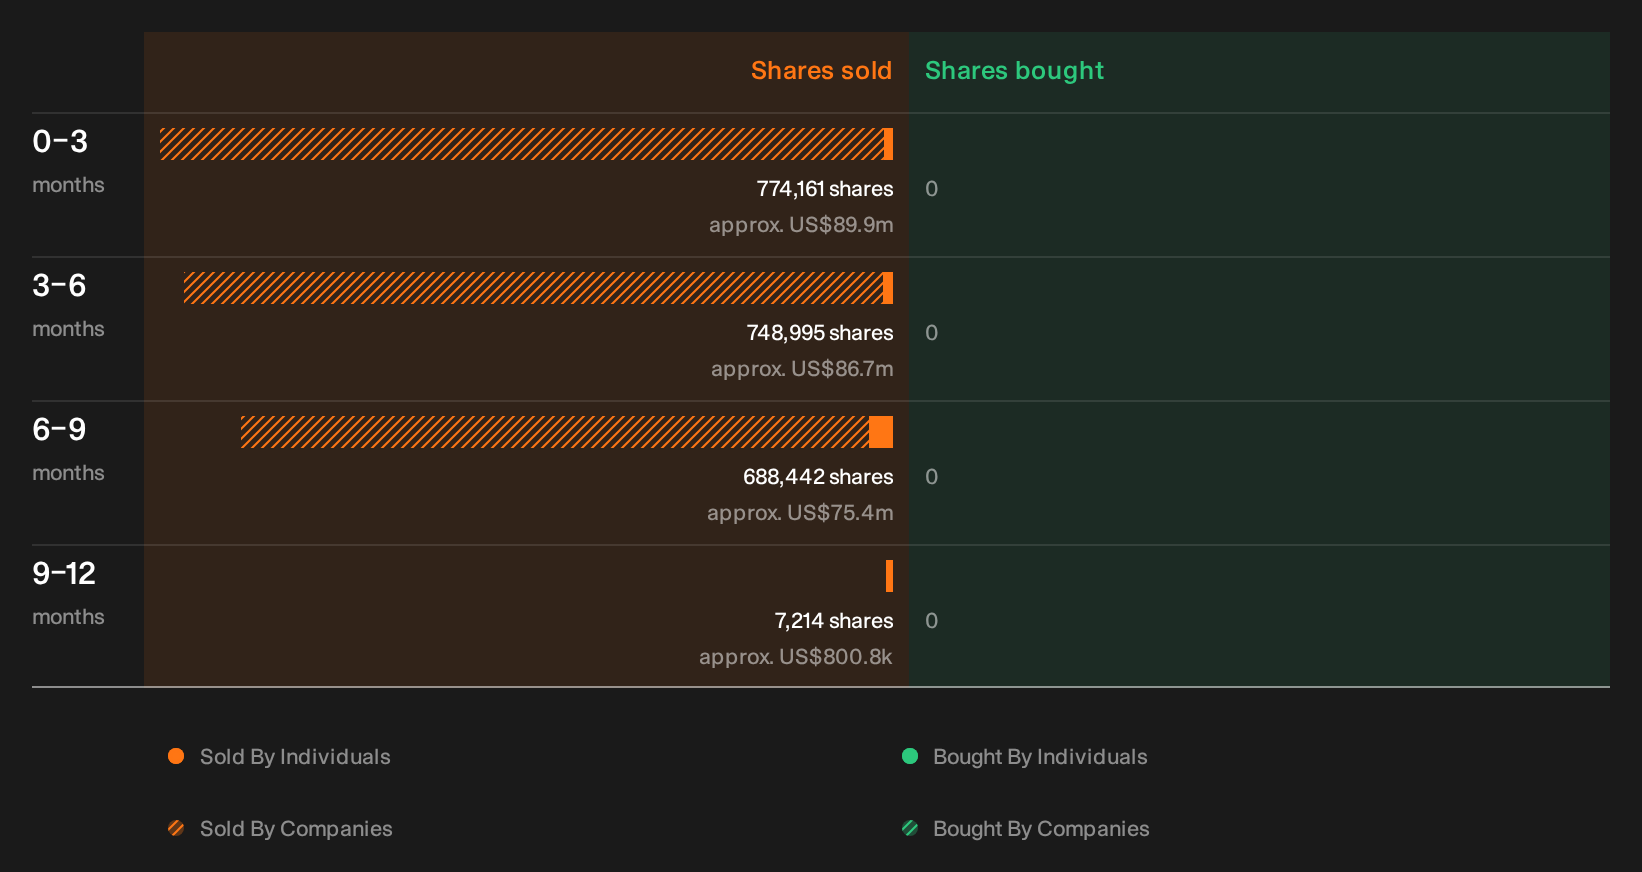
Valuation tells you what the market is willing to pay, but recent executive and director share sales can hint at very different motivations inside the boardroom. The specific trades here are worth inspecting closely. See the recent insider selling flagged for Aflac.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com