


EN
Why Did Daikin IndustriesLtd (TSE:6367) Shares Climb?
The latest review of the global air handling units market puts Daikin IndustriesLtd (TSE:6367) in focus, as rising demand for energy efficient HVAC systems and construction activity highlights the group’s exposure to this segment.
Recent trading shows Daikin IndustriesLtd shares gaining near term momentum, with a 1 day share price return of 2.70% and a 30 day share price return of 2.78%, while the 1 year total shareholder return of 13.23% contrasts with weaker 3 and 5 year total shareholder returns that remain in decline.
Scan beyond Daikin IndustriesLtd and see how other HVAC and capital goods players with strong fundamentals are lining up in the list of solid balance sheet and fundamentals (23 results).
Bulls point to Daikin IndustriesLtd’s recent share price gain and positive 1 year return, while bears focus on weaker 3 and 5 year performance. So, which story does the current valuation actually support next?
Preferred P/E of 21.8x: Is it justified?
On plain earnings terms, Daikin IndustriesLtd trades on a P/E of 21.8x, which is materially higher than both its peers and the wider JP Building industry, even though the current share price of ¥21,465 sits below some fair value estimates and analyst targets.
The P/E ratio compares what investors are willing to pay today for each unit of current profit. For a business like Daikin IndustriesLtd, which operates in HVAC and broader capital goods, this metric often reflects expectations about future earnings resilience, the perceived quality of its profit stream, and the breadth of its product portfolio.
There are a few cross currents here. Earnings have grown by 5.9% per year over the past 5 years and are described as high quality, yet net profit margins eased from 6% to 5.2% most recently and earnings fell 3.3% over the last year. Forecasts point to earnings growth of 9.6% per year, which is only slightly ahead of the JP market at 9.4% and supported by revenue growth forecasts of 3.7% per year that trail the broader market expectation of 6.3%.
Relative to the peer group, the premium is clear. Daikin IndustriesLtd trades on a P/E of 21.8x compared with the peer average of 15.5x and the JP Building industry on 11.8x, and that ratio also sits above the estimated fair P/E of 21.4x. This suggests the current valuation is already leaning to the rich side if the market eventually moves closer to that fair ratio level.
Explore the SWS fair ratio for Daikin IndustriesLtd.
Result: Price-to-earnings of 21.8x (OVERVALUED)
Still, the weaker 3 and 5 year total returns and the slimmer recent net margin leave Daikin IndustriesLtd exposed if earnings or pricing assumptions prove too optimistic.
Find out about the key risks to this Daikin IndustriesLtd narrative.
Another view on Daikin IndustriesLtd’s value
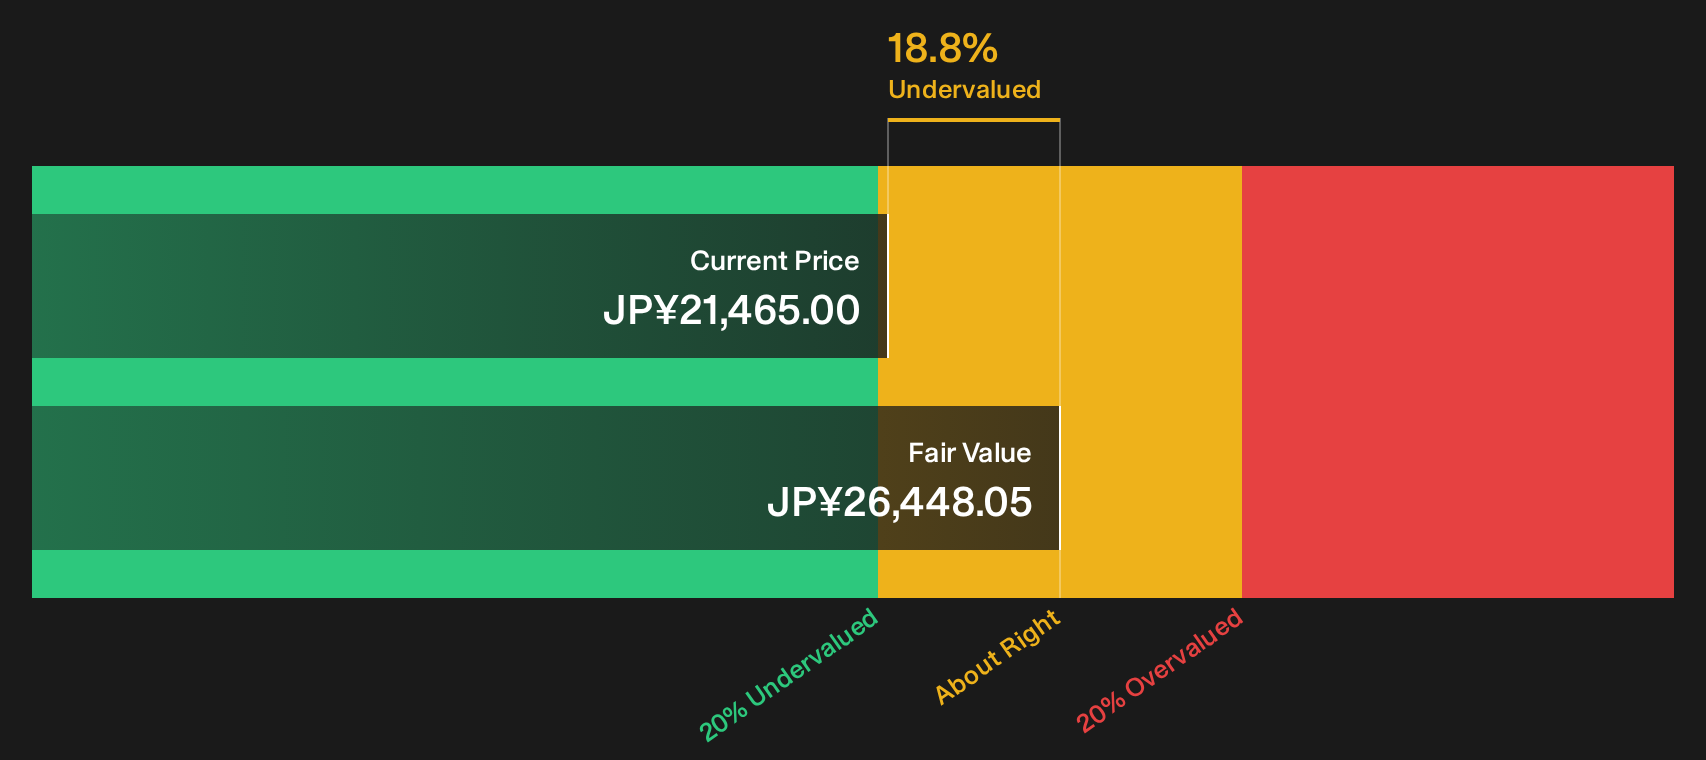
The P/E screen paints Daikin IndustriesLtd as pricey, yet the SWS DCF model points the other way. On that approach, the shares at ¥21,465 sit about 18.8% below an estimated future cash flow value of roughly ¥26,448, which frames today’s level as a potential discount rather than a premium. So which signal would you trust more if the two stay this far apart?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Daikin IndustriesLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of signals around Daikin IndustriesLtd feels unresolved, move quickly to test the assumptions against the raw data and firm up your own stance. To see the upside case that has investors optimistic, start by reviewing the 2 key rewards.
Looking for more investment ideas beyond Daikin IndustriesLtd?
Do not stop with one stock. Use the Simply Wall Street Screener to pressure test your thinking against fresh ideas that might suit your approach even better.
- Target potential mispriced opportunities by scanning for quality companies trading below their implied worth through the 19 high quality undervalued stocks.
- Build a steadier income base by reviewing companies screened as potential 28 dividend fortresses that could support a regular payout profile.
- Protect your downside by focusing on financially sound businesses using the 22 resilient stocks with low risk scores, which filters for resilience first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com