


EN
Zimmer Biomet (ZBH) Stock Looks Below Fair Value After 27% Rise
Zimmer Biomet Holdings has climbed sharply over the past year, and with the stock recently closing at US$110.15, the key question now is whether that move is supported by its earnings power. Strong headlines around new orthopedic technologies and a busier product pipeline give the story momentum, but price alone does not settle what investors are actually paying for each dollar of profit.
- The share price is up 27.2% over the past year, which puts fresh focus on whether the current valuation still lines up with the earnings the business is generating.
- Recent product launches and a broadened portfolio in robotics and connected orthopedic care may support expectations for future profit growth and cash generation, which feeds directly into how much investors are prepared to pay on an earnings basis.
- The analysts covering Zimmer Biomet Holdings have run their own numbers. See what analysts think Zimmer Biomet Holdings's shares could be worth.
The issue now is whether Zimmer Biomet Holdings' recent share price level is justified by its earnings when set against the Fair Ratio benchmark.
Zimmer Biomet Holdings is riding a strong year, but if you also want a starting list of other stocks filtered by clear rules, take a look at 38 healthcare AI stocks.
Does Zimmer Biomet Holdings Look Undervalued on Earnings?
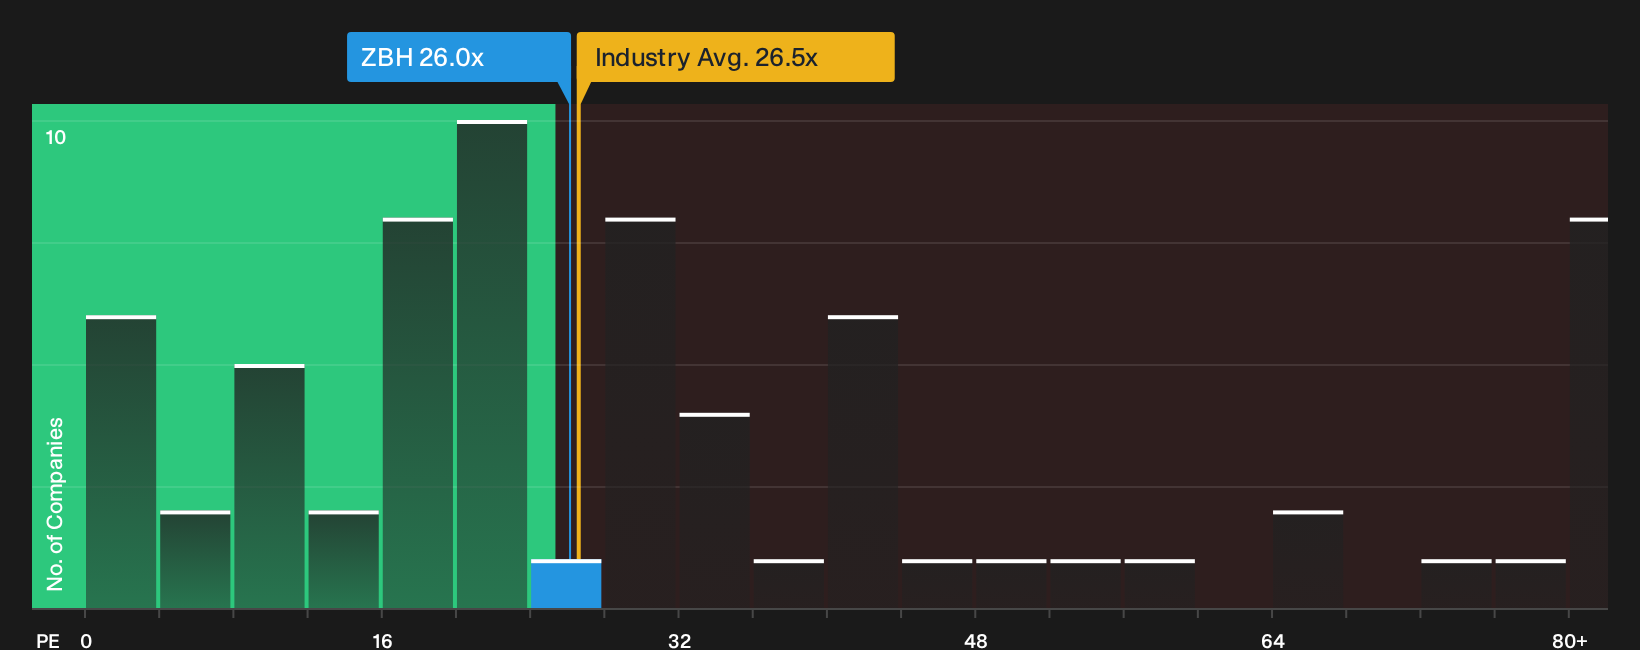
The P/E ratio is a useful lens for Zimmer Biomet Holdings because earnings remain a central yardstick for how investors judge its orthopedic and robotics pipeline. At roughly 26.0x earnings, the stock trades just below the broader medical equipment sector on about 26.5x and well under the peer group closer to 37.6x. That gap to similar healthcare stocks suggests the market is not placing a premium multiple on Zimmer Biomet despite its established position in joint replacement and surgical technology.
The Fair Ratio, which blends factors such as growth profile, profitability, size and risk, points to a higher P/E than where Zimmer Biomet currently trades, so the shares screen as undervalued on this metric. Because management lifted 2026 sales and earnings guidance after its latest quarter, the current discount to that Fair Ratio hints that investors are pricing in less optimism than the updated outlook might imply. For anyone weighing the stock today, the key question is whether Zimmer Biomet’s earnings quality and product mix justify a multiple closer to that tailored benchmark. Explore the numbers behind Zimmer Biomet Holdings's P/E valuation.
The Zimmer Biomet Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Zimmer Biomet Holdings' valuation puzzle leaves off. They spell out what kind of future growth, profitability and earnings profile would need to play out for the stock to look meaningfully cheaper or more expensive than today’s price, using separate scenarios that each lay out their own fair value framework so you can compare those underlying assumptions with the company’s reported numbers over time.
One of the top community narratives on Zimmer Biomet Holdings: roughly fairly valued
"The main factor that has to go right is successful execution of the commercial and cost-efficiency programs, including Project Optima, the global capability center in India, the Costa Rica plant, and integration of acquisitions such as Paragon 28 and iovera…"
Discover why this Narrative puts Zimmer Biomet Holdings at roughly fairly valued.
Zimmer Biomet Holdings: one more factor to check before relying on the valuation alone
Zimmer Biomet’s earnings multiple and Fair Ratio snapshot only tell part of the story, because the research checks have also flagged specific risk signals that deserve your attention before you act. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com