


EN
Lendlease Shares In Focus After Brisbane Rental Tower Opens
- Lendlease Group recently completed its Exhibition Place build-to-rent tower in Brisbane, with residents now moving in, adding a fresh income-producing asset to its portfolio.
- The opening of Exhibition Place highlights how Lendlease Group is leaning further into recurring rental income, which can matter for cash flow resilience compared with pure project sales.
- The next consideration is how Lendlease Group's investment narrative lines up with the Exhibition Place completion and its rental income potential.
Scan how Lendlease Group compares by running your ruler over our hand-picked list of solid balance sheet and fundamentals (12 results), which can better withstand higher interest rates and shifting rental economics.
What Is Lendlease Group's Investment Narrative?
Lendlease Group is a bet on complex precincts, fee based construction work and a growing pool of income producing assets like Exhibition Place. For a shareholder, the big picture rests on the business turning forecast revenue growth of 15.6% a year and expected profit recovery into consistent cash generation, while managing a capital intensive model that leans heavily on external borrowing and development spending.
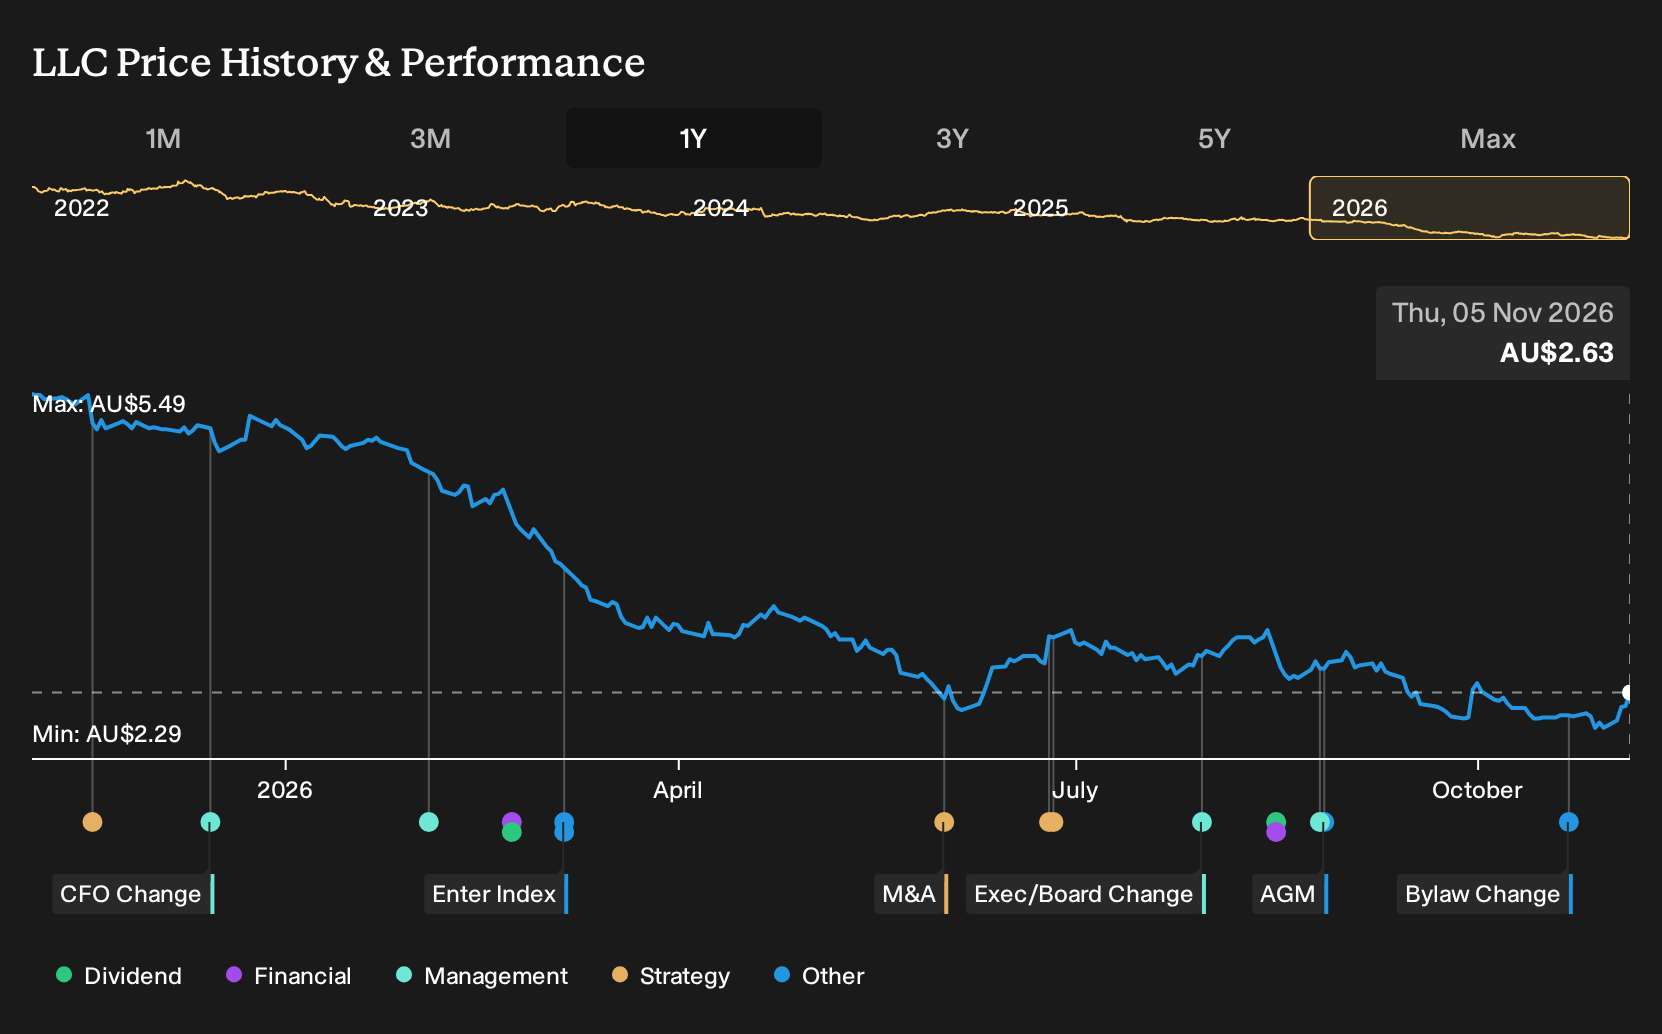
The proposed constitution changes flagged for the November 2026 meetings look more like governance housekeeping than an obvious near term earnings catalyst. In the short term, the sharper focus is on leasing and rent levels at new projects, execution risk across the A$5,429.0m revenue base and how higher interest rates interact with interest cover and a dividend that is not well supported by earnings or free cash flow.
Yet the part of the Lendlease Group story that deserves a harder look is ...
There's only one way to know the right time to buy, sell or hold Lendlease Group. Head to Simply Wall St's company report for the latest analysis of Lendlease Group's Fair Value.
Exploring Other Perspectives
Some readers will focus less on Exhibition Place and more on the risk that Lendlease Group’s capital release program drags. The lowest analysts were already cautious, despite still modelling revenue rising about 27.1% a year and earnings reaching roughly A$248.5 million by 2029. Fresh news like this could genuinely reshape their narrative.
Explore 3 other Lendlease Group fair value estimates, including one that suggests as much as 73% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lendlease Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lendlease Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lendlease Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lendlease Group?
If the Lendlease Group story leaves you wanting a broader watchlist, it can help to line it up against other businesses with different balance sheets, income profiles and risk levels.
- For investors hunting for value and quality together, compare Lendlease Group with a wider field of potential opportunities through the 5 high quality undervalued stocks.
- If capital preservation matters just as much as upside, filter for businesses that score well on financial resilience and lower risk using the 6 resilient stocks with low risk scores.
- When you want to widen the net and look for underfollowed opportunities with solid fundamentals, broaden your search with the 14 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com