


EN
Is GLOBALFOUNDRIES (GFS) Undervalued Following Strong Q3 Results And Raised Outlook?
GLOBALFOUNDRIES (GFS) drew fresh attention after third quarter 2026 results came in above guidance, with record non-IFRS gross margin and stronger AI, data center and communications infrastructure contributions capturing investor focus.
Despite the strong third quarter story, GLOBALFOUNDRIES has been under pressure in recent weeks, with the share price down 17.05% over 30 days and 25.20% over 90 days, even as the year-to-date share price return is 9.41% and the 1-year total shareholder return is 17.66%. This combination hints at positive longer term momentum but fading near term enthusiasm as investors reassess execution risks, capital spending plans, and the new dividend profile following the US$0.12 per share payout declaration and fresh guidance.
Scan beyond GLOBALFOUNDRIES and compare its recent pullback and AI exposure with a curated group of 53 AI infrastructure stocks.
Bulls see GLOBALFOUNDRIES as a mispriced AI and data center beneficiary after the selloff. Bears point to recent losses and heavy capital expenditures. The key question is which side the current valuation supports next.
Most Popular GLOBALFOUNDRIES Narrative: 46% Undervalued
The most followed valuation narrative pegs GLOBALFOUNDRIES at a fair value of $74.36 compared with the last close of $40.34, which frames the recent selloff as a sizeable gap between price and modeled expectations.
GlobalFoundries diversified manufacturing footprint in the U.S., Europe and China continues to align with customer requirements for regionalized and resilient supply, reinforced by government funding and customer co investment, which can support higher long term revenue and free cash flow.
See why 48 investors see GLOBALFOUNDRIES as 46% undervalued.
The narrative uses an 11.53% discount rate and assumes revenue growth of 13.51% a year, earnings expansion of about 38% a year and a 16.04% long run profit margin, then discounts those cash flows back to today to reach its $74.36 figure.
It also applies a future P/E of 33.50x that sits below the current semiconductor industry level cited in the narrative, which suggests the model is not relying on a very aggressive multiple to support the upside case and instead leans more on the growth and margin profile tied to funded capacity and higher value end markets.
Result: Fair Value of $74.36 (UNDERVALUED)
Still, the GLOBALFOUNDRIES narrative can crack if weak smart mobile demand lingers or if heavy capital spending fails to translate into stronger free cash flow.
Find out about the key risks to this GLOBALFOUNDRIES narrative.
Another Take On GLOBALFOUNDRIES Valuation
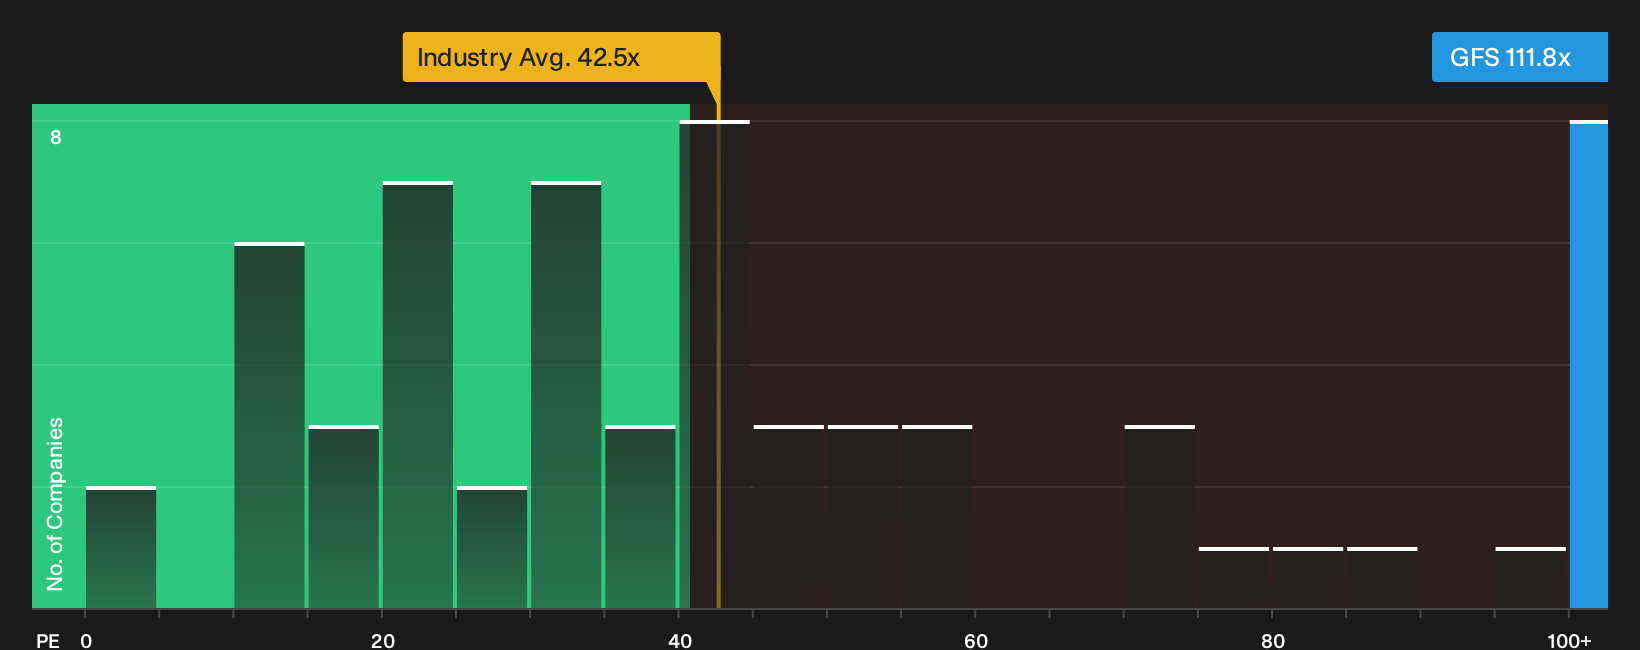
That $74.36 fair value hinges on long term growth and margin assumptions. A simpler lens tells a different story. GLOBALFOUNDRIES trades on a P/E of 111.8x, while the fair ratio points to 38.6x and peers sit closer to 42.9x. That wide gap loads more valuation risk onto every future forecast. Which view do you trust more when sentiment shifts?
For a closer look at how that earnings multiple compares with the broader semiconductor group, and what it might mean if the market moves toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling the split sentiment on GLOBALFOUNDRIES after its pullback and the ongoing valuation debate. Act quickly, test the key assumptions yourself, and weigh them against the 2 key rewards.
Looking for more GLOBALFOUNDRIES investment ideas to compare?
If GLOBALFOUNDRIES has your attention, do not stop here. Use the screener to stack it against fresh ideas and avoid missing better setups.
- Target resilience first by scanning companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Spot potential mispricings by lining up GLOBALFOUNDRIES against a 35 high quality undervalued stocks that share solid cash generation and cleaner financials.
- Hunt for overlooked potential by checking a 19 high quality undiscovered gems with robust underlying business quality before they reach wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com