


EN
Dominion Energy (D) Stock Looks About Right Despite Strong Q3 Earnings
Dominion Energy, which trades on the NYSE as D and last closed at US$69.75, has delivered a strong multiyear run that now puts a simple question in front of investors who focus on valuation. Is the stock price that move has created still in line with what the company earns today and what its earnings power suggests?
- Over the past 3 years the Dominion Energy share price has returned 74.9%, which puts real pressure on the question of whether its current earnings base can carry that gain.
- Recent earnings strength, ongoing offshore wind investment and rising contracted data center capacity all feed into expectations for Dominion's future profit profile, which can matter a lot for how much investors are prepared to pay for each dollar of earnings today.
- There is a second opinion on Dominion Energy worth weighing. See what analysts think Dominion Energy's shares could be worth.
The stock's next move may depend on whether Dominion Energy's current earnings and outlook justify the valuation investors are placing on it today.
You can explore Dominion Energy's earnings-based valuation across a wider set of regulated utilities by scanning the 41 power grid technology and infrastructure stocks.
Where Does Dominion Energy Sit on Earnings?
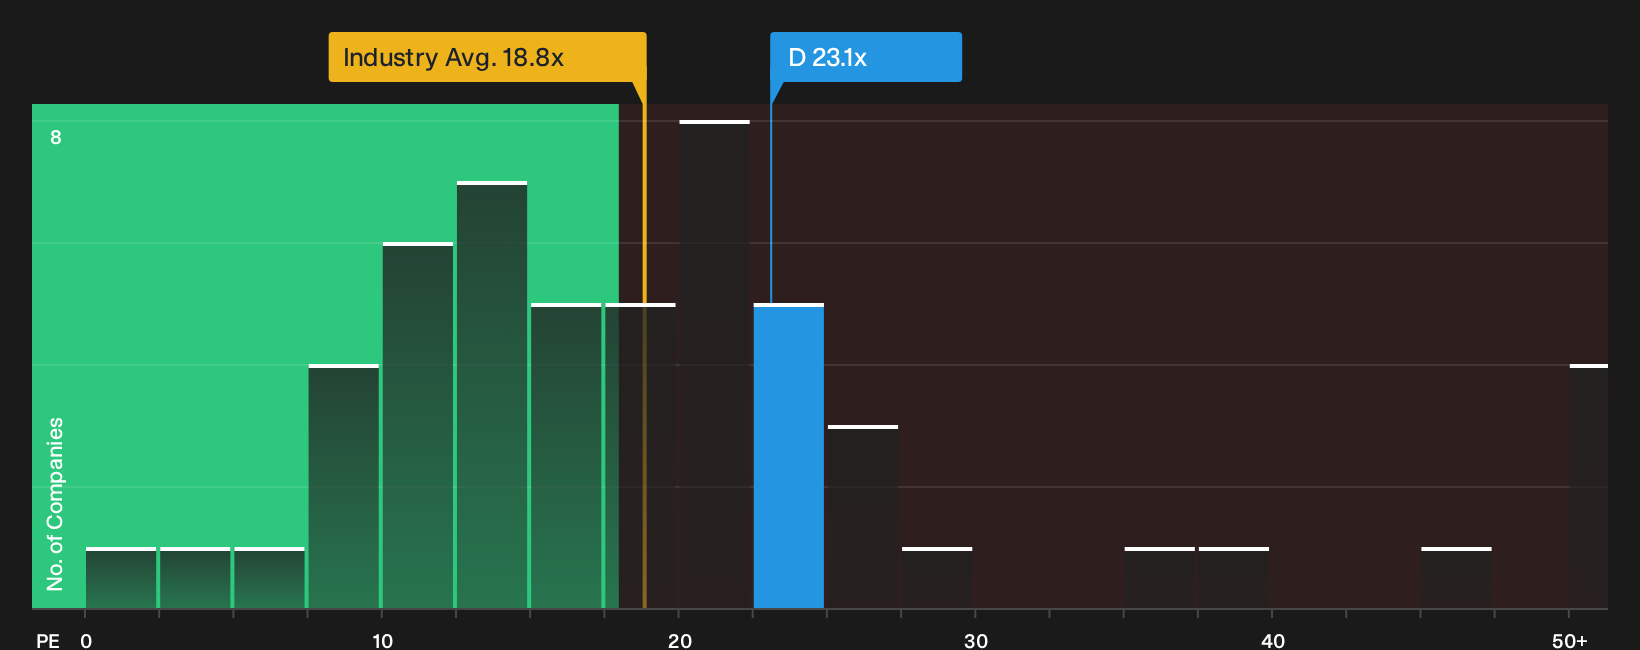
A P/E lens makes sense for Dominion Energy because earnings still anchor how investors frame regulated utilities with ongoing capital projects. On this yardstick, Dominion trades at roughly 23.1x, a modest premium to the integrated utilities sector average of about 18.8x and just above the peer group at around 21.5x. That points to investors paying a little more per dollar of earnings than for typical large utility peers.
The fair-value P/E that incorporates Dominion Energy's growth profile, margins, scale and risk comes out slightly higher than where the shares change hands today, which leaves the current multiple looking about right rather than stretched. Because Q3 2026 earnings and offshore wind progress already appear to be reflected in the price through this mid‑20s P/E, the key question for you is whether that earnings path and project execution still justify paying close to this level relative to other regulated power providers. Explore the numbers behind Dominion Energy's P/E valuation.
The Dominion Energy Narrative: What Would Justify Today's Price?
Narratives for Dominion Energy pick up where the P/E question leaves off and explain which earnings, margin, and growth paths would need to hold for the stock to be worth meaningfully more or meaningfully less than it is today on Simply Wall St's Community page. Each narrative presents Dominion Energy's implied fair value as a specific, testable view of the business that you can track over time instead of a one-off snapshot.
One of the top community narratives on Dominion Energy: roughly fairly valued
"The current valuation implies the market is still discounting Dominion Energy’s potential benefits from long-lived regulated investment in projects such as CVOW…"
Discover why this Narrative puts Dominion Energy at roughly fairly valued.
One more Dominion Energy check that belongs alongside the share price
Before you stop at the multiples and project pipeline, it is worth asking who is steering Dominion Energy and how their pay packets line up with your interests as a shareholder. See who runs Dominion Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com