


EN
National Australia Bank (ASX:NAB) Restructuring Puts Fair Value Back In Focus
National Australia Bank (ASX:NAB) has put investors on alert after full-year cash earnings and statutory profit came in below analyst expectations, with higher credit impairment charges and software costs pressuring results and prompting a large restructuring program.
At a share price of A$38.96, National Australia Bank has seen a sharp 1-day share price decline of 5.37% and a 7-day share price drop of 5.80% around the weaker earnings update and restructuring news, even though the 3-year total shareholder return of 54.91% and 5-year total shareholder return of 67.38% point to a much stronger longer-term record than the recent momentum suggests.
Compare National Australia Bank's reset with a curated group of banks and financials that currently screen as list of solid balance sheet and fundamentals (12 results) for potential resilience through the next round of results.
The share price reset at A$38.96 gives National Australia Bank a very different entry point than even a few weeks ago. This raises the question of whether that justifies buying now, or whether patience still looks more sensible on valuation grounds.
Most Popular Narrative: 1% Overvalued
On the most followed narrative, National Australia Bank screens as slightly above its A$38.46 fair value estimate, with the last close at A$38.96 and only a narrow gap between the two figures once everything is discounted at 8.01%.
Ongoing technology modernization and AI adoption, including completion of multi cloud infrastructure, migration to a modern data platform and deployment of AI tools to over 7,000 software engineers with targeted productivity savings of more than $450 million in FY 2026, is aimed at improving operating leverage and supporting net margins over time.
See why 83 investors see National Australia Bank as 1% overvalued.
Result: Fair Value of A$38.46 (ABOUT RIGHT)
Still, the story around National Australia Bank can shift quickly if technology spending continues to rise faster than revenue or if business loan losses start to climb.
Find out about the key risks to this National Australia Bank narrative.
Another View On National Australia Bank’s Value
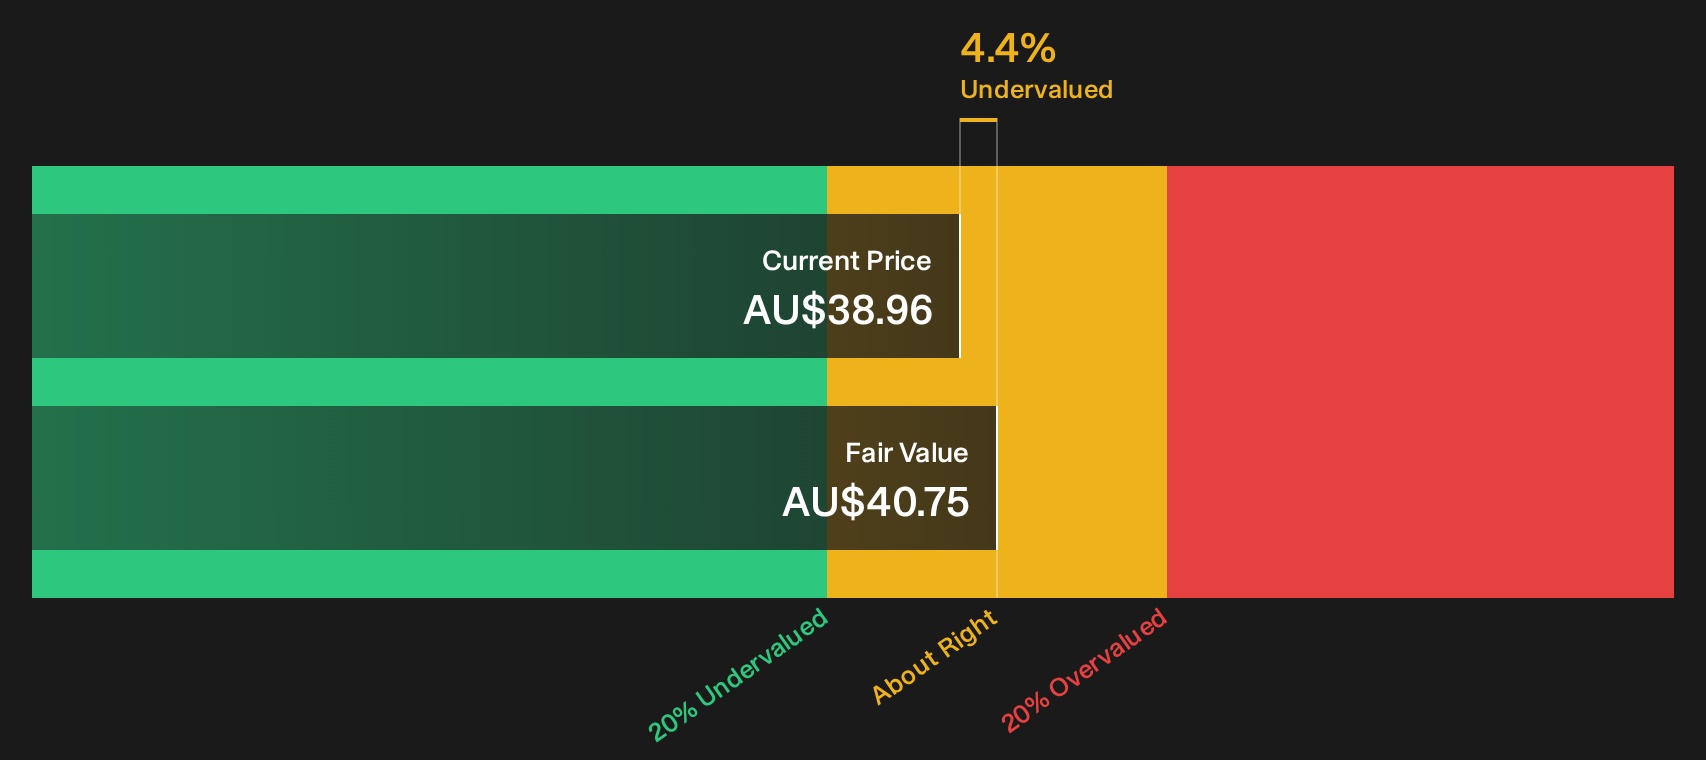
The first take presents National Australia Bank as close to fairly priced, yet the SWS DCF model points in a different direction. On that framework, NAB at A$38.96 trades about 4.4% below an estimated future cash flow value of A$40.75. This suggests a modest potential undervaluation. Which lens do you rely on more for the next decision point?
For a closer look at the moving parts behind that cash flow estimate, including the discount rate and long term assumptions baked into it, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out National Australia Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around National Australia Bank is clearly split, with clear concerns sitting alongside meaningful positives. Move quickly, review the data in full, and weigh both sides before you decide which matters more for you, then dig into the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond National Australia Bank?
If National Australia Bank is already on your radar, use this reset as a springboard to scan fresh opportunities and keep your watchlist one step ahead.
- Target potential mispricings by reviewing the 5 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- Build a steadier income stream by assessing the 5 dividend fortresses that clear a high yield bar with support from underlying cash generation.
- Dial down portfolio risk by focusing on the 6 resilient stocks with low risk scores that combine sturdier balance sheets with more resilient business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com