


EN
Does Return To Profit Guidance Change The Bull Case For Kemper (KMPR)?
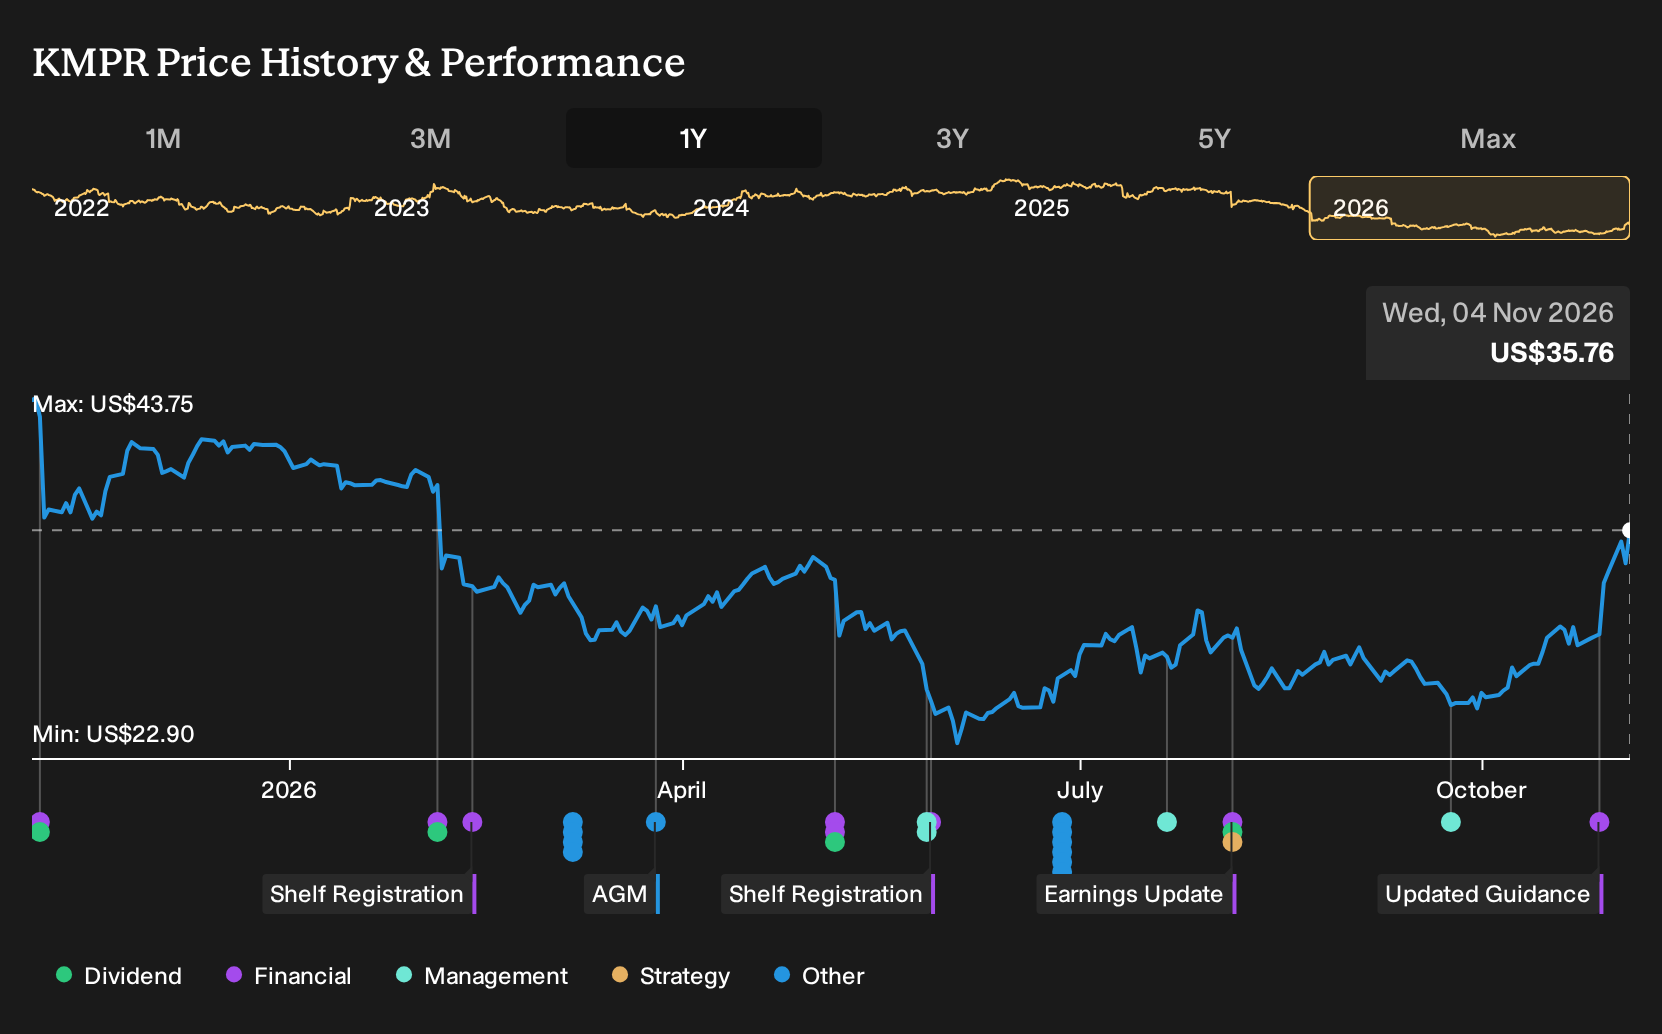
- Kemper Corporation issued new guidance for the third quarter of 2026, projecting net income of about US$52 million, or US$0.88 per diluted share, after reporting a net loss of US$465 million, or US$7.90 per share, in the prior quarter.
- The swing from a large loss to guided profitability highlights how recent restructuring, underwriting adjustments and cost actions may be starting to influence Kemper's earnings profile.
- This report explores how Kemper's guided return to quarterly profitability could reshape the existing investment narrative around its restructuring.
Scan how other insurers with restructuring stories are setting up for their next leg by reviewing the hand picked 31 resilient stocks with low risk scores alongside Kemper's guidance shift.
Kemper Investment Narrative Recap
To own Kemper, you need to believe the restructuring can turn a large recent loss into a more repeatable earnings base. The guided US$52 million Q3 2026 profit points to early traction, but the near term story still hinges on whether underwriting, pricing and expense actions in specialty auto hold up across more than one quarter.
The key near term catalyst is evidence that Kemper can keep improving combined performance while staying disciplined on California auto exposure and rate adequacy. The main risk is that pressure in that state, together with interest costs and weaker surplus note economics, keeps dragging on margins and return on equity even if a single quarter looks better.
With guidance now flagging a move from a US$465 million quarterly loss to an expected US$52 million profit, the Q3 2026 outlook itself is the most relevant recent communication. It gives you a concrete earnings marker to compare against the earlier goodwill impairment in specialty auto and the ongoing restructuring cost work.
Where this matters for catalysts is execution. If Kemper reports in line with, or close to, this guidance while also maintaining progress on the targeted expense ratio improvement and the mix shift away from unprofitable California auto, that would support the broader thesis around restructuring and technology investments. If results fall short, it would sharpen focus on earnings quality, interest coverage and the timing of any improvement in group margins.
What Consensus Forecasts Assume For Kemper
Kemper's current analyst narrative points to forecast revenue of US$4.3b and earnings of US$527.0 million by 2029. This setup assumes revenue declining at about 2.2% per year, with earnings expected to move from a loss of US$495.5 million today to a profit of US$527.0 million in 2029, which is an earnings swing of roughly US$1.0b over that period.
Uncover why Kemper's fair value is broadly in line with its current price.
Exploring Other Perspectives
Bullish analysts lean into a different catalyst for Kemper. They focus on the potential earnings ramp, with prior high end forecasts pointing to about US$4.6b of revenue and US$488.8 million of earnings by 2029. Those estimates were set before this guidance, so treat them as one viewpoint and compare several angles yourself.
Explore 3 other Kemper fair value estimates, including one that suggests there may be up to 20% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kemper research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kemper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kemper's overall financial health at a glance.
Looking For More Ideas Beyond Kemper?
Once you have formed a view on Kemper, it can help to line it up against other opportunities so you can see where the risk, quality and income profile really stand out.
The Simply Wall St Screener makes that comparison work easier by filtering the market around the characteristics you care about most.
- For investors who care most about resilience, start with a curated set of lower risk opportunities through the 31 resilient stocks with low risk scores.
- If you want to focus on quality businesses that might be trading below what their fundamentals suggest, take a look at the 35 high quality undervalued stocks.
- For readers who prefer to cast a wider net and hunt for strong operators that are not yet widely followed, scan through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com