


EN
X Energy (XE) Stock Could Be Rich After Xe 100 Supply Chain News
X-Energy shares have fallen sharply so far this year, which puts a spotlight on whether the current US$10.05 price still lines up with the company’s sales profile. With fresh project news coming through on its Xe-100 reactor program, the key issue for you as an investor is how much revenue potential is already baked into today’s valuation.
- The stock is down 65.6% year to date. This means any reassessment of what its sales can realistically support has an outsized impact on whether the recent drop has gone too far or not far enough.
- Alleima’s first order for steam generator tubing in the Xe-100 reactor program moves X-Energy a step closer to commercial deployment. This can influence how confidently investors treat future sales expectations tied to that Texas project and related supply chain build out.
- Your read on X-Energy is one view; the desks covering it have another. See what analysts think X-Energy's shares could be worth.
The stock’s next move may depend on whether X-Energy’s current share price is adequately grounded in the level and trajectory of its sales.
If you want a broader starting point while you assess X-Energy’s sales story, apply the same analysis to 16 nuclear energy infrastructure stocks as well.
Is X-Energy Getting Expensive on Sales?
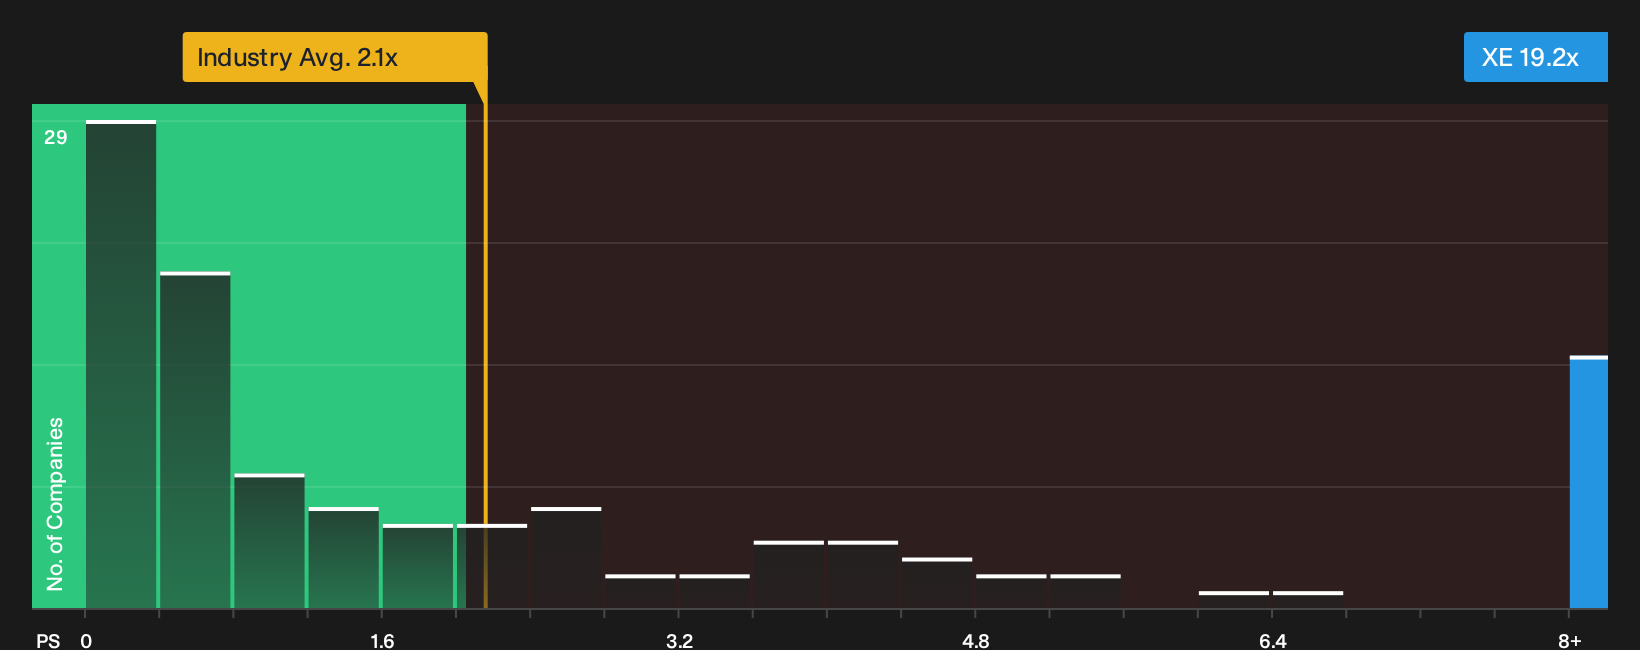
P/S is a useful lens for X-Energy because the business is still being valued more on commercial potential than on current earnings. At about 19.2x P/S, the stock trades far above the broader Electrical industry, which averages roughly 2.1x, and also above peers at about 3.6x. That sort of gap indicates the market is already assigning a sizeable premium to the company’s existing revenue base.
The fair multiple model, which adjusts for X-Energy’s specific growth profile, profitability outlook, scale and risk, points to a much lower P/S level than where the shares change hands today. The very wide gap suggests the framework is heavily discounting current losses and execution risk, so the present 19.2x P/S is better read as a warning signal that the stock prices in demanding expectations rather than a precise mispricing estimate. Because Alleima’s tubing order anchors the Xe-100 project more firmly in real-world activity, sentiment around X-Energy’s future top line may stay optimistic even though the P/S ratio already embeds a rich set of assumptions. Explore the numbers behind X-Energy's P/S valuation.
The X-Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the X-Energy P/S puzzle leaves off. They explain which paths for revenue, margins and earnings would need to occur for the stock to be worth meaningfully more or less than today’s price. They also set out the assumptions behind each fair value so you can track those against actual results as they arrive.
A written, number-driven Narrative on X-Energy gives you a clear view of what assumptions about future sales, margins and execution need to come true for today’s valuation to make sense. With the Alleima steam generator tubing order marking a concrete step toward the Xe-100 deployment in Texas, a structured view on whether that kind of contract flow ultimately supports the current P/S level can be tracked cleanly as new project data is released.
Share your own Narrative for X-Energy and set out the assumptions behind your valuation.
X-Energy’s price is only one piece of the decision
Valuation is just the starting point for X-Energy, because recent research has also flagged potential pressure points in the business that deserve your attention before you commit fresh capital. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com