


EN
HSBC Holdings (LSE:HSBA), What Is Behind Its Latest Update?
HSBC Holdings (LSE:HSBA) has just paired solid third quarter earnings and reaffirmed 2026 guidance with a fresh quarterly dividend proposal, putting the bank’s latest capital decisions in sharp focus for shareholders.
Recent price action has been mixed. The share price is down about 11% over the past month and around 15% over the last quarter, yet HSBC Holdings still shows a 9.7% year to date share price gain and a 1 year total shareholder return of 25.33%. This suggests that long term momentum remains stronger than the latest pullback as the market weighs solid earnings, fresh debt issuance and ongoing capital return plans.
Scan how HSBC Holdings stacks up against other large, income focused banks by reviewing our hand picked 4 dividend fortresses with resilient payouts and substantial yields.
Bulls point to HSBC Holdings’ stronger recent earnings, fresh dividend and guidance, while bears focus on the sharp pullback and new debt. Which camp does the current valuation argue for as you weigh the next move?
Most Popular Narrative: 14% Undervalued
The most followed valuation story around HSBC Holdings currently pegs fair value at £15.15 using an 8.53% discount rate, compared with the last close at £13.07. That gap frames a thesis built around Asian wealth, transaction banking and disciplined cost control.
Intensifying investment in Asian wealth management and private banking remains central, with over 1 trillion US dollars of Asian wealth balances and strong net new money in Hong Kong and India. This points to further growth in fee income and, in turn, support for revenue and earnings resilience.
See why 172 investors see HSBC Holdings as 14% undervalued.
Result: Fair Value of £15.15 (UNDERVALUED)
Still, the narrative around HSBC Holdings could be tested if competition for deposits in Hong Kong and the UK squeezes net interest margins, or if planned business exits reduce revenue faster than expected.
Find out about the key risks to this HSBC Holdings narrative.
Another View On HSBC Holdings: What The P/E Is Saying
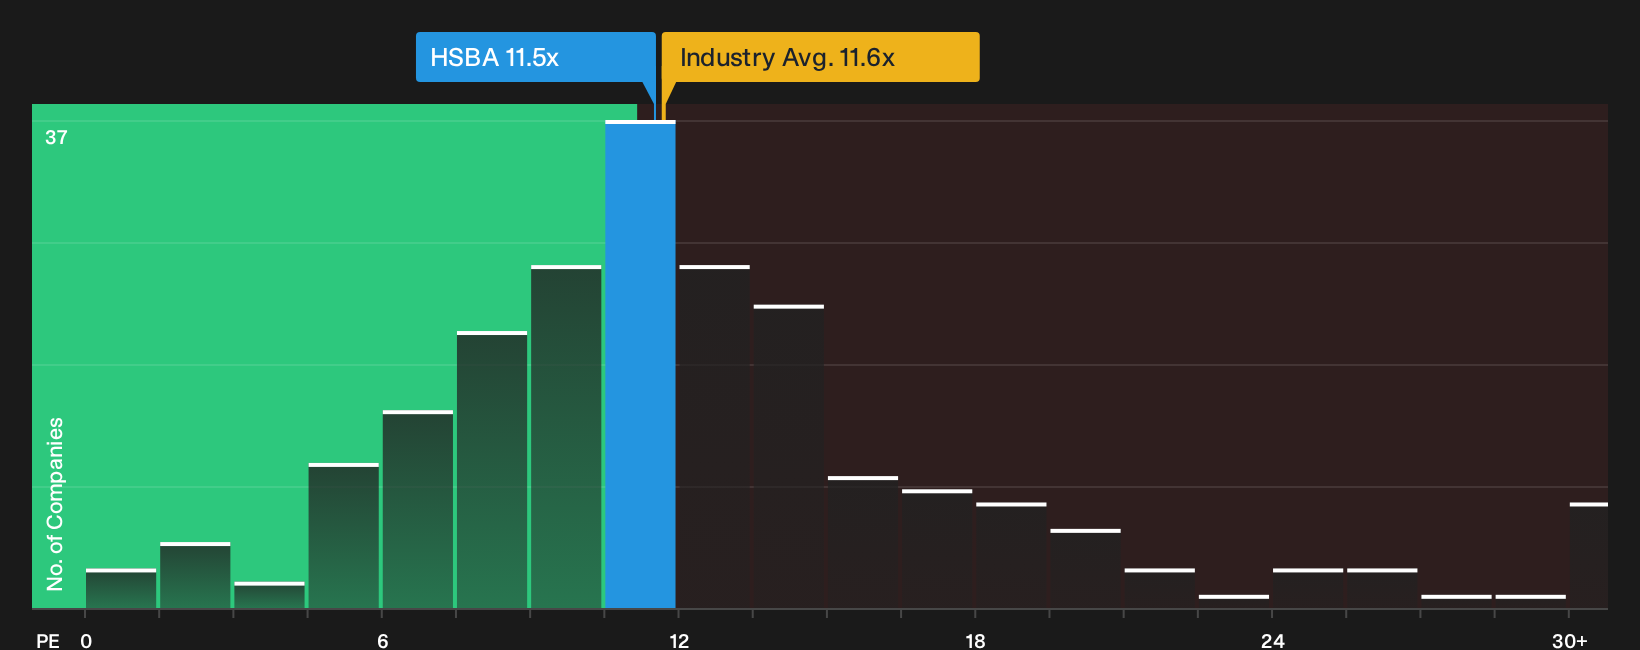
The earlier fair value story for HSBC Holdings leaned on detailed forecasts and analyst targets. A simpler lens looks at the P/E ratio of 11.5x, which is almost identical to the wider European banks average of 11.6x, yet above the 9x fair ratio estimate. That mix of alignment with the sector and premium to the fair ratio hints at less obvious upside and some valuation risk. If profit delivery or capital returns slip against expectations, how quickly could the market pull that multiple toward the fair ratio level?
To see how pure pricing comparisons stack against cash flow based work, and what the fair ratio gap might mean for you, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity? If you want to move before sentiment shifts again, weigh both sides of the story and review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond HSBC Holdings?
HSBC Holdings may be front of mind today, but the next opportunity could be sitting quietly elsewhere, waiting for investors who actually go looking.
- Spot potential mispricing early and review a curated 14 high quality undervalued stocks that blends quality fundamentals with pricing that some investors may be overlooking.
- Strengthen portfolio resilience and scan a focused list of solid balance sheet and fundamentals (10 results) so you are not caught out by weak finances when conditions change.
- Get ahead of the crowd and hunt through a 5 high quality undiscovered gems that highlights quality businesses before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com