


EN
Illinois Tool Works (ITW) Stock Seems About Right At Today’s Price
Illinois Tool Works has delivered steady share price gains in recent years, and the latest move higher is again putting the focus on what investors are paying for its earnings. After that kind of run, the live question is whether the current valuation still lines up with the profits the business is generating today.
- Over the past 5 years, Illinois Tool Works has returned 40.8%, which raises a clear issue for holders and potential buyers about how much future earnings strength is already reflected in the price.
- Recent earnings updates point to solid profitability and ongoing cost discipline, which can support expectations for the durability of the company’s earnings power and the level of cash it may generate for shareholders over time.
- Your read on Illinois Tool Works is one view; the desks covering it have another. See what analysts think Illinois Tool Works's shares could be worth.
The issue now is whether Illinois Tool Works' recent share price, after this multi year climb, is adequately supported by the earnings it produces today and what investors expect those earnings to look like in the future.
If you are weighing Illinois Tool Works at this earnings driven price, it can help to compare it against a broader set of companies using 35 high quality undervalued stocks.
Does Illinois Tool Works Look Fairly Valued on Earnings?
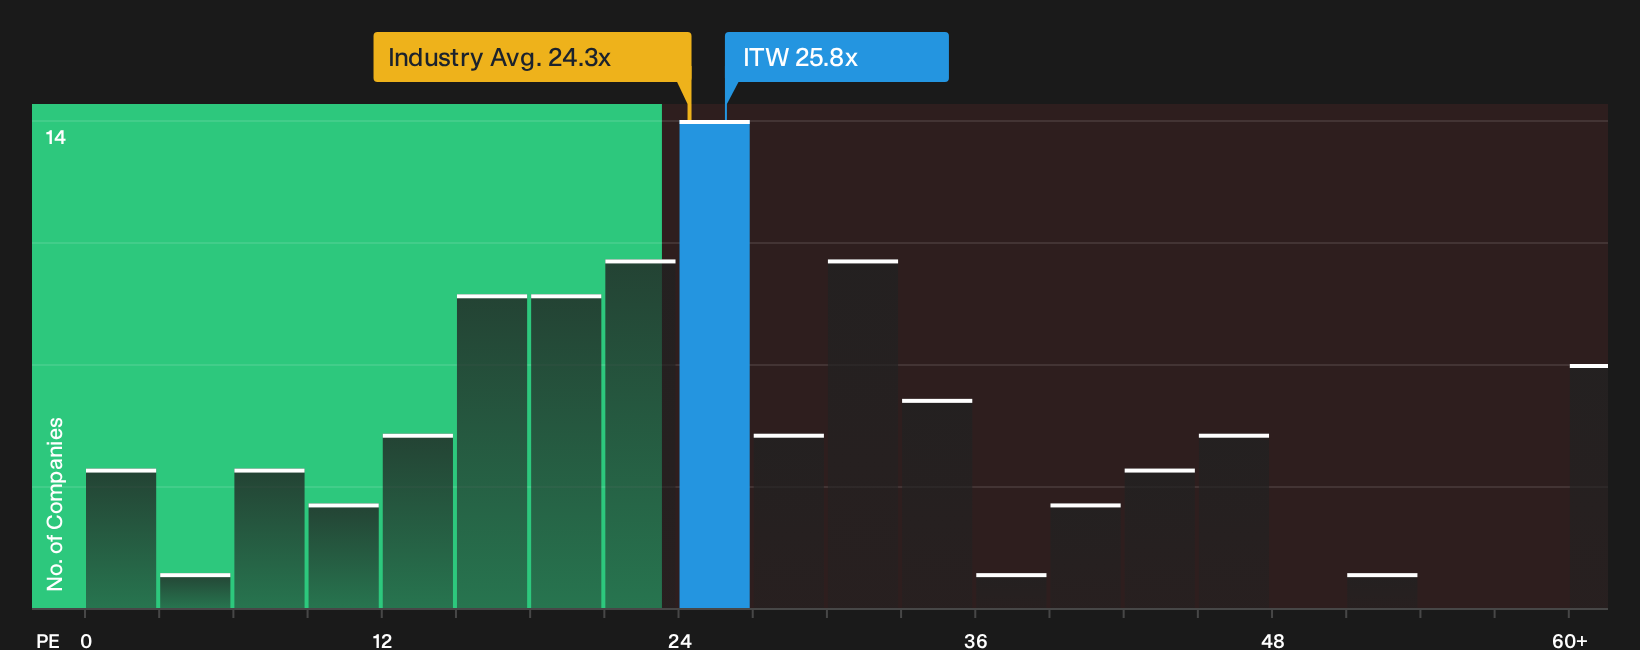
P/E is a useful yardstick for Illinois Tool Works because earnings are a central focus for holders watching how cash generation supports dividends and buybacks. The stock trades on a P/E of 25.8x, which sits slightly above the Machinery industry average of about 24.3x and is also higher than the peer group level of roughly 24.7x. That premium points to investors paying a bit extra for each dollar of current profit compared with many similar industrial businesses.
The valuation model suggests a tailored fair P/E multiple that reflects Illinois Tool Works' sector, risk profile and earnings quality. The current 25.8x price to earnings ratio is close to that mark, so the shares do not screen as obviously overvalued or obviously cheap on this measure. Because management has lifted 2026 earnings guidance after solid Q3 results, the market is being asked to decide whether that near fair P/E is a comfortable entry point or already prices in enough of the story. Explore the numbers behind Illinois Tool Works's P/E valuation.
The Illinois Tool Works Narrative: What Would Justify Today's Price?
Illinois Tool Works' valuation story now hinges on what kind of future the market is quietly pencilling in. Simply Wall St Narratives pick up that thread by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price, and each one treats fair value as a thesis about Illinois Tool Works' business. You can watch that thesis play out over time on the Community page.
One of the top community narratives on Illinois Tool Works: roughly fairly valued
The numbers and current valuation together imply a stock price that does not yet fully reflect Illinois Tool Works’ plan for operating margins above 30%...
Discover why this Narrative puts Illinois Tool Works at roughly fairly valued.
Before you act on Illinois Tool Works' valuation, there is one more angle to check
Price and earnings only tell part of the Illinois Tool Works story, because the research screen has also raised specific concerns that investors may want to review in detail before committing fresh capital. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com