


EN
How Market Weakness Could Impact 3i Group Shares Investors
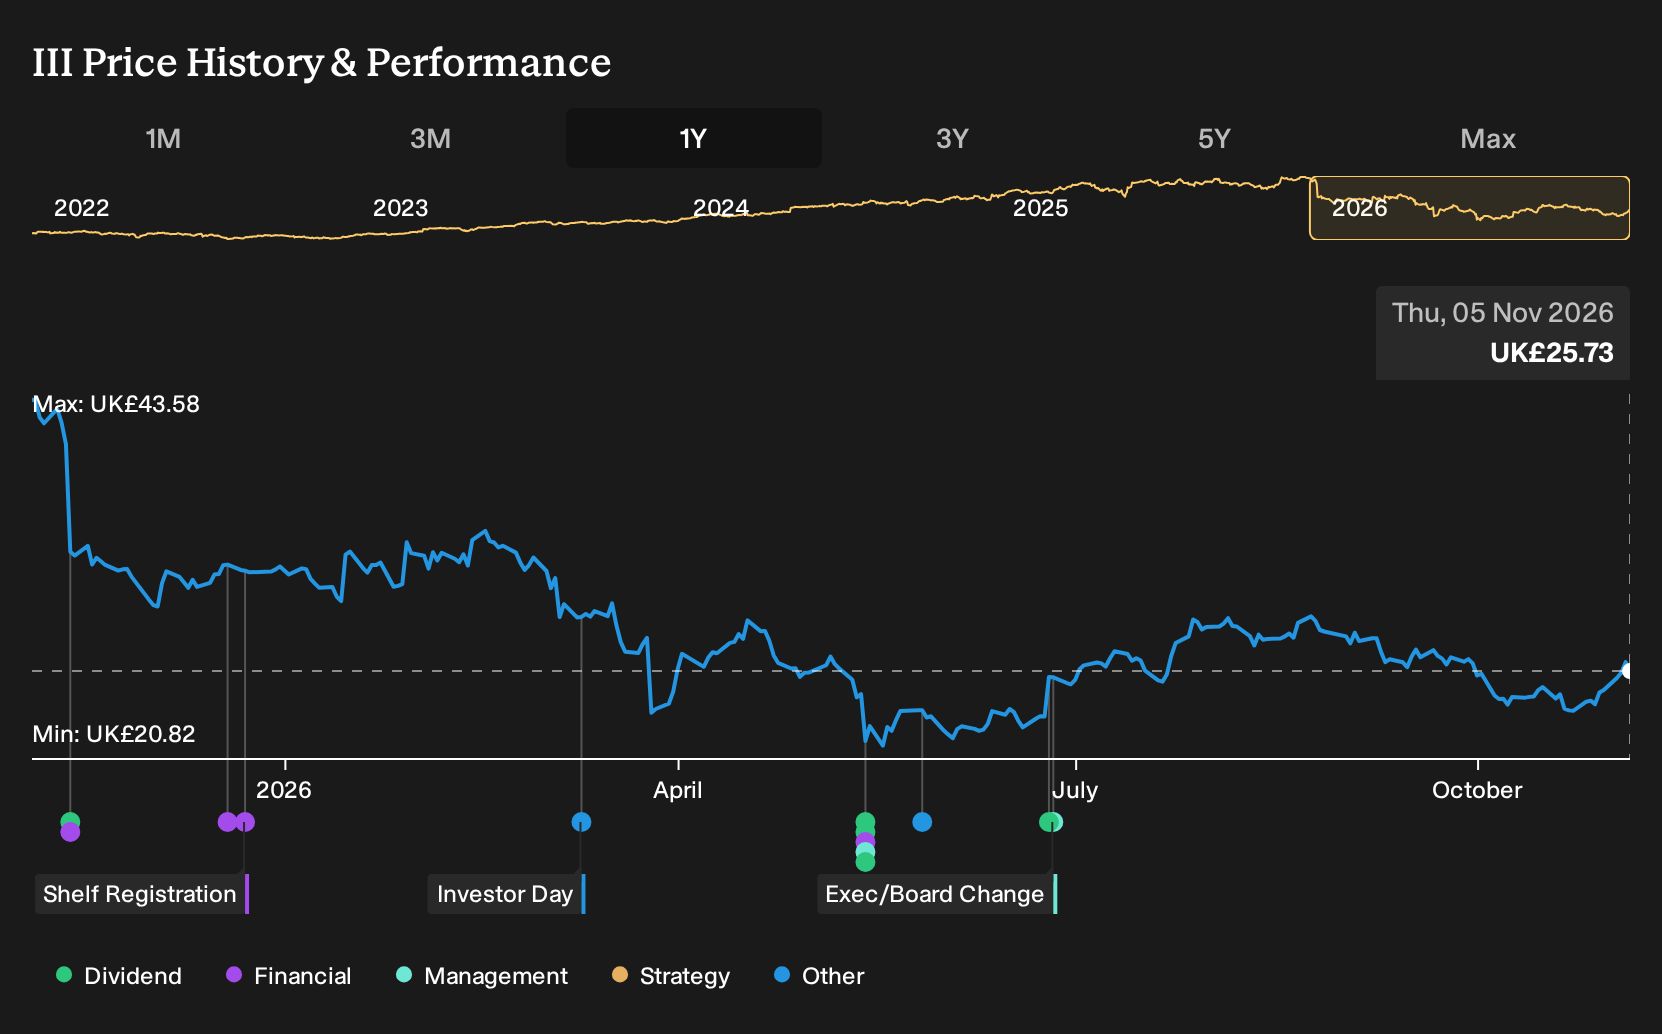
- 3i Group shares moved higher on a recent trading day even as wider equity markets weakened, with energy and mining companies under pressure.
- This relative strength indicates that investors may be focusing on 3i Group’s asset management and private equity operations as potentially more resilient when broader risk appetite softens.
- We will now look at how this show of confidence in 3i Group during a weak market could affect its investment narrative.
Scan how investor confidence in 3i Group compares with peers that also aim for resilience when sentiment turns risk off by reviewing the hand picked 5 resilient stocks with low risk scores in one place.
3i Group Investment Narrative Recap
To own 3i Group, you need to be comfortable with a private equity model that leans on deal selection, portfolio company execution and disciplined exits rather than day to day market sentiment. The recent 1.34% share rise on a weak session for wider indices looks more like a sentiment blip than a shift in fundamentals, so it does not materially change the near term picture.
The main short term swing factor remains how resilient cash flows from key holdings like Action and infrastructure assets prove if deal markets stay uneven. The biggest risk still sits with currency moves, higher leverage around Action and any slowdown in core European markets that could pressure net asset value and earnings translation.
There were no fresh company announcements directly tied to this share price move, so the trading day needs to be viewed against the existing story. That story revolves around 3i Group focusing on expanding its private equity portfolio and realising assets at what analysts describe as disciplined prices, while keeping an eye on leverage.
For you as a shareholder, the operational focus is how increased exposure to Action through a higher stake and past refinancing interacts with current investor confidence. The recent gain on a weak market day highlights how sensitive the stock can be to perceptions around that asset, even without new disclosures. This keeps execution at Action and ongoing infrastructure disposals central to both potential catalysts and key risks.
3i Group's narrative projects £8.6b revenue and £6.2b earnings by 2029. This profile is based on an assumed 9.2% yearly revenue growth and an earnings decrease of £0.1b from £6.3b today.
Uncover why 3i Group's fair value indicates a 46% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate storyline around 3i Group puts Action’s store rollout risk in the spotlight. The most cautious analysts were already baking in revenue of about £7.3b and earnings near £6.7b by 2029, yet still saw a much lower price as fair. After this resilient share move, those pessimistic assumptions may be revisited.
Explore 3 other 3i Group fair value estimates, including one that suggests it could be worth just £34.03!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your 3i Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for 3i Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 3i Group's overall financial health at a glance.
Looking for more 3i Group style investment ideas?
If the recent move in 3i Group has you rethinking how you build resilience and upside into your portfolio, it can help to scan a broader set of opportunities with similar qualities using the Simply Wall St Screener.
- If capital preservation is front of mind, start by reviewing a list of solid balance sheet and fundamentals (10 results) that keeps financial strength in focus.
- If you want potential value on your side, broaden your watchlist with a 14 high quality undervalued stocks that pair quality fundamentals with pricing that still looks reasonable.
- If income is a key part of your plan, round out your research by checking a 4 dividend fortresses that combine higher yields with business models built for staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com