


EN
Progyny (PGNY) Stock Looks Fairly Valued Despite Raised Earnings Guidance
Progyny has delivered a 59.4% return over the past year, putting fresh attention on whether the recent share price around US$30.10 lines up with what its earnings can support. With the stock coming off a weaker multi year record and fresh company updates in 2026, the question now is how much of Progyny's profit story is already baked into today's valuation.
- The 59.4% gain over the past 12 months puts real pressure on the earnings case, because a move of that size can quickly pull a valuation away from what recent profits justify.
- Management's higher earnings outlook, including projected net income between US$107.0 million and US$110.6 million, may support an argument that the business can grow into a richer earnings multiple over time.
- The analysts covering Progyny have run their own numbers. See what analysts think Progyny's shares could be worth.
The stock's next move may depend on whether Progyny's current price is supported by its earnings when measured against the Fair Ratio benchmark.
If you want a broader watchlist while you assess whether Progyny's 59.4% one year return matches its earnings power, a focused screen of 35 high quality undervalued stocks can be a useful second reference point.
Where Does Progyny Sit on Earnings?
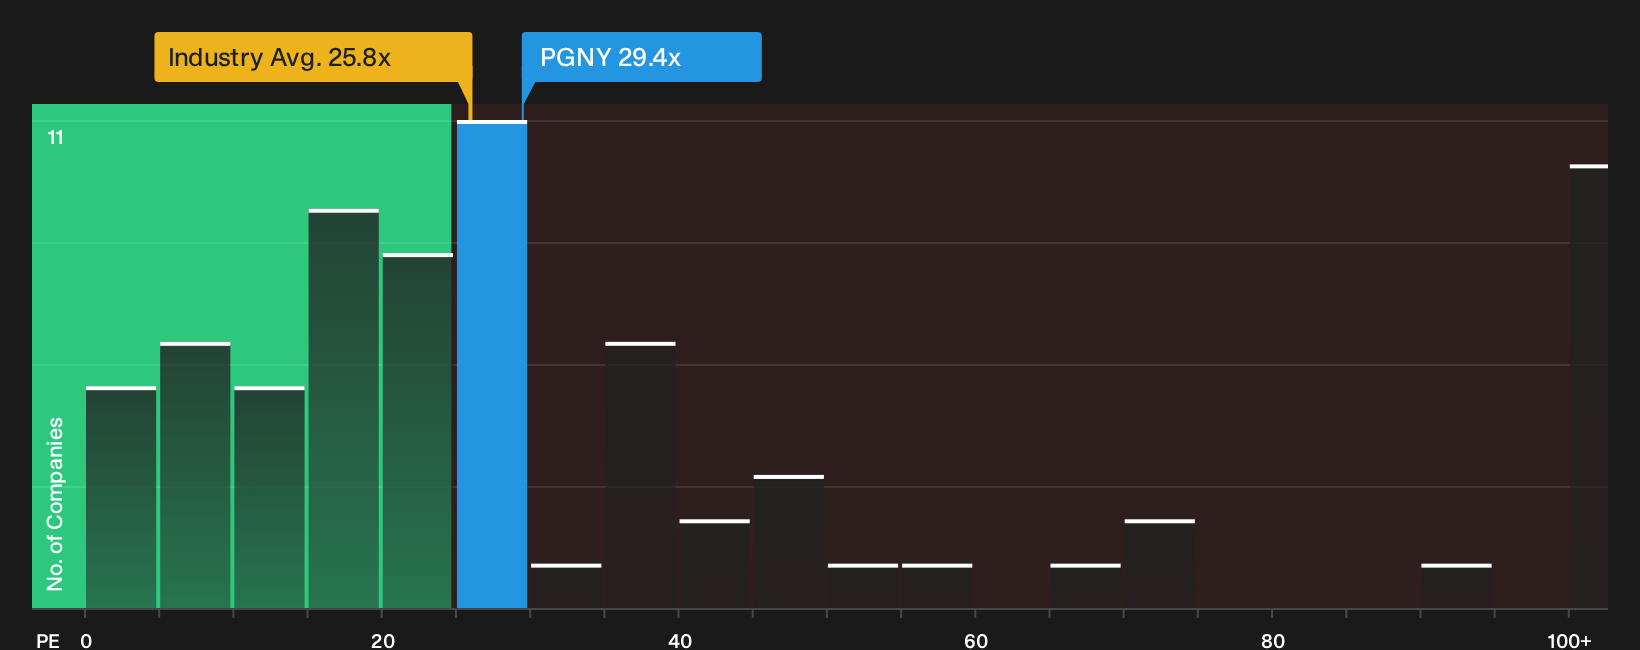
The P/E ratio is a useful shorthand here because Progyny is already earning profits and guiding to specific net income figures for 2026. On this measure, the shares trade at about 29.4x earnings, compared with roughly 25.8x for the broader Healthcare sector and around 40.5x for close peers. That leaves the stock priced at a premium to the sector but below the average of similar companies that investors currently favour.
The Fair Ratio framework, which adjusts the P/E multiple you might expect for Progyny based on its size, margins, growth profile and risks, points to a level slightly below where the shares trade today, so the tag looks about right rather than clearly cheap or expensive. Because management has recently lifted earnings guidance for 2026, the current valuation already reflects a fair amount of confidence in that profit outlook, yet it does not stretch the P/E to the higher peer average. Explore the numbers behind Progyny's P/E valuation.
The Progyny Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Progyny's valuation puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the current share price to appear meaningfully high or low. Each scenario links its numerical view to a clear stance on how Progyny's revenue trajectory, margins and risk profile could change, giving you a set of assumptions you can compare with new information as it appears on the Community page.
Progyny draws two very different reads from the community, with one camp seeing more upside in the current setup than the other.
Bull case: 13% undervalued
"Investment in a broader women's and family health platform, including menopause, postpartum support, leave assistance, navigation tools, and AI enabled care management, alongside 20% of existing clients and 40% of new clients already taking at least one newer product, creates room for higher revenue per client and potential margin support as these services scale..."
Discover why this Narrative puts Progyny at 13% undervalued.
Bear case: roughly fairly valued
"Although Progyny continues to report high engagement and record quarterly revenue, the recent cut to near term EBITDA guidance after a revenue beat suggests that rising platform and operating costs could absorb more of each incremental dollar of revenue, which would pressure future earnings quality and net margins..."
Explore why this Narrative puts Progyny at roughly fairly valued.
Progyny's price is only one piece of the decision
Share price and current earnings tell just part of the story, because a separate clue lies in where professional analysts expect Progyny to be a few years from now, and how that outlook lines up with today's tag. Explore where analysts expect Progyny to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com