


EN
DLocal (DLO) Could Be 73% Undervalued Before Its November 12 Earnings
DLocal (NasdaqGS:DLO) heads into its November 12 earnings release with investors watching for year over year gains in profit and sales, particularly in light of peer Global Payments reporting stronger than expected quarterly results.
DLocal’s recent trading tells a mixed story. The 1 day share price return of 5.46% lifted the stock to US$13.90, yet the 30 day share price return is down 4.27% and the 90 day share price return is down 5.89%, while the 5 year total shareholder return has fallen 67.50%, which indicates short term optimism alongside a much tougher long term experience.
Compare DLocal’s setup with other payment and fintech players by scanning a curated 19 high quality undiscovered gems that may be quietly building momentum behind the scenes.
DLocal’s rebound to US$13.90 after a long stretch of weaker returns puts a clear fork in the road for you. Is this the entry point, or do the numbers still argue for patience as valuation comes under the microscope next?
Most Popular Narrative: 73% Undervalued
DLocal’s last close at $13.90 sits far below a widely followed narrative fair value of $50.96. This frames earnings day against a strong value gap and puts the focus squarely on whether future cash generation can support that spread.
DLocal trades below the value implied by discounting its own free cash flow. On a two-stage model running 10 years of +25.0% growth fading to a 2.5% terminal rate, discounted at 9.8%, the shares are worth USD 50.96 against a market price of USD 15.24, a 70% discount, or +234% to fair value. 58% of that value sits in the terminal period, which is the honest caveat; the further out the cash flow, the more the answer is a statement about assumptions rather than about this year. The business earns 37.0% on invested capital on a 20.7% operating margin struck against 36.6% gross margins. Of USD 1.09B in trailing revenue, 40.0% converts all the way to free cash flow, and the balance sheet carries debt at 0.16 times equity, in fact a net cash position of USD 733.78M, which buys the time a levered peer would not have.
See why 8 investors see DLocal as 73% undervalued.
Result: Fair Value of $50.96 (UNDERVALUED)
Still, a slowdown in payment volumes or pressure on DLocal’s 20.7% operating margin could quickly challenge a valuation thesis built heavily on long range cash flows.
Find out about the key risks to this DLocal narrative.
Another View On DLocal’s Valuation
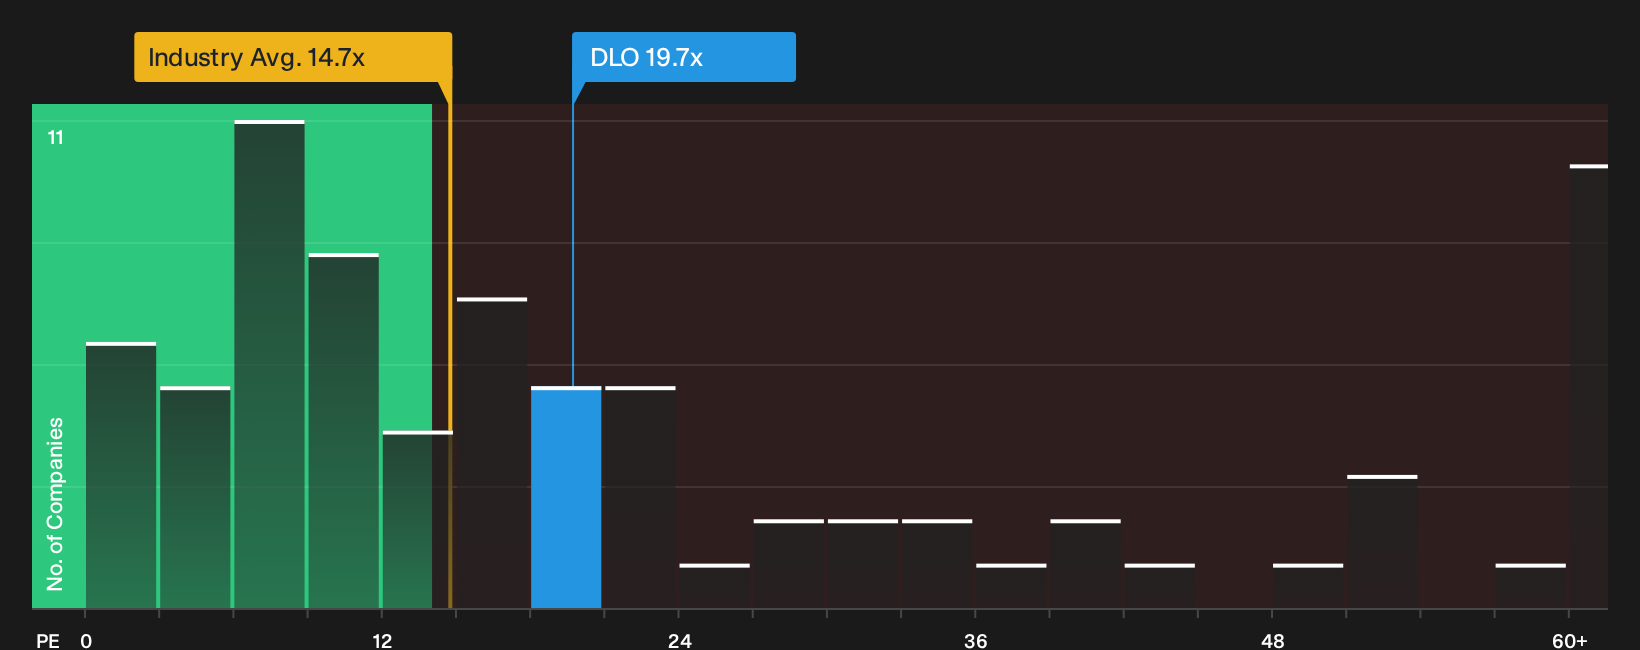
A second lens tells a different story. On earnings multiples, DLocal trades on a P/E of 19.7x. That is higher than the US Diversified Financial industry at 14.7x and above a fair ratio of 15.2x, which points to a richer price if the market drifts toward that fair ratio. Against peers on 43.9x, it looks cheaper, so which crowd do you think will set the reference point for this stock?
To see how those earnings multiples stack up in more detail and what they imply for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
All of this cautious optimism around DLocal is only useful if you pressure test it yourself and move before sentiment shifts again. Start by weighing the upside signals in the 4 key rewards.
Looking for more investment ideas beyond DLocal?
Do not stop your research with a single ticker. A broader watchlist gives you more options when prices or expectations shift without warning.
- Spot potential turnaround stories early by reviewing the 7 elite penny stocks with strong financials that pair lower share prices with stronger underlying financial profiles.
- Target quality at a discount by scanning the 35 high quality undervalued stocks that combine healthier balance sheets with pricing that screens below fair estimates.
- Dial back portfolio stress by focusing on the 31 resilient stocks with low risk scores that score better on volatility, debt levels, and earnings consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com