


EN
Earnings Beat Could Be A Big Deal For Lincoln Electric Stock
- Lincoln Electric Holdings reported third quarter 2026 basic earnings per share from continuing operations of US$2.65 and diluted earnings per share of US$2.63, with nine month basic and diluted figures of US$8.04 and US$7.97 respectively, all above the prior year levels.
- The sharper earnings per share performance over both the quarter and nine month period points to operating execution that supports the existing automation, RISE efficiency and pricing initiatives that investors have been tracking at Lincoln Electric Holdings.
- This article will explore how Lincoln Electric Holdings' higher quarterly earnings per share refine the investment narrative built around automation and margins.
Scan beyond Lincoln Electric Holdings and see how other automation and robotics plays are reacting to strong earnings trends by reviewing the 92 robotics and automation stocks in the same theme.
Lincoln Electric Holdings Investment Narrative Recap
To own Lincoln Electric Holdings, you need to be comfortable with a story built around automation demand, the RISE efficiency program and disciplined pricing in an inflation sensitive world. The latest quarterly earnings per share figures support the view that management is executing on that plan. The near term swing factor still looks like how effectively pricing and productivity offset cost pressure in logistics, energy and components.
The biggest operational risk remains margin pressure if inflation proves sticky or pricing power fades. Automotive weakness and Middle East disruptions are still watchpoints for volume and international profitability. The fresh earnings data does not erase those issues, but it reduces near term concern that they are derailing the broader plan.
The most relevant data point is the third quarter and nine month 2026 earnings release. Basic earnings per share from continuing operations reached US$2.65 for the quarter and US$8.04 for the nine month period. Diluted figures were US$2.63 and US$7.97. Each of these compares to lower levels a year earlier, which highlights progress through pricing, mix and efficiency work.
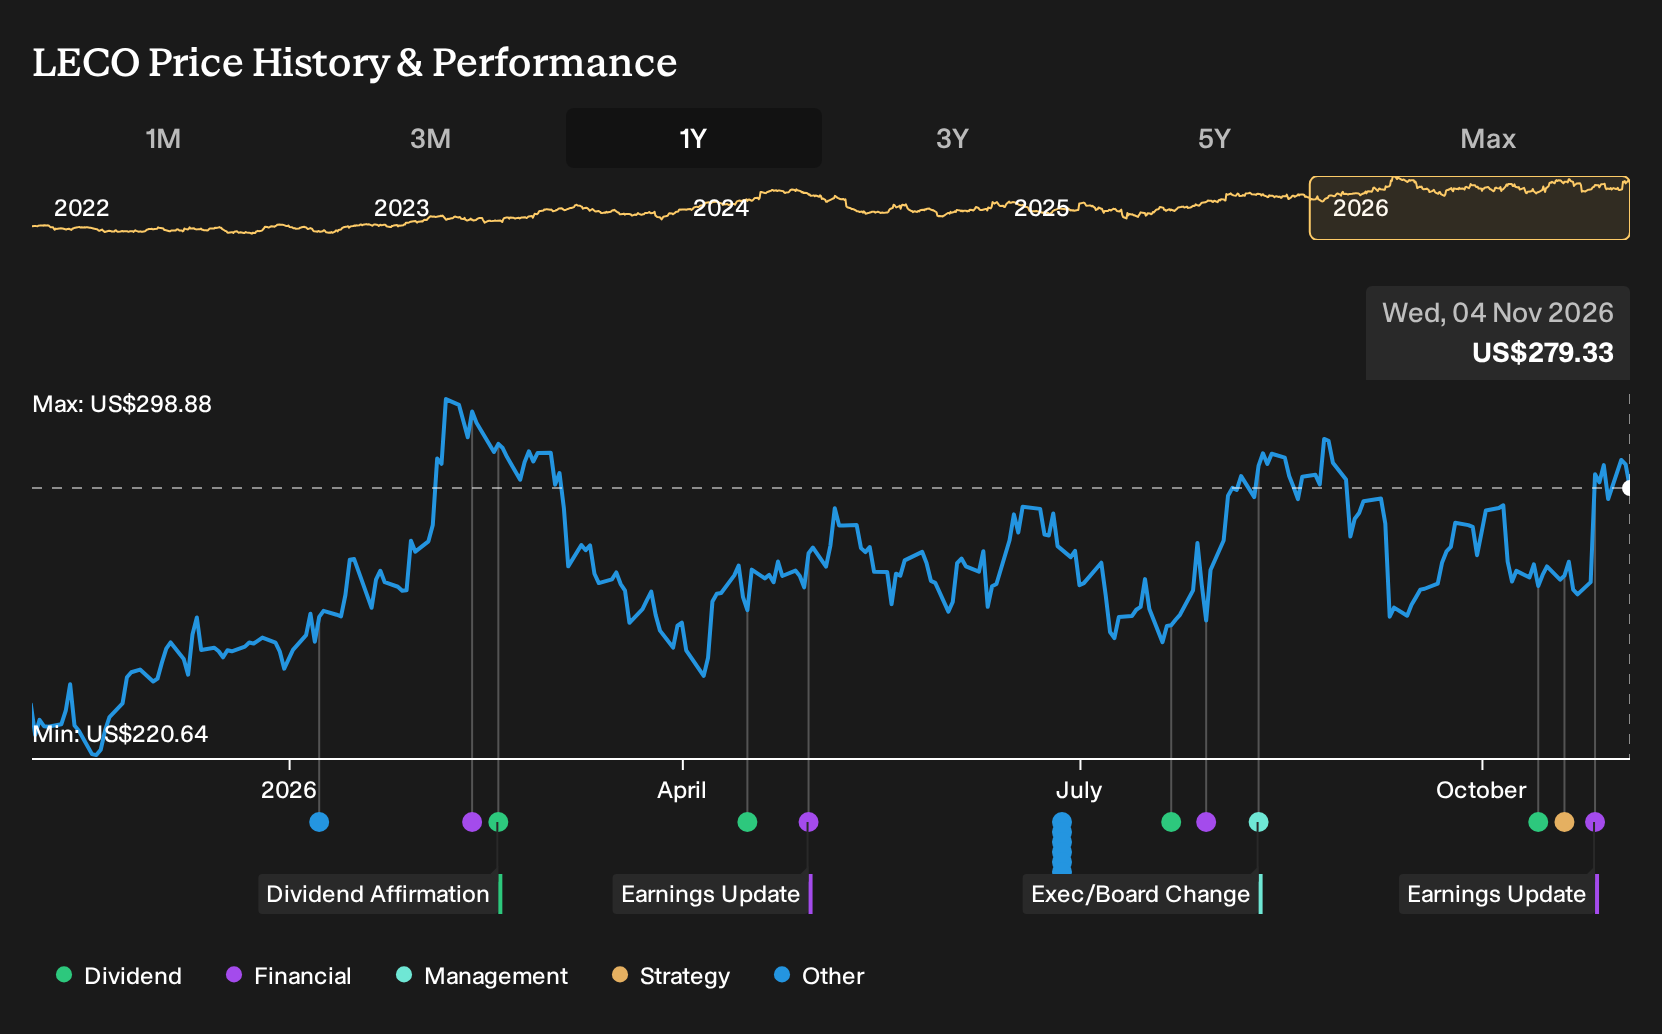
Those outcomes matter for the automation and RISE catalysts because they give you evidence that incremental margin targets and price cost neutrality remain key parts of the story. Recent estimate revisions and a strong share price move suggest analysts and short term traders have responded to that execution. The open question is how sustainable that performance is if automotive demand stays soft or geopolitical disruption persists.
What The Lincoln Electric Holdings Forecasts Assume
Lincoln Electric Holdings' narrative projects revenues of US$5.5 billion and earnings of US$778.7 million by 2029. Analysts are building that view on 6.9% yearly revenue growth and an earnings increase of about US$225 million from US$553.6 million today.
Uncover why Lincoln Electric Holdings' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Lincoln Electric Holdings’ valuation risk front and center. The lowest analysts were working off roughly US$5.3b in 2029 revenue and US$802.4m in earnings, yet still saw a lower future P/E near 21.3x. Those expectations came before this earnings beat, so you may see opinions shift. Consider both narratives carefully before assessing how they align with your own outlook.
Explore 4 other Lincoln Electric Holdings fair value estimates, including one that suggests it could be worth just $268.60.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lincoln Electric Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lincoln Electric Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lincoln Electric Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Lincoln Electric Holdings?
If Lincoln Electric Holdings' story around automation, earnings power and execution has sharpened your thinking, widen the lens and line it up against other potential opportunities using the Simply Wall St Screener. You can filter by quality, balance sheet strength or income profile so the watchlist you build reflects the kind of risk and reward mix that makes sense for you.
- For investors hunting for mispriced quality, compare Lincoln Electric Holdings with companies that have robust fundamentals using the 35 high quality undervalued stocks and see which ones justify a closer look.
- If capital preservation and resilience matter most to you, start with businesses that score well on financial strength through the 31 resilient stocks with low risk scores and build a shortlist that fits your risk comfort.
- Income focused investors can round out their research by scanning for reliable cash return potential via the 5 dividend fortresses and see which payers align with your yield and stability goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com