


EN
3 British Owner Operator Stocks With At Least 25% ROE
The Bank of England has just lifted interest rates to 4%, and signalled more to come, putting real pressure on heavily borrowed businesses. Founder led British companies often respond differently. Leaders with large personal stakes tend to watch every pound, rethink projects fast and protect long term value. This article highlights three such stocks from our founder focused screen that could merit a closer look now.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses, where leadership is heavily invested alongside you. However, if you want the pick of this theme, these 8 top founder-led companies are the best of the best.
Computacenter (LSE:CCC)
Overview: Computacenter is a founder-influenced IT services specialist that supplies and manages large scale technology infrastructure and support for corporate and public sector customers worldwide.
Operations: The group generates about £12.1b from computer services, with revenue spread across the UK, Germany, wider Western Europe and a sizeable North American footprint.
Market Cap: £5.1b
Computacenter links directly to the founder-led theme because long-tenured leadership still shapes multi year managed services and outsourcing deals. These are backed by a record product order backlog and higher recent earnings growth. Investors get a business built on recurring relationships and contract visibility. However, the real test will be what happens when one unseen pressure on those carefully built margins shifts.
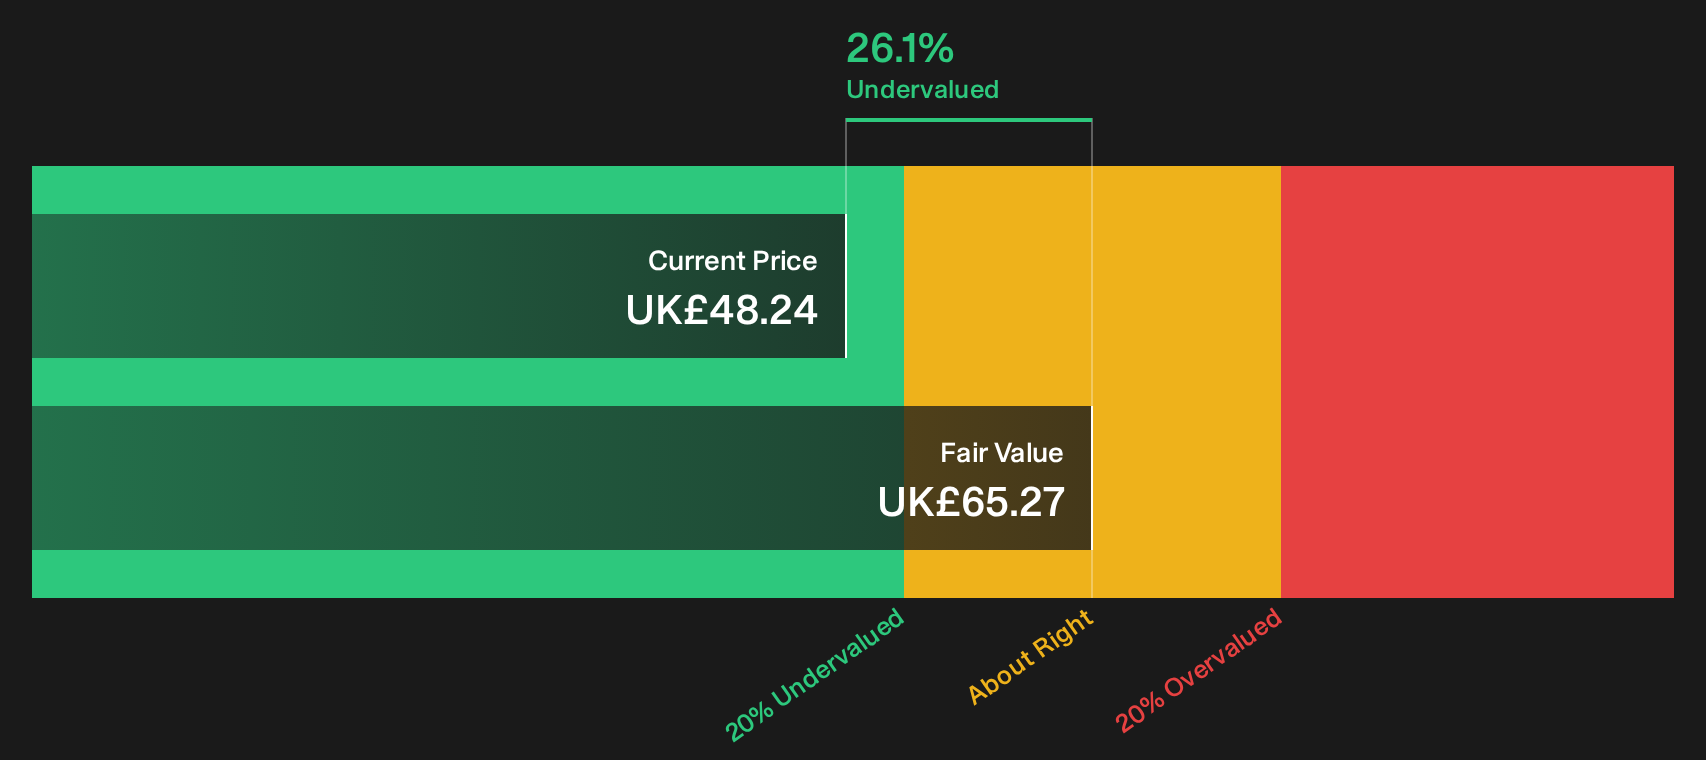
To see how that pressure could reshape returns at Computacenter, review the DCF valuation analysis for Computacenter and identify where contract strength might be masking valuation risk or upside.
Applied Nutrition (LSE:APN)
Overview: Applied Nutrition is a founder-led sports nutrition and wellness business that sells protein supplements, performance products and gym-focused accessories worldwide.
Operations: Applied Nutrition generates about £134 million from manufacturing and selling sports nutrition products, with roughly £58 million from the UK, £18 million across Europe and £58 million from other international markets.
Market Cap: £763 million
Applied Nutrition fits the founder-led theme because the core Applied Nutrition brand reflects a founder’s product vision translated directly into gym floors, retail shelves and shaker bottles.
"High reported free cash flow conversion of 72% in FY25, combined with an adjusted EBITDA margin of 29% and a net cash position, provides Applied Nutrition with room to pursue bolt-on capacity or capability investments that could add incremental revenue without materially increasing financial risk."
What really matters now is whether one quiet operational decision turns that financial headroom into sustained demand without eroding the current margin profile.
That quiet move is where the story really gets interesting, and the full narrative for Applied Nutrition shows how that financial firepower could accelerate or stall Applied Nutrition’s next phase.

Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is an asset manager that finances and scales founder-led private companies and real-asset projects across multiple regions.
Operations: Foresight Group Holdings generates about £164.9 million of fee income, with £114.8 million from Real Assets and £50.1 million from Private Equity.
Market Cap: £531 million
For founder-focused investors, Foresight Group Holdings matters because it does not just pick listed stocks. It raises and deploys pools of capital directly into founder and management-led businesses, then works alongside those teams to turn growth plans into fee income and long term value for its own shareholders.
"Acceleration in real assets deployment into energy transition projects, supported by a near doubling of deployment in the most recent year and over £3.6b of identified future deployment rights in international mandates, gives Foresight Group Holdings room to turn existing pipelines into higher management fees and potentially stronger EBITDA growth as those commitments are drawn."
What happens to earnings if one assumption about how quickly fresh fundraising converts into fee-paying capital proves too optimistic or too cautious?
If that timing risk matters to you, the full narrative for Foresight Group Holdings explains how Foresight Group Holdings could see fee income either accelerating or stalling as deployment pipelines convert.

Seeking Alternatives Before The Window Closes
Some opportunities move from quiet accumulation to full breakout before most investors even notice. Fresh ideas can get snapped up fast while it still matters. Get in early.
- Target steady cash generators and stress test your income plan against a curated set of 4 dividend fortresses before yields drop or spreads compress further.
- Spot potential future leaders early by scanning 5 high quality undiscovered gems while they are still flying under the radar for now and sentiment has not fully caught up.
- Position ahead of potential infrastructure momentum by checking 41 power grid technology and infrastructure stocks before funding cycles, regulation and project pipelines get fully priced into valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com